

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LED Strip Market set for USD 11.02B by 2032 with 9.6% CAGR

LED Strip Market 2026: Strategic Imperatives for Rapidly Scaling Opportunities
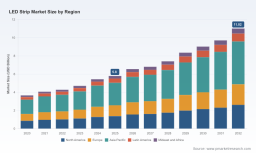
The LED strip market is at an inflection point. With a compound annual growth rate (CAGR) of 9.6% anchored to a 2025 base year, total addressable revenue has roughly doubled from the early 2020s and is projected to continue expanding through our 2032 horizon. For executives planning capital allocation, product roadmaps, and channel strategies in 2026, this research is designed to convert macro momentum into executable, low-regret actions while spotlighting the operational and regulatory levers that will determine winners in the next three years.
LED Strip Market
Why this study matters for 2026 decision-making
- Translate growth into profitable scale: High headline growth does not guarantee margin expansion. Our analysis differentiates top-line opportunity from sustainably profitable adoption by isolating where value migrates (product premiumization, systems integration, and recurring services) versus where commoditization compresses returns.
- Prioritize roadmap investments: The market is bifurcating between highly integrated, smart lighting systems and high-performance, specification-driven strips for commercial/industrial uses. The report maps where R&D and certification spend will produce the highest ROI in 2026–2028.
- Derisk supply chains strategically: Raw material volatility, certification timelines, and evolving regulation present concentrated operational risk. We quantify exposure points and present mitigation playbooks that can be actioned within 6–12 months.
- Target M&A and partnership windows: With measured market concentration and large numbers of specialty suppliers, we identify archetypal targets and partnership structures that accelerate access to end-markets without repeating costly build cycles.
- Operationalize compliance as a competitive advantage: New high-end color and safety standards are reshaping buyer expectations. The report turns regulatory compliance from a cost center into a product differentiator in procurement conversations.
What the report contains — practical, actionable deliverables
- Bottom-up demand model: A proprietary, scenario-capable model spanning 2020–2032 (base year 2025) that reconciles historical adoption curves with technology substitution dynamics and service revenue assumptions.
- Revenue and margin scenarios: Three stress-tested pathways (constrained, baseline, accelerated) that show how pricing, BOM optimization, and channel mix drive EBITDA outcomes through 2032.
- Commercial playbooks: Tactical GTM bundles for OEMs, lighting contractors, and retail brands, including channel economics, sales comping, and promotional hygiene for 2026 launch windows.
- Product-specification scorecards: Decision matrices that map CRI, SDCM, IP ratings, and driver integration options to monetization levers across residential, commercial, and industrial use cases.
- Supplier and risk matrix: A prioritized list of raw-material and supplier risks (with mitigation options such as dual-sourcing, hedging, and design-to-material substitutions) and time-to-implement estimates.
- Competitor dossiers and pricing benchmark: Executive summaries and go-to-market positions for the market’s leading vendors, plus a pricing ladder and margin sensitivity analysis.
- Regulatory scenario planning: Tailored playbooks for RoHS compliance, UL certification timelines, and color-imperfection remediation, including estimated compliance cost bands and supplier contract language.
- Downloadable assets: A modular Excel model, slide-ready market maps, and an executive decision checklist designed for board-ready briefings.
Market structure and concentration — what leaders should know
The LED strip market presents meaningful room for both scale players and specialist challengers. Measured concentration is modest: the combined share of the three largest suppliers is limited, and even the five-leader block leaves substantial share for nimble incumbents and regional specialists. That structure creates two strategic playbooks that work in parallel in 2026: (1) platform-led scale (integrated smart systems, global distribution), and (2) niche specialization (spec-driven strips for automotive, industrial, and high-color-fidelity applications).
LED Strip Market
Competitive landscape — profiles and tactical implications
- Philips Hue (Netherlands): Positioned as a premium smart lighting leader, Philips Hue’s expansion into gradient and outdoor Neon strips signals a push to own decorative and architectural ecosystems. Their delayed regional rollouts highlight the execution risk in global launches; premium feature sets will command higher ASPs but require strong inventory and channel coordination.
- LEDVANCE (Germany): Focused on professional and modular systems, LEDVANCE’s trade-show presence and project-oriented offerings make them a first-choice partner for commercial and institutional installers. Their approach underscores the importance of systemization — drivers, profiles, and service contracts — to capture larger project-level margins.
- Govee (United States): Govee’s product cadence (RGBIC, COB, and the recent Lumiblend+ color accuracy tech plus AI lighting bot demoed at CES 2026) demonstrates how consumer-tech speed and data features can rapidly commoditize lower tiers while opening services-led adjacencies (apps, subscription features).
- OSRAM (Germany): With a strong automotive and entertainment lighting lineage, OSRAM’s high-performance modules position them advantageously for interior automotive retrofits and specialized entertainment installations — segments where certification and endurance testing create higher barriers to entry.
- HitLights, Flexfire LEDs, Super Bright LEDs (US): These players emphasize professional-grade outputs, high-density COB offerings, UL listings, and installer-focused accessories — a playbook that converts product reliability and spec-accuracy into repeat business with contractors and systems integrators. Recent tactical moves include Flexfire’s strategic bulk-pricing and price reductions announced in early 2026 — a sign that price competition in project segments may intensify.
Regulatory and raw-material dynamics to model now
- RoHS exemption expirations (July 21, 2026): The lapse of several lead-related exemptions requires immediate product and supply-chain reassessment for companies relying on legacy alloys or ceramic/glaze processes. Lead-time for alternative certs and material validation can extend several quarters.
- Certification expectations: UL certification continues to be a gating factor for U.S. market access; concurrently, high-end segments are consolidating around color-quality thresholds (CRI 90+ and SDCM ≤3). Meeting both safety and color fidelity requirements is now table stakes for premium segments.
- Raw-material inflation and security: A sharp copper price move in 2025 — upward of thirty-some percent — materially lifted BOMs and has driven opportunistic copper theft from assemblies. Mitigation requires supply contracts, alternative board designs, and physical security measures for distribution and warehousing.
2026 tactical playbook — three priority moves
- Fast-track high-value certification: Prioritize UL and high-CRI compliance for SKUs targeting commercial and premium residential channels. Certification timelines must be built into 2026 launch schedules and CAPEX plans.
- Segment-focused product tiers: Introduce a three-tier portfolio (value, professional, flagship) that balances rapid reflow of commodity SKUs with higher-margin, spec-driven offerings that require certification and services-bundling.
- Hedge supply and secure BOMs: Negotiate multi-year offtake or price collars for copper and critical components; consider design-for-material-reduction exercises and selective vertical integration for strategic components.
Where this preview stops — and why you should access the full dataset
To preserve the strategic value of this preview while offering immediate, operational insight, we intentionally limit disclosure of granular segment-level revenue splits and region-by-application percentages in this article. The full PW Consulting LED Strip Market report contains the proprietary line-item segmentation, region and application matrices, competitive benchmarking tables, and the downloadable demand model that enable transaction-level decision-making — from SKU rationalization to acquisition target screening.
LED Strip Market
If your 2026 planning requires precise allocation of R&D dollars, a prioritized M&A shortlist, or merchant-level pricing ladders tied to expected channel mix, the full report converts directional intelligence into executable milestones and financial-ready scenarios.
Conclusion — actionable urgency
The headline growth and favorable long-term demand trajectory present compelling upside, but the path to capturing sustainable margin is narrow and time-bound. Certification commitments, supply-chain reengineering, and the ability to translate features into service-enabled revenues will distinguish leaders from followers in 2026. This research is built to shorten the runway from insight to action: offering the models, scenario playbooks, and competitor intelligence needed to make defensible decisions now. For the complete market architecture, proprietary models, and the granular segmentation critical to investment-grade decisions, access the full report and supporting assets.
For detailed analysis of this topic, please visit the official page: LED Strip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com