

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: EPDM Market to Reach USD 7.03B by 2032 at 5.0% CAGR

EPDM Market 2026: Strategic Briefing for Decision-Makers
As EPDM moves from a mature commodity to a strategic material in automotive, construction and industrial applications, 2026 will be a pivotal year for corporate choices around capacity, sourcing and product positioning. This preview of PW Consulting’s latest Ethylene Propylene Diene Monomer (EPDM) Market study synthesizes the high‑level, decision-relevant signals you need now — while intentionally withholding the granular segment tables and proprietary allocations contained in the full report to preserve the strategic value of our primary research.
Ethylene Propylene Diene Monomer (EPDM) Market
Market snapshot: scale, trend and near-term trajectory
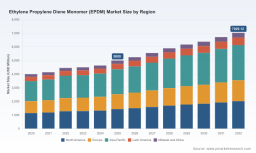
By PW Consulting’s accounting (base year 2025), the global EPDM market reached approximately USD 5,000 Million, up from roughly USD 4,000 Million in 2020. Under a baseline outlook we model a steady compound annual growth rate of about 5.0% across 2026–2032, with total market value rising toward the low‑seven‑billion USD range by 2032. The market’s mid-single-digit CAGR masks material variation in end‑use demand, feedstock sensitivity and regulatory exposure — factors that should shape near‑term corporate priorities.
Ethylene Propylene Diene Monomer (EPDM) Market
Why 2026 matters: three strategic inflection points
- Regulatory compression around recycled content and taxation risk. Policy moves are converging on both sides of the Atlantic: recycled content mandates for packaging (and related pressure on elastomer use in automotive and industrial components) are accelerating customer and OEM requirements, while tax/regulatory proposals in major jurisdictions are elevating the risk profile of certain raw polymer categories. These developments will reframe cost, compliance and product specification conversations with buyers.
- Supply architecture reconfiguration. Producers are starting to react to demand recovery and sustainability pressures with capacity adjustments and site reinvestments. Announced capacity restarts and expansions in 2025–2026 alter near‑term supplier bargaining power and create windows for downstream players to lock favorable terms or to diversify suppliers strategically.
- Consolidation and competitive positioning. The market exhibits a moderate level of concentration: the top three producers account for a meaningful share of global supply, and the top five further broaden that footprint. This structure produces both risk (single‑supplier constraints in specific product classes) and opportunity (strategic partnerships and selective vertical integration).
Key dynamics shaping commercial outcomes
- Demand heterogeneity. Growth drivers in automotive, building & construction, and wires & cables remain intact, but demand intensity, specification complexity and lead‑time sensitivity differ substantially by end‑use. Commercial teams need to translate product roadmaps into differentiated go‑to‑market propositions rather than rely on volume plays alone.
- Feedstock and input cost volatility. EPDM economics remain linked to ethylene/propylene markets and to energy dynamics. Procurement flexibility — via tolling, long‑term offtake agreements, or co‑location strategies — will materially affect margin stability across scenarios.
- Sustainability and product reformulation pressure. OEM and regulatory pressure for recycled content and lifecycle performance is accelerating reformulation R&D and scale trials. Players that can validate recycled‑content EPDM at automotive performance levels will command pricing premiums and preferred supplier status.
- Regulatory tail‑risks. Recent filings seeking to change tax treatment of certain elastomers highlight a non‑zero probability of retroactive cost impacts or additional compliance burdens. Proactive tax and regulatory scenario planning is now a board‑level priority for exposed companies.
Competitive landscape — what the major players are doing
The market is served by a mix of global petrochemical majors, specialty elastomer producers and regional champions. Each competitor follows distinct strategic archetypes: global scale players pursuing integrated feedstock-to‑polymer advantages; specialty firms focusing on grade differentiation and application engineering; and regional providers leveraging localized cost or customer intimacy.
Ethylene Propylene Diene Monomer (EPDM) Market
- Integrated majors (example profile) — Companies with integrated petrochemical value chains deploy branded EPDM elastomers aimed at high‑volume, industrial specifications. Their scale enables investment in grades for weatherability and performance and supports broad distribution networks.
- Specialty elastomer houses (example profile) — These firms emphasize differentiated EPDM grades and technical support for OEMs, investing in compound development, application testing and co‑development programs with Tier‑1 customers.
- Regional and cost‑focused competitors (example profile) — These producers target local markets with competitive pricing and faster commercial response, often serving converters and downstream compounders where logistics and lead times are decisive.
Our report includes focused company dossiers covering the leading producers, their brand portfolios and their strategic moves (including recent capacity announcements). A representative development with sectoral implications: a July 2025 announcement to restart additional production capacity in the United States underscores the immediacy of supply repositioning — a lever that will influence procurement negotiations and spot market behavior through 2026.
Strategic implications and recommended actions for 2026
- Scenario‑based procurement strategies. Build layered sourcing models (short‑term spot + medium‑term contracts + strategic partnerships) that preserve flexibility while securing critical volumes. Stress‑test contracts against potential tax/regulatory outcomes and include review clauses tied to recycled‑content mandates.
- Prioritize product and application segmentation. Move beyond volume segmentation toward value segmentation: define premium grade pathways (e.g., higher durability, validated recycled content, lower lifecycle carbon intensity) and align pricing and service models to capture margin uplift.
- Accelerate validation of recycled content. Invest in accelerated testing and co‑development with OEMs to shorten qualification timelines. Early movers that can certify recycled‑content EPDM for demanding automotive applications will gain durable commercial advantages.
- Capex and footprint recalibration. Reassess greenfield and brownfield investments against a 5% CAGR baseline and alternative downside/upside scenarios. Consider capacity flexibility (modular lines, tolling agreements) over large irreversible investments in uncertain regulatory environments.
- M&A and alliance playbook. Use the current market structure to evaluate bolt‑on acquisitions that provide technical capability (e.g., compounding, specialty grades) or regional market access. Partnerships with recyclers and compounders can accelerate capability creation at lower capital cost.
What PW Consulting’s full EPDM Market report delivers
This briefing is a strategic trailer. The complete study provides hands‑on tools and proprietary data designed to convert insight into action for 2026 planning cycles:
- Detailed market model (historical 2020–2025, base year 2025, forecast 2026–2032) with scenario toggles for price, demand shock and regulatory outcomes.
- Proprietary demand matrices and application-specific adoption curves, including validated OEM specification timelines and qualification hurdles.
- Comprehensive competitive dossiers on the leading producers, including product portfolios, grade mappings, capacity footprints and strategic initiatives.
- Supply chain heat maps and risk indices that connect feedstock exposure, logistics complexity and supplier concentration to commercial risk metrics.
- Actionable playbooks: procurement templates, CAPEX prioritization frameworks, commercial segmentation strategies and an M&A screening tool tailored to EPDM.
- Regulatory impact assessment, including tax scenarios and recycled‑content compliance pathways with quantified margin and cost-to‑serve implications.
To protect the integrity of our primary research and to ensure commercial exclusivity, we have purposefully withheld the granular regional and application split tables in this preview. The full dataset—containing detailed regional, type and application allocations, supplier share by grade, and downloadable financial models—is available through our publication portal.
How to use this briefing in your 2026 planning
- Deliverable alignment: use the high‑level scenarios herein to challenge budget assumptions and to prioritize options in your Q1 corporate planning cycle.
- Immediate operational moves: assess short‑term supplier agreements for flexibility clauses and begin pilot testing of recycled‑content blends with key OEMs.
- Board‑level conversation starters: present the regulatory and tax risk scenarios to the audit and risk committee, and commission a focused regulatory impact study if your exposure is material.
PW Consulting stands ready to support execution—whether that means running supplier negotiations, building a recycled‑content validation roadmap, or modeling the cashflow impact of capacity options under alternative regulatory futures. For teams that require the full dataset and executable tools to finalize 2026 commitments, the complete EPDM Market report provides the granular intelligence and operational templates needed to act with confidence.
Next step
Access the full report to unlock the detailed segmentation, supplier share matrices and the Excel model that power actionable decisions for 2026 and beyond. Our analysts are available for briefing sessions that map the findings directly to your portfolio and go‑to‑market plans.
For detailed analysis of this topic, please visit the official page: Ethylene Propylene Diene Monomer (EPDM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com