

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Natural Astaxanthin Market Poised for 9.1% CAGR through 2032
By pmarketresearch, 2026-07-09
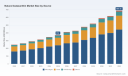
Natural Astaxanthin Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s senior strategy advisor and lead industry analyst, I present an executive field guide to the natural astaxanthin market intended to orient corporate decision-making in 2026. Built on a base-year analysis (2025) and a calibrated historical series (2020–2025), our study projects the market through 2032. At the macro level the market has grown from roughly USD 249 million in 2020 to approximately USD 372 million in 2025 and is forecast to approach USD 686 million by 2032 — reflecting a compound annual growth rate (CAGR) of 9.1% over the projection window. These headline dynamics frame the near-term choices that will determine commercial and strategic winners in the next three to five years.
Natural Astaxanthin Market
Why this study matters in 2026
-
Strategic timing: 2026 is the inflection year for several structural shifts — regulatory clarity in key markets, new industrial-scale capacity coming online, and the maturation of higher-value product formulations. Our study translates these shifts into decision-ready implications for supply, pricing and go-to-market timing.
Natural Astaxanthin Market -
Capital allocation: With a mid-single-digit-to-double-digit growth trajectory, executives must choose where to allocate scarce CAPEX — brownfield capacity, closed-system photobioreactors, downstream formulation lines, or bolt-on acquisitions. The analysis converts growth and margin assumptions into actionable investment thresholds.
Natural Astaxanthin Market -
Risk-adjusted planning: Concentration metrics matter. The market shows meaningful supplier concentration among top players, informing counterparty risk, negotiating leverage, and M&A opportunities for vertically integrated or geographically diversified entrants.
-
Regulatory urgency: Recent and imminent regulatory rulings create both barriers and openings for product innovation and market access. The report maps regulatory scenarios to product-level commercialization pathways.
What the report delivers (practical & operational)
-
Transparent market-sizing and forecasting framework — methodology, assumptions, and sensitivity tables so finance teams can re-run scenarios under alternate price, yield and adoption curves.
-
Scenario-driven demand models — three to five demand trajectories calibrated to end-market adoption (nutrition, aquaculture, cosmetics and food), with triggers that materially change the outlook.
-
Supply-side cost curves and break-even maps — production economics for open-pond vs closed photobioreactor systems, conversion yields, and unit cost drivers for extract vs powder vs oil formats.
-
Supply chain and raw-material mapping — supplier concentration, logistics bottlenecks, and a supplier due-diligence checklist tailored to the astaxanthin value chain.
-
Regulatory & compliance playbook — jurisdictional risk matrices, dossier templates, and mitigation steps for differences in food/novel food and feed regimes.
-
Commercial playbooks — optimal route-to-market by customer archetype, pricing models, and product positioning for premium vs cost-sensitive segments.
-
M&A and partnership scorecards — screen criteria, valuation anchors, and integration risk checklists designed to prioritize targets that accelerate market entry or secure feedstock.
-
KPIs and monitoring dashboard — real-world metrics for procurement, production, regulatory milestones and commercial traction to operationalize governance.
Key market dynamics shaping 2026 choices
-
Demand composition and growth: Robust expansion is being driven by multi-sector demand (human nutraceuticals, aquaculture/animal feed, cosmetics and functional food ingredients). While each application carries distinct margin and regulatory profiles, the aggregate market trajectory provides room for both premiumization and scale plays.
-
Supply constraints and feedstock reality: Natural astaxanthin production is intrinsically linked to Haematococcus pluvialis biomass. Market intelligence points to a global commercial production scale of roughly 800 metric tons annually for H. pluvialis powder — a critical figure for supply planning and contract negotiations. Capacity additions announced by several producers will relieve some pressure, but geographical and technological concentration still creates sourcing risk.
-
Technology divides: Producers continue to differentiate by cultivation systems (open-pond vs closed photobioreactors), downstream extraction platforms, and formulation technologies that improve bioavailability and stability. Closed systems command a premium in contamination-sensitive markets (e.g., human nutraceuticals and cosmetics), while open-pond systems can be cost-competitive for bulk feed applications.
-
Regulatory inflection points: Recent EFSA developments (December 2025) have tightened the assessment of algal meal and oleoresin uses in non-supplement applications when exposure exceeds established ADI thresholds. This sharpens the distinction between food-supplement pathways and broader food/feed approvals. Separately, key industry players have progressed formal novel-food engagement, underscoring that regulatory strategy will be a gating factor for product expansion.
-
Concentration and negotiating leverage: The market exhibits moderate concentration at the top; recent CR metrics indicate the top three players control a substantial share and the top five command a clear majority. For buyers, that reality raises the importance of multi-sourcing, long-term offtakes, and backward integration options.
Competitive landscape — strategic positioning of core players
-
AstaReal Inc. (Sweden) — positioning: technology-led premium supplier. Strengths include patented cultivation systems, a strong reputation in high-purity extracts and active involvement in standards and monograph development. Strategic implication: ideal partner for brands seeking traceability and regulatory-compliant formulations.
-
Cyanotech Corporation (United States) — positioning: integrated low-cost producer with buoyant consumer-brand heritage. Recent margin improvements reflect scale benefits in open-pond production and operational leverage. Strategic implication: attractive supplier for cost-sensitive formulations and bulk supply agreements.
-
Algatechnologies Ltd. (Israel) — positioning: high-purity, closed-system supplier targeting premium nutraceuticals and softgel formats. Product line extensions aimed at convenience and bioavailability are a clear premium play.
-
Beijing Gingko Group (China) — positioning: large-scale incumbent with aggressive capacity expansion and strong domestic supply chains. Recent announcements signal intent to extend global reach; vigilance on quality certifications and export compliance is essential for international buyers.
-
Algalif Iceland, Fuji Chemical and Divis Laboratories — positioning: complementary capabilities across production scale, formulation development and ingredient supply. These players present varied options for partnership, toll-manufacturing and vertical integration.
-
Recent moves to watch: plant expansions, margin improvements and new product introductions (e.g., premium formulations for softgels) are reshaping competitive economics and creating short-term supply ripples.
Strategic implications — eight tactical decisions for 2026
-
Secure prioritized feedstock: Negotiate tiered offtake contracts with volume and quality collars tied to P&L breakeven scenarios. Consider joint-venture cultivation partnerships to secure long-term supply.
-
Calibrate CAPEX to spread risk: Defer large greenfield builds in favour of modular expansion and tolling arrangements until regulatory and demand signaling firm up.
-
Differentiate by formulation: Invest in formulation R&D (bioavailability, water-dispersible systems) to command premium pricing in nutraceuticals and cosmetics.
-
Prioritize markets by regulatory clarity: Fast-follow jurisdictions with clear novel-food pathways and strong consumer demand; plan controlled pilot launches in riskier jurisdictions only after dossier milestones.
-
Pursue tuck-ins to secure capabilities: Use conservative valuation multiples from our screening tool to selectively acquire upstream feedstock access, downstream formulation tech, or customer lists to accelerate commercialization.
-
Implement active price-management: Build dynamic pricing models tied to biomass availability, extraction yield volatility and FX exposure; protect margins with forward purchase agreements where feasible.
-
Operationalize sustainability and traceability: Buyers increasingly require certified claims; investing in chain-of-custody and sustainability audits creates commercial differentiation and reduces buyer friction.
-
Engage regulators early and visibly: Coordinate submission strategies around novel-food dossiers and feed additive thresholds to avoid last-minute commercialization delays.
How PW Consulting can accelerate your 2026 agenda
-
Tailored scenario modelling — we re-run the forecast under your price, yield and product mix assumptions and provide investment-aligned sensitivity tables.
-
Supplier due-diligence & contracting playbook — on-the-ground supplier audits, contract templates and negotiation support focused on quality, delivery and force majeure clauses specific to algal supply.
-
Regulatory dossier and stakeholder engagement — drafting support for novel-food submissions, feed additive dossiers and EFSA-style risk responses; regulatory roadmaps for prioritized markets.
-
M&A origination and integration planning — target screening, valuation, and 100-day integration blueprints to convert acquisition intent into accretive outcomes.
-
Commercial launch & channel strategy — go-to-market staging, pricing architecture and digital channel playbooks for nutraceutical and cosmetics customers.
Our full market research product contains proprietary segment-level forecasts, supplier-level cost curves, and granular application and regional splits that are deliberately omitted here to preserve the value of the primary intelligence. If your 2026 plan depends on precise volume/price thresholds, supplier sourcing maps, or product-level margin tables, access to the full dataset and the accompanying scenario model is essential.
Contact PW Consulting to request the full Natural Astaxanthin Market report and bespoke advisory support to convert the market’s growth and regulatory transitions into a clear, executable roadmap for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Natural Astaxanthin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PDMS Market — 11.2% CAGR (2026–2032), USD 888.06M in 2025
By pmarketresearch, 2026-07-09
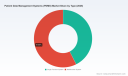
Patient Data Management Systems (PDMS) Market — Strategic Briefing for 2026 Decision-Makers
As healthcare providers, technology vendors and investors recalibrate strategy for a post-pandemic, digitally accelerated care environment, Patient Data Management Systems (PDMS) sit at the intersection of clinical workflow optimization, device connectivity and regulatory compliance. This briefing synthesizes the macro dynamics from PW Consulting’s upcoming PDMS market study to highlight the strategic imperatives that will matter for 2026. It is a purposeful preview: we reveal analytical depth and directional conclusions while preserving the granular segmentation and proprietary forecast tables for the complete report.
Patient Data Management Systems (PDMS) Market
Why this research matters for 2026
Hospitals and health systems face compressed decision windows in 2026: capital cycles, regulatory deadlines, and cybersecurity exposures are converging. Our study quantifies the market trajectory and maps the operational pressures that will determine winners and losers. At a high level, the PDMS market demonstrates robust expansion — the sector is forecast to grow at a strong double-digit compound annual growth rate into the next decade, with total market size roughly doubling over the forecast horizon. This pace underscores both the urgency and the opportunity for investment in interoperable, secure PDMS implementations.
Patient Data Management Systems (PDMS) Market
Top-line market context
- Base year and horizon: Our analysis is anchored on 2025 as the base year with a 2026–2032 forecast horizon to capture near-term policy cycles and mid-term technological adoption curves.
- Growth profile: The market is growing at an accelerated clip, driven by hospital digitization programs, acute care modernization, and cloud-native platform transitions. This creates a multi-year window for capture of incremental PDMS revenue and services.
- Commercial structure: The competitive landscape blends specialized PDMS vendors with broader medical device and health IT suppliers. Market control is concentrated among established vendors that combine clinical domain expertise with device integration capabilities.
Market dynamics shaping 2026 decisions
- Regulatory and standards pressure: PDMS are regulated as medical devices in many jurisdictions, requiring documented risk management and compliance pathways. New guidance is increasingly embedded within PDMS feature baselines, which shortens development-to-deployment cycles for compliant offerings but raises the bar for validation and documentation during procurement.
- Public funding and national programs: Targeted funding initiatives in some countries have accelerated PDMS adoption in acute care settings. Buyers capitalizing on such funding windows can leapfrog legacy constraints, but must align procurement timelines with grant or subsidy conditions.
- Cloud transformation vs. operational resilience: Several major hospital programs are transitioning to cloud-based EPD/HIS platforms. Cloud migration enables scalable PDMS integrations and analytics but creates new attack surfaces and operational dependencies, as recent ransomware incidents in the region have starkly demonstrated.
- Workforce constraints and automation ROI: Staff shortages and nursing workload pressures make automated data capture, closed‑loop medication support and streamlined documentation not just efficiency plays but essential risk mitigation measures. PDMS implementations must therefore be assessed for both direct efficiency gains and indirect clinical safety benefits.
Technology and integration trends
- Device-first interoperability: Successful PDMS projects are those that treat device connectivity as a primary product requirement — ventilators, monitors, infusion pumps and OR devices must feed reliable, timestamped data streams into a single clinical view.
- From point solutions to ecosystem platforms: The market is evolving from single-function modules toward multifunction, hospital-wide platforms that link PDMS, HIS/EPD and middleware. Buyers must decide whether to prioritize best-of-breed clinical depth or vendor-managed integrated stacks that promise faster time-to-value.
- Closed-loop medication and clinical decision support: Integration with medication management and traceability features is moving from “nice to have” to expected baseline functionality in acute care PDMS deployments.
- Security and resiliency engineering: Cybersecurity must be embedded across the PDMS lifecycle — procurement, implementation, and operations. Incident preparedness and recovery are now differentiators in vendor evaluation.
Competitive landscape — what to watch
Our competitive analysis profiles both specialist PDMS providers and broader health IT manufacturers. Several incumbent and regional leaders stand out for different strengths:
Patient Data Management Systems (PDMS) Market
- NEXUS AG (Germany) — Known for certified PDMS integrations that tightly couple ICU device connectivity with hospital information systems (HIS). Their offerings emphasize medication management, nutrition balance and pediatric-specific functionality, positioning them well in specialized acute care workflows.
- Dräger (Germany) — Offers a suite geared toward centralized data management across ICU, OR and NICU environments, with a strong record in monitoring and traceability of prescriptions. Their proposition is attractive for hospitals seeking deep acute care monitoring alignment.
- BIOMEDICA Medizinprodukte GmbH (Germany) — Focused on anaesthesia and intensive care departments with solutions that centralize documentation and improve cross-hospital communication and data quality. Recent deployments illustrate their ability to deliver standardized documentation across multiple institutions.
- ChipSoft B.V. (Netherlands) — Integrates PDMS functionality into broader electronic patient dossier (EPD) platforms with hospital-wide device communication. Their pivot to cloud-native HIS/EPD architectures highlights both the upside of modernization and the operational risks associated with cyber events.
Recent vendor developments exemplify the market’s trajectory and the new risk/return calculus:
- BIOMEDICA’s recent multi-hospital PDMS deployment demonstrates the acceleration of standardized documentation across provincial healthcare networks.
- ChipSoft’s cloud migration programs show how cloud-enabled HIS/EPD initiatives can accelerate integrations, while a contemporaneous ransomware incident underscores the need for rigorous cybersecurity contingencies in vendor selection.
- Industry showcases and integrations (e.g., DMEA 2026 demonstrations) confirm an acceleration in closed-loop and point-of-care integration propositions from niche integrators and device partners.
Strategic implications for 2026 planning
For executive teams, purchasing leads and investors, the study converts macro signals into actionable strategy options:
- Procurement timing: Align capital and implementation schedules with national funding cycles and regulatory deadlines. Early movers who secure grants and start integration projects in 2026 can realize disproportionate operational benefits in the following years.
- Vendor selection framework: Elevate cybersecurity, device interoperability and regulatory-ready documentation to primary selection criteria. Don’t trade clinical depth for integration convenience unless total cost of ownership and clinical outcomes are demonstrably superior.
- Transition planning: For hospitals migrating to cloud-hosted HIS/EPD platforms, architect PDMS projects with robust failover, segmented networks and clear SLAs for incident response — a “lift-and-modernize” strategy without hardened resilience can increase downstream risk.
- Value capture and ROI measurement: Design pilots and phased rollouts to capture both labor-savings and clinical-safety KPI improvements. The most defensible business cases combine efficiency metrics with reduced adverse events and documentation quality gains.
- Partner and M&A playbooks: For vendors and private investors, consolidation opportunities exist in niche clinical PDMS modules and device connectivity middleware. Strategic acquisitions that expand hospital footprint or close critical integration gaps will accentuate competitive advantage.
What the full PW Consulting PDMS study delivers
The full report moves beyond directional commentary to provide the operational intelligence required to act in 2026. Key deliverables include:
- Comprehensive market sizing and forecast model (historical and projected figures, 2020–2032) with scenario simulations reflecting different adoption, funding and regulatory pathways.
- Segmentation analysis by region, solution type and clinical application — with interactive tables and downloadable datasets to inform budgeting and go-to-market planning (note: detailed segmentation tables are included in the full report).
- Vendor scorecards that assess product capability across device connectivity, medication management, regulatory readiness and cybersecurity controls, accompanied by vendor risk matrices and roadmap visibility.
- Implementation playbooks and procurement templates that translate clinical requirements into RFP criteria, validation checklists and contractual cybersecurity clauses.
- Case studies and lessons learned from recent deployments and incidents — practical recommendations for mitigation, workforce training and phased adoption.
How to use this intelligence in 2026
- Health system CIOs and CMIOs can use the forecasts and vendor evaluations to prioritize hospital wards and clinical programs for PDMS rollouts and to justify capital requests with market-backed ROI timelines.
- Vendors can map whitespace and partnership opportunities — assessing whether to pursue cloud-native integrations, niche clinical modules, or device-agnostic middleware strategies.
- Investors and private equity can use the consolidation maps and vendor scorecards to identify targets that offer rapid scaling of device connectivity, compliant feature sets, or strong footholds in funded national programs.
Next steps
This briefing is intentionally directional. If you are facing a PDMS procurement decision, vendor negotiation or strategic investment in 2026, the full PW Consulting report provides the granular segmentation, financial modelling and executable playbooks you will need. Visit our report page to access the complete dataset, interactive forecasting model and vendor scorecards that underpin these strategic recommendations.
For detailed analysis of this topic, please visit the official page: Patient Data Management Systems (PDMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
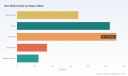
Beer Market 2026: Strategic Imperatives for Growth, Resilience and Value Creation
As PW Consulting’s Chief Industry Analyst, I present an executive orientation to our latest Beer Market study — a deliberately high-resolution, decision-focused analysis calibrated for leadership teams planning 2026 strategies. This preview synthesizes the macro trajectory, competitive dynamics, structural cost pressures and the operational playbooks that will determine who captures value in the coming cycle. It also follows the “trailer” principle: we show the analytic depth and strategic direction here while preserving the report’s full segment-level data and proprietary modeling behind our source page to preserve commercial utility and encourage direct engagement.
Beer Market
A concise market snapshot
Using 2025 as the base year, the global beer market has expanded materially since 2020. Our topline time series shows the market rising from the mid-700s (USD Billion) in 2020 to USD 860.0 Billion in 2025, reflecting a recovery and reset after pandemic-related disruption. Looking ahead, our forecast model — underpinned by demographic, pricing, and channel dynamics — projects a compound annual growth rate (CAGR) of 4.91% across the 2026–2032 period, taking the market to roughly USD 1,170 Billion by 2032.
Beer Market
That trajectory is not linear: the historical series contains both resilience and volatility, signaling pockets of structural growth (premiumization, non-alcoholic innovation, off-premise omnichannel) alongside episodic headwinds (raw-material cost swings, regulatory shifts, and logistics disruptions). For 2026 planning, executives need to treat the aggregate expansion as an opportunity window — but one that rewards granular positioning, cost architecture, and nimble go-to-market execution.
Beer Market
Why this research matters for 2026 decisions
-
Strategic resource allocation — Our modeling translates the macro growth envelope into probabilistic revenue and margin outcomes under alternative scenarios (e.g., sustained premiumization, accelerated non-alcoholic adoption, or material input-cost inflation). These are designed to inform investment sizing, capacity timing, and channel prioritization for 2026 capital plans.
-
Competitive differentiation — With aggregate concentration metrics indicating a market where the top three and top five players retain meaningful shares, the levers to expand share are increasingly strategic: targeted innovation, regional portfolio optimization and differentiated channel strategies. Our report converts these levers into executable initiatives and KPIs.
-
Risk-aware growth — Input-cost volatility (malt, barley, aluminum) and trade policy shifts can quickly erode margins. We provide scenario stress-tests that quantify EBITDA sensitivity to common shocks and rank mitigation options by effectiveness and time-to-impact.
Core strategic themes for 2026
-
Segmentation-driven premiumization: Consumer willingness to pay continues to migrate toward premium and experiential formats — not uniformly, but in clusters that reward precise local execution. The commercial implication is simple: targeted premium roll-outs, higher mix economics and differentiated pricing governance will be required to convert interest into durable margin expansion.
-
Non-alcoholic and portfolio stretching: Leading brewers are investing in non-alcoholic and alternative malt beverages as both margin and channel-entry plays. Rapid SKU rationalization, accelerated R&D-to-shelf timelines, and marketing investments in mainstream channels will determine winners.
-
Packaging and input-cost strategy: Aluminum and malt cost dynamics are now a core strategic domain. Our research shows packaging conversion choices, supplier contracts, and recycling/closed-loop pilots materially affect cost per liter. Expect integrated packaging strategies — combining material innovation, procurement hedging and circularity — to be a competitive battleground.
-
Omnichannel distribution optimization: The on-trade vs off-trade balance has been recalibrated post-2020. Leading firms are redesigning route-to-consumer strategies with sharper trade promotion economics, subscription and DTC pilots, and data-enabled assortment management.
-
M&A and capability-led consolidation: With medium concentration at the top, M&A is less about scale alone and more about capability capture — craft portfolios, contract-brewing capacity, premium supply chains, and technology-enabled direct channels.
Competitive landscape — what the majors are doing
Our study includes a focused benchmarking of the sector’s largest players and their strategic postures. Highlights:
-
Anheuser-Busch InBev (HQ: Leuven) — Continuing to lean into capacity expansion and local manufacturing investments while prioritizing growth SKUs in the premium and health-forward segments. Leadership is balancing scale with local responsiveness.
-
Heineken N.V. (HQ: Amsterdam) — Reported gains in non-alcoholic and premium segments, underscoring a portfolio play that blends broad distribution with differentiated offerings and brand marketing focused on premiumization.
-
Carlsberg Group (HQ: Copenhagen) — Emphasizing portfolio diversification and market share gains across targeted markets, while calling out packaging and raw-material cost pressures as focal operational priorities.
-
Molson Coors (HQ: Golden, CO) — Managing North American core brands alongside craft and innovation efforts; portfolio complexity and trade dynamics are central to its near-term margin management.
-
Constellation Brands and Boston Beer Company (US firms) — Both illustrate the interplay of import dynamics, tariffs and margin exposure. One firm benefitted from recent tariff removals; another has explicitly flagged tariff pressure as a near-term margin headwind.
These firm-level movements are not isolated: they collectively signal a strategic shift from simple volume growth to margin and capability-driven competition. Our report translates these observations into competitor scorecards and prioritized response options for new entrants and incumbents alike.
Operational levers and near-term playbook
For 2026 plans, we recommend decision-makers focus on a tight set of operational levers that the report models quantitatively:
-
Procurement and forward-buying protocols for key inputs (malt, barley, aluminum), combined with supplier diversification and local sourcing where feasible.
-
Packaging optimization: evaluate can-to-bottle economics through a full TCO lens, incorporate conversion and recycling initiatives, and integrate packaging strategies into SKU and channel economics.
-
SKU portfolio pruning and prioritized NPD: concentrate brand and promo support behind high-ROI SKUs while accelerating rollouts of non-alcoholic and premium SKUs in high-opportunity channels.
-
Channel economics redesign: deploy trade-promo ROI tools, roll out high-frequency DTC pilots in strategic markets, and redesign trade terms to align incentives across the on-trade and off-trade continuum.
-
M&A and partnerships: a playbook for sourcing capability-first targets — contract brewers, premium craft portfolios, or logistics and packaging innovators — along with integration templates and synergy capture metrics.
Risks, policy and near-term shocks to monitor
-
Trade policy surprises: Tariff reintroductions or removals can swing import economics and supply-chain routing. Our scenario work models sensitivity of gross margin to plausible tariff outcomes and offers hedging and sourcing mitigations.
-
Raw-material inflation: Malt and barley remain primary cost drivers; firms with better hedging, supplier partnerships and agronomy programs will enjoy durable margin advantages.
-
Packaging supply constraints: Aluminum availability and conversion economics can amplify costs. Firms investing in recycled content, alternative pack formats and local conversion capacity reduce exposure.
-
Consumer preference shifts: Rapid shifts toward non-alcoholic or flavor-driven formats demand accelerated NPD pipelines and agile manufacturing.
What the full report contains — operationally actionable deliverables
PW Consulting’s full Beer Market study is structured for immediate use by strategy, commercial, supply-chain and investor teams. The deliverables include:
-
Comprehensive historical and forecast topline time series spanning 2020–2032 with scenario variants and sensitivity bands keyed to pricing, volume, and mix assumptions.
-
Proprietary segmentation and channel matrices with interactive dashboards (company- and market-level views) enabling drill-down to SKU, pack-format and distribution economics. Please note: detailed segment splits and proprietary unit economics are available inside the full report.
-
Competitor benchmarking with capability maps, near-term strategic moves, and an M&A target universe scored by strategic fit, integration risk and value uplift.
-
Operational playbooks: pricing and promo optimization templates, procurement and packaging strategies, manufacturing capacity plans, and a validated set of KPIs to track 2026 execution.
-
Stress-test models that quantify EBITDA sensitivity to shocks (tariffs, input-cost spikes, and demand shifts) and rank mitigation levers by speed-to-impact and cost-to-implement.
How to use this intelligence in your 2026 planning cycle
Translate the report’s outputs into three concrete actions before Q2 2026 planning freezes:
-
Run the report’s scenario sets against your current FY26 budget to test resilience of EBITDA targets and adjust capital timing where necessary.
-
Use the competitor scorecards and M&A scoring to identify 1–3 capability-led bolt-ons or partnership plays you can diligence in 2026.
-
Implement a rapid packaging and input-cost task force to capture short-term procurement and conversion wins while developing medium-term circularity projects.
Conclusion — where to go next
The beer market is growing on aggregate, but the next wave of value will be captured by firms that align portfolio, procurement and routes-to-market with the nuanced pockets of demand and cost opportunity we identify in this study. The strategic choices you make for 2026 — about where to invest, where to prune, and which capabilities to acquire — will determine whether you gain share in the higher-margin parts of the market or merely chase volume in a structurally evolving arena.
For the full dataset, interactive dashboards, segmentation matrices and the proprietary playbooks referenced above, please consult the report host page. The core intelligence and the granular numbers that plug directly into planning models are available there — including our market concentration analysis and the full competitor benchmarking dossiers that inform the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Beer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tonneau Covers Market to Hit USD 460.85M by 2032 at 5.8% CAGR - PW Consulting
By pmarketresearch, 2026-07-09
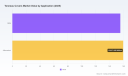
Tonneau Covers Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused preview of our full Tonneau Covers Market study. This briefing synthesizes the report’s most consequential macro-trends, competitive dynamics, and regulatory shocks that will shape corporate strategy in 2026 — while intentionally withholding granular segment tables and proprietary scorecards that live inside the full report. Consider this a short, evidence-led trailer: enough depth to inform near-term choices, and a clear invitation to access the complete analysis for executable planning and deal support.
Tonneau Covers Market
Market trajectory: steady growth with strategic inflection points
The tonneau covers market has demonstrated resilient expansion through the early-2020s and enters 2026 from a position of scale. Our modeled history shows the market growing from roughly USD 243 million in 2020 to about USD 315 million in 2025. Under a base-case outlook, the market extends to the mid-hundreds by the end of our forecast window, advancing at a compound annual growth rate of 5.8% across 2026–2032.
Tonneau Covers Market
- Implication: A 5.8% CAGR is sufficient to support continued innovation investment, channel expansion, and selective consolidation — but it does not justify undisciplined capital deployment. Companies must pursue targeted moves that improve margin capture and distribution efficiency rather than chasing top-line growth alone.
Demand drivers and structural tailwinds
Three principal drivers undergird the market’s expansion:
Tonneau Covers Market
- Fleet and contractor usage trends that favor lightweight, durable bed covers enabling secure cargo transport and modular access for tools and equipment.
- OEM integration trends where passenger-truck buyers increasingly expect factory-fit accessories and options that blend aesthetics with functionality.
- Aftermarket appetite for personalization and value-preserving accessories, where consumers trade modest upfront spend for utility and resale protection.
Each driver has different margin and go-to-market implications. OEM channels reinforce scale and credibility but demand tight compliance and pricing discipline; aftermarket channels offer higher SKU diversity and marketing levers but require deeper distribution and warranty management capabilities.
Competitive landscape — consolidation without domination
The competitive topology reveals a market that is concentrated by capability clusters rather than by a handful of dominant single-brand players. Our concentration metrics show that the top three firms account for well under a majority of market value, and the top five remain below 40% market share — a structure that keeps both competitive intensity and M&A optionality high.
- Implication: The market is ripe for strategic roll-ups and capability-driven consolidation, but any acquirer must prioritize integration of channel networks, IP, and manufacturing footprints to realize value.
Key corporate players are active along both aftermarket and OEM axes. Notable observations from our competitive benchmarking:
- Truck Hero operates a multi-brand portfolio that spans roll-up, folding, retractable, and one-piece designs. This multi-brand strategy improves shelf presence and OEM access but creates integration and SKU rationalization challenges.
- RealTruck (and the BAK line) occupies a strong position in high-performance hard/folding covers and is influential in trade action advocacy.
- Specialist manufacturers — including producers of retractable mechanisms, high-end contractor-grade hard covers, and low-profile roll-up solutions — sustain product innovation cycles that reset buyer expectations for durability, access, and security.
- A surprising structural feature: an industry cluster centered on a common geographic ecosystem that concentrates manufacturing, suppliers, and design capability, creating advantages in talent, supplier negotiation, and rapid prototyping.
These dynamics create three strategic archetypes for market participants: (1) scale-oriented consolidators leveraging multi-brand portfolios; (2) niche innovators selling premium differentiation to contractor and OEM segments; and (3) channel specialists focused on distribution-led aftermarket growth.
Regulatory and trade dynamics: a material near-term shock
In early 2026 the industry saw a decisive regulatory development: a coordinated set of antidumping and countervailing duty petitions filed by domestic manufacturers and brand owners triggered a formal less-than-fair-value investigation into imports of truck bed covers from the People’s Republic of China. The Federal Register initiated an investigation in March 2026.
- Immediate impacts we track: pricing volatility on import-intense SKUs, supplier requalification needs, and short-run availability risks for certain roll and retractable mechanisms.
- Strategic consequence: Tariff actions, if sustained, will favor domestically integrated manufacturing and near-shore sourcing. They also create a temporary arbitrage for companies that can lock in supply or transition to alternative suppliers quickly.
Concurrent with trade action, we are observing product launches from premium innovators: Worksport’s new models — introduced at industry shows in early 2026 and supported by meaningful pre-order interest — demonstrate that product-led differentiation continues to work even amid policy uncertainty. That combination of trade friction and innovation creates both risk and opportunity.
What the full report delivers (practical sections you’ll use immediately)
Our report is built to inform boardrooms, corporate development teams, and commercial leadership in 2026. Key operational modules include:
- Robust market sizing and a transparent forecast model (2026–2032) with sensitivity scenarios tied to tariff outcomes, fuel/pricing shocks, and OEM option penetration rates.
- Go-to-market playbooks for OEM vs aftermarket prioritization, including channel economics, dealer margin profiles, and warranty cost modeling.
- Supply chain stress-testing and mitigation options: dual-sourcing templates, near-shoring cost models, and raw-material pass-through clauses.
- Competitive benchmarking and positioning maps that compare product portfolios, patent intensity, manufacturing depth, and brand equity — with actionable gaps and M&A targets.
- Commercial tactics: pricing elasticity analysis, bundle strategies (cover + bed-liner + toolboxes), and digital direct-to-consumer approaches that lift attachment rates.
- Regulatory scenario playbooks tied to the unfolding AD/CVD case, including import mitigation timelines, temporary inventory hedging, and lobbying/stakeholder engagement templates.
- Capex and operational dashboards for manufacturers: tooling amortization schedules, contract manufacturing vs. owned-facility live models, and break-even analyses under tariff regimes.
Actionable strategic imperatives for 2026
Executives should act now across five parallel tracks to preserve optionality and capture upside:
- Supply resiliency: Implement rapid supplier audits, prioritize dual-sourcing for critical components, and model cost-to-serve under tariff scenarios. Short-term inventory increases are defensible when targeted at high-risk SKUs.
- Portfolio clarity: Distinguish between “must-offer” SKUs for OEM contracts and “margin-rich” aftermarket innovations. Rationalize slow-moving SKUs and reallocate capital toward modular, higher-attachment products.
- Channel optimization: Accelerate D2C pilot programs to capture aftermarket margin, while deepening key OEM relationships via co-development and variance reduction programs.
- M&A and alliances: Target tuck-ins that supply complementary technology (e.g., retractable drives, sealed latches) or distribution reach; avoid scale plays without backend integration plans.
- Regulatory response: Maintain active engagement with trade counsel and industry coalitions. Prepare a three-tier plan (immediate, transitional, permanent) to adjust sourcing and pricing if duties are imposed.
How PW Consulting supports 2026 decisions
We bring a blended capability that couples market analytics with transaction and operational execution. Practical services tied to this study include:
- Full financial model delivery and customization (scenario toggles for tariffs, volume, and mix), enabling rapid board-level decision testing.
- Target screening and value-creation plans for M&A, including integration playbooks that neutralize channel overlap and unify manufacturing footprints.
- Operational workshops to redesign supplier contracts, implement cost pass-through mechanisms, and trim SKU complexity without losing market coverage.
- Regulatory response planning and stakeholder engagement strategies aligned to the current antidumping and countervailing duty processes.
Closing — why this matters for 2026
The tonneau covers market in 2026 is not a binary story of booming or busting; it is a nuanced landscape where measured growth, product differentiation, and policy-driven supply shifts intersect. The market’s steady CAGR and established scale create a runway for focused investment. But the trade actions and concentrated supplier topology mean that the next 12–18 months will disproportionately reward companies that combine agile sourcing, disciplined portfolio management, and the ability to execute on channel economics.
This preview is designed to orient decision-makers to those pressure points. The full PW Consulting report contains the underlying datasets, proprietary scorecards, and executable templates required to move from insight to implementation. Access to those deliverables will materially shorten your path from strategic intent to market capture.
Next step
For teams preparing 2026 budgets, M&A targets, or operational contingency plans, we recommend commissioning the full report and a brief focused workshop with our advisory team. We will tailor forecast scenarios to your product mix and supply exposure and produce a prioritized 90-day action plan you can deploy immediately.
For detailed analysis of this topic, please visit the official page: Tonneau Covers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Microwave Oven Market to Reach USD 13.5 Billion in 2025; 3.5% CAGR (2026–2032) — PW Consulting
By pmarketresearch, 2026-07-09
Microwave Oven Market 2026: Strategic Imperatives and What the PW Consulting Report Delivers
Between 2020 and 2025 the global microwave oven market recorded material expansion — rising from roughly USD 8.5 billion to USD 13.5 billion — driven by faster replacement cycles in mature markets, portfolio refreshes in major brands, and feature-led upgrades (convection, air-fry and connectivity). Our base-year analysis (2025) and forward-looking work indicate a continued, moderate-rate expansion under a scenario-weighted compound annual growth rate of 3.5% through 2032, with the market trending toward the mid‑teens of billions of USD by the end of the forecast window. For executives making strategic choices in 2026, that profile implies steady demand growth but mounting differentiation and margin pressure — a combination that rewards disciplined product, channel and sourcing strategies.
Microwave Oven Market
Why our research matters for 2026 decision cycles
-
Regulatory uncertainty is now a first-order operational risk. In 2025 the U.S. Department of Energy proposed rescinding prior energy conservation standards for microwave ovens — a policy move that materially alters product compliance, development roadmap timing, and potential labeling claims for manufacturers selling into North America. Meanwhile, existing FDA radiation-safety obligations remain binding and require continued certification and labeling diligence. Our study quantifies the commercial implications of both types of regulatory pressure and provides a prioritized compliance playbook for product teams.
Microwave Oven Market -
Supply-chain cost volatility and trade policy shifts are constraining margin expansion. Analysis of tariff impacts through early 2026 shows that prior trade measures have increased core component price indices and elevated landed costs for many import-reliant designs. The market-scale data in our report lets CFOs and procurement leaders stress-test sourcing scenarios and build hedges into 2026 budgets.
Microwave Oven Market -
Competitive intensity is concentrated but not lock-tight. The market exhibits moderate concentration with the top three firms controlling a meaningful share of global revenue and the top five expanding that dominance further. That structure creates clear windows for nimble brands and private-label OEMs to capture share by moving faster on product innovations, channel partnerships, and aftermarket services.
What PW Consulting’s Microwave Oven Market Report contains — practical, executable intelligence
-
Granular market-sizing and forecast engine (2020–2025 historical, 2026–2032 forecast) with scenario toggles for policy, component-cost, and consumer-preference shocks. We provide base-case, upside and downside runs that feed directly into financial planning models.
-
A transparent methodology appendix describing data sources, primary-research protocols (supplier interviews, retailer sell‑through audits, and installer panels), and statistical techniques used to reconcile divergent datasets.
-
Unit-economics and margin models by platform archetype (compact countertop, grill, convection, built‑in and drawer formats) that let product and commercial teams simulate pricing, component-cost swings, and warranty/service outcomes. (Note: detailed line-by-line segment tables are reserved for the full report.)
-
Supply‑chain and cost mapping: component origin matrices, common bill-of-materials breakdowns, and landed-cost sensitivity analyses keyed to 2026 tariff scenarios.
-
Channel and go‑to‑market playbooks bespoke to retailers, distributors, and OEM partners, including recommended merchandising mixes, digital bundling strategies, and subscription / extended‑warranty frameworks.
-
A playbook for regulatory engagement and product-compliance sequencing that reconciles U.S. energy-policy shifts with ongoing safety obligations and likely regional responses.
-
M&A and partnership scorecards highlighting logical bolt-ons (controls/software, service networks, component suppliers) plus valuation heuristics for 2026‑era transactions.
Competitive landscape — what the leading firms are doing and why it matters
-
Midea Group — A global OEM heavyweight that operates both as supplier-to-many and brand owner. Midea’s scale in manufacturing and breadth of countertop platforms give it cost advantages and a fast time-to-market capability; catalog updates in early 2026 illustrate a continued focus on breadth and price-point capture. For competitors, Midea represents both a procurement partner and a competitive threat on price and private‑label execution.
-
Galanz — A specialist OEM with deep ties to mass-channel retailers and private-label programs. Galanz’s dual role as brand and supplier amplifies its ability to flex volume; strategic buyers and retailers should evaluate the trade-offs between control and cost when engaging Galanz for exclusive or semi‑exclusive ranges.
-
LG Electronics — Leverages differentiated technology (connected controls, integration with home ecosystems) and premium positioning in built-in and multi-function units. LG’s path illustrates how software, connectivity and cross-category bundling can lift ASPs and create recurring-service opportunities.
-
Sharp Corporation — Signals from a 2026 product launch (notably a compact Convection Microwave Drawer™ Oven) demonstrate strategic focus on small-space living and design-led differentiation. For product teams, Sharp is an object lesson in how form-factor innovation can open new retail categories and justify premium pricing.
-
Whirlpool Corporation and GE Appliances — These incumbents balance large dealer networks and brand trust with sporadic domestic manufacturing footprints. Their multi-brand strategies (including premium and entry sub‑brands) are instructive for firms contemplating channel segmentation and localized supply.
Recent developments with direct implications for 2026 planning
-
February 2026 — Sharp launched new compact convection drawer units targeting urban and small‑kitchen consumers. This product move validates the “compact premium” sub‑segment opportunity and signals acceleration in non-traditional form-factor demand.
-
March 2026 — Midea updated its consumer-facing catalog with refreshed countertop offerings and Versa Series SKUs, underscoring a cadence of SKU refreshment that pressures competitors’ product‑life cycles.
-
May 2025 — The U.S. Department of Energy proposed rescission of prior microwave energy-efficiency standards. This policy dynamic creates a bifurcated risk: lower near-term compliance costs on one hand, but increased reputational and market-access risks on the other as sustainability-conscious channels and jurisdictions may impose higher voluntary requirements.
-
Trade-policy context — Tariff measures implemented in prior years contributed to material increases in component price indices through early 2026. Procurement and product teams should assume persistent cost tails and build sourcing flexibility into 2026 capex and procurement plans.
Concrete strategic moves for 2026 — where to focus
-
Prioritize modular platform architectures that allow rapid SKU configuration without full redesign. This reduces time-to-market and enables dynamic response to regional regulatory changes.
-
Implement dual-sourcing or nearshoring pilots for critical components to blunt tariff and logistics shocks; run a 12–18 month cost/revenue trade‑off analysis to inform investment decisions.
-
Double-down on software and services: connectivity, diagnostics, and aftermarket parts are higher-margin levers that dilute commoditization in base units.
-
Reassess channel economics: retailers and distributors face different inventory and warranty dynamics in 2026; align go‑to‑market models to the retailer’s appetite for assortment breadth versus depth.
-
Use the regulatory window to reposition products for sustainability-literate consumers — for instance, certify optional energy‑saving modes even if standards have been rescinded, maintaining access to green channels and segments.
-
Move early on M&A targets that close technology or service gaps (control modules, sensors, service networks), and avoid bidding up commodity manufacturing assets where scale parity already exists.
How PW Consulting’s deliverables accelerate your 2026 planning
-
Ready-to-use XLS models and scenario dashboards that plug into corporate FP&A processes — enabling finance teams to run “what-if” analyses quickly against tariff, component-cost, and regulatory levers.
-
Competitor heatmaps and vendor scorecards that distill supplier strengths, capacity constraints, and partner-fit assessments for procurement and corporate development teams.
-
A prioritized set of 12 tactical initiatives (with estimated timelines and cost buckets) that product, manufacturing and commercial leaders can adopt to shape 2026 roadmaps and R&D budgets.
The summary above highlights how PW Consulting blends market-scale data, primary research, and executable strategy work to support board-level and operational decision-making in 2026. For practitioners who need the full segmentation tables, company-level revenue splits, region-by-channel forecasts, and our detailed cost‑build models (the datasets we deliberately withhold here to preserve the value of the full study), the complete Microwave Oven Market report and the accompanying data package provide that depth — including downloadable models and vendor dossiers that slingshot planning cycles into execution.
If your team is evaluating product roadmaps, sourcing reconfigurations, or M&A targets in the coming 12 months, the intelligence in this report is designed to reduce execution risk and identify the value levers that matter most. Contact PW Consulting to access the full report and the interactive modeling suite.
For detailed analysis of this topic, please visit the official page: Microwave Oven Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cloud Gaming Market Poised for 28.25% CAGR Through 2032
By pmarketresearch, 2026-07-09
Cloud Gaming Market 2026: Strategic Outlook and Decision Playbook
Executive primer
Cloud gaming has moved beyond technology demos and headline trials to become a material, investable segment of digital entertainment. Our new PW Consulting market study — anchored on a 2025 base year and a 2026–2032 forecast window — shows a sustained, high-growth trajectory (CAGR: 28.25%) as the industry scales from an early adopter base into broader consumer and enterprise adoption. From a strategic standpoint, 2026 represents a pivotal inflection: connectivity and compute capabilities have matured enough to enable commercial rollouts at scale, while regulatory and energy headwinds are beginning to shape competitive moats and capital allocation decisions.
Cloud Gaming Market
Why this study matters for 2026 decision-makers
- Timing and conviction: With the market expanding rapidly (our analysis places the global market at USD 8.72 Million in 2025, rising toward USD 49.47 Million by 2032), executives who treat 2026 as the moment to operationalize cloud gaming strategies — rather than merely pilot them — position their organizations to capture disproportionate share.
- Competition and concentration: The market exhibits clear concentration at the top: the three largest providers account for a majority share (CR3 ~57.3%), and the top five control roughly three-quarters (CR5 ~74.2%). That dynamic influences partnership choices, pricing tactics, and the viability of niche plays.
- Regulatory and infrastructure risk: Recent regulatory shifts and infrastructure investments are creating asymmetric opportunities across markets. Firms that embed regulatory scenarios and energy-cost sensitivity into their 2026 playbooks will avoid costly mid-course corrections.
Market dynamics that will decide 2026 outcomes
- Edge and 5G are necessary but not sufficient: Carrier-grade 5G Standalone deployments and edge nodes materially reduce latency and broaden addressable audiences; recent national telco packages indicate operators see gaming as a beachhead. Yet, delivering consistent quality also requires cloud platform maturity and developer tooling — a multi-constituent problem that favors alliances between hyperscalers, telcos, and studios.
- Cloud compute, energy, and unit economics: Data center energy demand is rising sharply, and projected increases in power consumption introduce a new layer of operational risk. Cost-of-play economics in 2026 will increasingly hinge on energy sourcing, workload placement (central cloud vs edge), and hardware utilization. Firms must evaluate TCO across these dimensions rather than treating streaming as a pure software expense.
- Regulatory divergence: The regulatory landscape is bifurcating. Some jurisdictions are moving away from net neutrality constraints, while others are doubling down on digital sovereignty and federated telco-cloud initiatives. These opposing forces will create market-specific go-to-market requirements for content delivery, data residency, and interconnection strategies.
- Product and experience differentiation: As baseline streaming quality homogenizes, content licensing, ecosystem integrations, discovery, and latency-tailored UX will separate winners from the rest. Firms that invest in product primitives (adaptive codecs, AI-driven bandwidth optimization, and seamless cross-device state transfer) will win higher ARPU segments.
Competitive landscape: capabilities that matter in 2026
Our vendor analysis synthesizes product roadmaps, go-to-market signals, and recent tactical moves to generate a capability map for 2026 buyers. The leading firms in the space illustrate the strategic archetypes now competing for control of the value chain:
Cloud Gaming Market
- Hyperscaler-integrated platforms (example archetype): Major cloud providers are leveraging global infrastructure and content bundling to offer low-latency, subscription-driven services that scale across devices. Their advantage lies in edge density, platform integrations, and the ability to subsidize customer acquisition via broader bundles.
- Graphics and platform specialists (example archetype): Vendors focused on GPU virtualization and AI-assisted streaming differentiate on fidelity and performance. Their technical lead enables premium experiences (high frame-rate, high-resolution) that appeal to core gamers and premium tier subscribers.
- Integrated device and entertainment firms (example archetype): Console and hardware incumbents convert installed base and exclusive content into cloud propositions designed to retain high-value users without requiring new hardware purchases.
- Regional and niche aggregators (example archetype): Smaller providers and regional champions deliver localized catalogs, device-specific integrations, and white-label solutions that address market-specific content, billing, and latency constraints.
Recent market moves and what they signal
- Platform scaling and optimizations: Leading cloud platforms have doubled down on optimizations and edge expansion to capture broader device footprints. These efforts reduce entry friction for casual users and enable live migrations of game state across devices.
- Hardware and ecosystem integrations: Pre-installation agreements and native integrations on gaming handhelds and smart devices accelerate user acquisition and reduce friction in the funnel from discovery to play.
- AI and quality optimization: The infusion of AI into streaming stacks — from perceptual encoding to dynamic resource allocation — is creating new levers for quality improvement that materially affect perceived value at the point of consumption.
- Telco and edge commercial models: Operators are packaging low-latency gaming services into consumer and enterprise offerings, hinting at subsidized connectivity and B2B2C monetization models that can quickly scale user bases when paired with compelling content catalogs.
What the full PW Consulting report delivers (practical, decision-ready content)
This study is designed as an operational toolkit for corporate leaders, investors, and product teams preparing 2026 strategies. Key deliverables include:
Cloud Gaming Market
- Market sizing and high-resolution forecast model (2026–2032) calibrated to demand elasticity, device penetration, and monetization archetypes.
- Vendor capability matrix and strategic decision trees for choosing partners across cloud providers, telcos, and content studios.
- Go-to-market playbooks for four archetypal entrants (hyperscaler-led, graphics-specialist, console-integrator, regional aggregator) with sample KPIs, pricing experiments, and marketing levers.
- Regulatory scenario planning and mitigation blueprints that translate policy shifts into commercial actions (data residency plans, interconnection strategies, and contingency routing).
- Edge placement and TCO models that quantify trade-offs between centralized cloud and telco-edge deployments under varying energy and bandwidth cost assumptions.
- Studio and content acquisition frameworks that show how to prioritize catalog investment vs. platform feature investment to accelerate monetization.
Strategic imperatives and recommended first moves for 2026
- Reassess content vs. infrastructure trade-offs: Decide whether to compete on content exclusivity, platform experience, or a hybrid approach. Our scenarios demonstrate that customer retention benefits from differentiated content, but unit economics improve with infrastructure partnerships.
- Lock modular partnerships, not monolithic dependencies: Given top-player concentration, firms should design multi-vector partnerships (edge access, interconnect, content licensing) that preserve optionality and reduce single-partner exposure.
- Embed regulatory scenarios into financial planning: Build flexible deployment templates that can be reconfigured by region to meet sovereignty or net-neutrality-related constraints while controlling costs.
- Prioritize energy-aware operations: Incorporate renewable sourcing, workload scheduling, and regional load balancing into capacity plans to mitigate the rising energy footprint risk and secure long-term economics.
- Invest in perceptual quality improvements: Small gains in perceived latency and resolution (achieved through codecs, AI, and adaptive bitrate) yield outsized conversion and retention improvements in consumer cohorts.
Closing perspective
Cloud gaming is entering a commercialization phase where execution clarity and architectural discipline will determine winners. The market is expanding rapidly — growing from an early base in 2020 to a materially larger market by 2025, and projected to continue expanding through 2032 — but the winners in 2026 will be the organizations that combine pragmatic infrastructure decisions, content strategy, and regulatory foresight.
PW Consulting’s full report provides the granular models, vendor scorecards, and step-by-step playbooks required to convert the macro opportunity into executable plans. The analysis is intentionally detailed in source deliverables while this introduction is curated to highlight strategic implications — contact us or visit the report page to unlock the complete datasets, segmentation matrices, and implementation templates necessary for confident decision-making in 2026.
For detailed analysis of this topic, please visit the official page: Cloud Gaming Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Optical Films Market to Grow at 7.1% CAGR Through 2032
By pmarketresearch, 2026-07-09
Optical Films Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, forward-looking briefing on the optical films market that translates technical market intelligence into boardroom-ready actions for 2026. This preview highlights the structural drivers, competitive dynamics, and near-term strategic levers that will determine winners and laggards across display OEMs, advanced materials suppliers, and tiered component manufacturers. It intentionally demonstrates analytical depth while withholding granular segmentation tables and proprietary model outputs — the latter are available in the full report for subscribers.
Optical Films Market
Market trajectory and strategic context
The optical films market has shown resilient expansion through the post-pandemic recovery period and is on a steady growth path into the next decade. Using 2025 as our base year, the market is valued in the mid-hundreds of millions (USD, revenue basis) and is forecast to grow at a compound annual growth rate (CAGR) of 7.1% over the 2026–2032 forecast window. This trajectory reflects a convergence of display innovation (flexible OLEDs, mini-LED and micro-LED backlights, AR/ HUD integration), increased per-unit complexity in consumer devices, and rising content and safety requirements in automotive and industrial displays.
Optical Films Market
Historical performance through 2020–2025 demonstrates both the resilience and volatility of this sector. Supply-side shocks and raw-material swings depressed margins intermittently, while product innovation and recycling mandates have opened higher-margin, differentiated opportunities. For 2026, executives must read this as a market in which steady top-line expansion coexists with heightened operational and regulatory risks — a classic environment where strategy execution and supply-chain choices trump static market-share plays.
Optical Films Market
What is changing now — five dynamics to watch
-
Technology-driven demand composition: Display manufacturers are increasing requirements for thinner, higher-transmittance, and multi-functional films (e.g., polarizers integrated with brightness enhancement or anti-reflection properties). Novel form factors (foldables, rollables) are accelerating adoption of ultra-thin and flexible optical films.
-
Sustainability and regulatory pressure: Recyclable and low-environmental-impact chemistries are rapidly moving from “nice-to-have” to procurement prerequisites for major OEMs. Suppliers that can demonstrate circularity and reduced life-cycle impact will secure preferential sourcing and command premium pricing.
-
Supply-chain localization and capacity shifts: Manufacturers are responding to labor cost volatility, material shortages, and tariff uncertainty by selectively localizing production and reconfiguring inventory strategies. Recent greenfield expansions in Asia and targeted capacity upgrades in Korea and Japan create regional capacity pockets that change lead-time economics.
-
Tariff and trade-policy tail risks: Specialty chemicals used in film production face variable export controls and tariffs. These policies can rapidly reconfigure competitive advantages among global suppliers and alter sourcing decisions for display OEMs.
-
Automotive and AR use-cases scaling: Head-up displays, in-cabin infotainment, and augmented-reality overlays are driving bespoke film requirements (optical clarity, polarization control, durability). Co-development agreements between chemical suppliers and automotive OEMs are emerging as strategic anchors.
Competitive landscape — what the market structure means for 2026 moves
The market is moderately concentrated among several global players, with a handful of firms capturing a material share of advanced optical film demand. That concentration creates both supplier power and opportunity: leading players can invest in specialized R&D, while mid-tier suppliers can carve resilient niches through partnerships and tailored product stacks.
-
3M Company — continues to push ultra-thin polarizers and flexible-film innovation tailored to next-gen OLED form factors. Recent product introductions signal an emphasis on extending portfolio depth for foldable and flexible devices.
-
LG Chem — positions itself on sustainable materials, launching recyclable optical film families that meet increasingly exacting OEM sustainability requirements. This is a defensive and offensive play: defend existing relationships while opening new procurement pathways where ESG is a criterion.
-
Samsung SDI — integrates display-facing film capabilities with panel technologies, leveraging close OEM relationships to co-develop film composites for both LCD and OLED stacks.
-
Zeon, Toray, Nitto, Toyobo — these specialists are focused on high-transmittance substrates, low-haze films, and material science upgrades for touch and polarizer stacks. Their depth in polymer chemistry and substrate processing is a key competitive barrier.
-
Eastman Chemical — recently expanded manufacturing capacity in Asia, which materially alters the cost and lead-time calculus in certain regional supply chains.
Recent industry actions — a new ultra-thin polarizer launch, capacity expansions in Asia, and OEM-supplier partnerships for automotive HUD/AR — underscore a bifurcation: larger suppliers are investing in scale and premium innovation; specialist firms are protecting margin via targeted material differentiation and collaboration with OEMs.
Practical contents — what the full PW Consulting report delivers
The full study offers executive-ready, operational guidance designed for 2026 planning cycles. Highlights include:
-
Robust market-sizing and forecast model (base year 2025; 2026–2032 forecasts) with scenario layers for technology adoption, trade-policy shocks, and raw-material price regimes.
-
Competitive benchmarking with strategic profiles for each major supplier, innovation roadmaps, and capability heatmaps to identify partnership and acquisition targets.
-
Supply-chain resilience playbook: a prioritized set of actions covering capacity localization, dual-sourcing, strategic inventory sizing, and contract structures to mitigate tariff and raw-material volatility.
-
Commercial go-to-market playbooks for suppliers and OEMs: tiered pricing strategies, co-development contracting templates, procurement scorecards, and channel optimization guidance.
-
Capex and ROI toolkits: sensitivity matrices and break-even analyses for greenfield lines, product conversion investments, and recycling-enhancement retrofits.
-
Regulatory and compliance checklist tailored to chemical export controls and environmental mandates, with recommended mitigation steps and timeline impact assessments.
-
Investor and M&A intelligence: target screening criteria, valuation benchmarks, and post-merger integration risks specific to optical-film technology and production footprints.
Strategic recommendations for 2026 corporate planning
For boards and C-level teams, the following strategic priorities should be operationalized in 2026 planning cycles to capture upside and insulate downside risk.
-
Prioritize differentiated product roadmaps: Invest in ultra-thin, multifunctional films and recyclable chemistries. Incremental manufacturing efficiency is necessary but insufficient — differentiation will drive margin expansion.
-
Lock in OEM co-development partnerships: Move from transactional sales to integrated development agreements with major panel and device manufacturers to secure long-term demand visibility and co-fund innovation risk.
-
Reassess manufacturing footprint defensively: Use scenario modeling to determine which assets to localize, expand, or decommission — prioritize proximity to strategic OEMs and access to stable input streams rather than lowest labor cost alone.
-
Hedge raw-material and tariff exposure: Deploy commodity hedging where possible, negotiate long-term supply agreements with pricing collars, and structure sales contracts to share tariff risk with customers in clearly defined triggers.
-
Pursue bolt-on M&A and strategic alliances: Acquire niche material innovators or processing specialists to shorten time-to-market for next-generation films. Target assets that plug directly into existing supply relationships with panel OEMs.
-
Embed sustainability into procurement and product specification: Make recyclability and end-of-life processing part of your product spec for new contracts; this reduces future retrofit costs and strengthens negotiation positions with ESG-focused OEMs.
Decision triggers and KPIs to include in 2026 execution plans
-
Volume and revenue mix against scenario buckets (baseline, upside, downside) for product families tied to flexible OLEDs and automotive AR.
-
Gross margin differential from recycled/eco-friendly product lines versus legacy films; milestone-based R&D expenditure tracking.
-
Weighted lead-time and fill-rate metrics across primary production nodes to trigger capacity shifts or inventory builds.
-
Tariff exposure quantified as a percentage of cost of goods sold, with defined contractual triggers for price pass-through or mitigation actions.
Closing — the strategic value of this research for 2026
For executives planning capital allocation, product strategy, or M&A in 2026, this market represents a growth opportunity tempered by operational and policy risk. The sector’s 7.1% projected CAGR and the mid-hundreds million USD market base (2025) suggest healthy expansion, but realizing attractive returns requires precision in technology roadmaps, supply-chain positioning, and regulatory strategy. PW Consulting’s full Optical Films Market report supplies the models, scenario analyses, and playbooks that translate market forecasts into executable corporate strategy — enabling decision-makers to prioritize investments, secure long-term OEM relationships, and hedge the structural risks that will define 2026 outcomes.
To access the complete dataset, granular regional and application segmentation, and downloadable decision-support models, please consult the full PW Consulting report online. The comprehensive package contains appendices with vendor scorecards, capex calculators, and contract templates not published in this preview.
For detailed analysis of this topic, please visit the official page: Optical Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gas Detectors Market - USD 6,200M in 2025, set for USD 9,630M by 2032 (6.5% CAGR)
By pmarketresearch, 2026-07-09
Gas Detectors Market 2026: Strategic Briefing for Enterprise Decision-Makers
As enterprises plan capital allocation, product roadmaps, and compliance programs for 2026, the global gas detectors market presents both an immediate safety imperative and a sustained commercial growth opportunity. Our market intelligence indicates that total industry revenue expanded from USD 4,400 Million in 2020 to USD 6,200 Million in 2025, and — at a compound annual growth rate (CAGR) of 6.5% — is forecast to approach USD 9,630 Million by 2032. This growth trajectory reflects a combination of regulatory tightening, rising process safety expectations in traditional hydrocarbon sectors, and accelerating demand for new-sensor use cases (notably hydrogen and other low-concentration safety monitoring) across energy transition value chains.
Gas Detectors Market
Why this research matters for 2026 decisions
- Prioritization: The market scale and steady mid-single-digit CAGR make gas detection a defensible area for capital investment in both product development and after-sales services.
- Risk mitigation: New regulatory mandates and safety recommendations are shortening procurement cycles and raising minimum technical specifications for detectors and monitoring systems.
- Strategic windows: The industry structure shows meaningful market concentration among the leading vendors, creating pockets of opportunity for disruptive entrants, partnerships, and carve-out plays.
Market trajectory — what the headline numbers tell you
The industry has moved from a post‑2020 recovery phase into a structurally larger market. Between 2020 and 2025 the market enlarged by roughly 40% in absolute terms, and sustained demand drivers imply continued expansion into the early 2030s. For corporate strategists, this baseline trajectory validates both incremental capacity investments and targeted R&D bets — but it also demands a differentiated approach to customer segmentation, channel strategy, and regulatory readiness to capture disproportionate share.
Gas Detectors Market
Key market dynamics shaping 2026 planning
- Regulatory acceleration: A wave of jurisdictional requirements and standards — from municipal codes for residential gas alarms to pipeline leak-detection mandates and workplace H2S monitoring rules — is elevating the minimum technical and reporting requirements for deployed systems. Operators and OEMs must align product specifications and certification roadmaps to these new baselines.
- Standards-driven procurement: Performance standards and regulatory references are becoming procurement filters. Entities that can demonstrate compliance to recognized standards find it easier to win enterprise-level contracts and long-term service agreements.
- Hydrogen and new gases: Energy transition projects are driving demand for detectors designed for novel atmospheres and lower detection limits, especially hydrogen-focused sensors and explosion-proof enclosures suitable for mixed energy environments.
- Digitization and lifecycle services: Connected detectors, cloud-enabled fleet management and predictive maintenance services are maturing into revenue pools with higher lifetime value than one-off hardware sales.
- Channel and aftermarket economics: Calibration, certification, and localized servicing are rising as strategic levers — firms that integrate hardware, software and service deliver compelling total-cost-of-ownership propositions to large industrial customers.
Regulatory and institutional context — implications for compliance and procurement
Recent and near-term regulatory changes are not abstract; they are operational: municipal building codes now require zoned natural gas detection for certain dwelling classes, pipeline regulators have mandated leak-detection performance thresholds, and major safety agencies are reinforcing standards for workplace monitoring and residential alarms. These shifts compress timelines for deployed upgrades and increase the technical floor for acceptable products. For example, operators subject to pipeline leak-detection rules will prioritize commercially available solutions that meet recognized performance standards when re‑tendering programs.
Gas Detectors Market
Technology and product innovation trends to watch
- Sensing modalities: IR, electrochemical, catalytic, and advanced solid-state sensors each retain distinct use-cases. The choice is increasingly driven by the gas-species mix, required response time, and lifecycle cost considerations.
- Connected and managed solutions: The move from stand-alone detectors to managed fleets — including asset tracking, firmware orchestration, and cloud analytics — is creating recurring revenue opportunities and differentiation.
- Hydrogen-specific designs: New detection chemistries and housings optimized for hydrogen service are appearing in product roadmaps, reflecting event-driven demand from hydrogen production, storage, and fueling projects.
- Integration with process-safety systems: Vendors that bundle gas detection into broader safety and control stacks (including fire, flame, and leak management) are increasing their share of large-scale projects.
Competitive landscape — actionable profile of incumbent and emerging players
The market is commercially mature and moderately concentrated: the top three manufacturers account for a clear majority of market value, with the top five controlling an even larger portion of revenue. Against this backdrop, strategy must balance competitive defense and selective partnership or acquisition.
- Honeywell International Inc. — A broad portfolio across portable and fixed systems, with strong brand recognition in industrial, confined-space and utility applications. Its multi‑brand approach gives it reach across enterprise accounts and service channels.
- MSA Safety Incorporated — Deep in portable multi‑gas detection and established across mining and hazardous-environment use cases; recognized for rugged product lines and field service ecosystems.
- Drägerwerk AG & Co. KGaA — European engineering leader with solid penetration in chemical and process industries; technical depth in oxygen, toxic and combustible gas monitoring.
- Teledyne Gas and Flame Detection — Strengths in open-path and fixed-point systems for oil & gas and marine sectors; often selected for large-scale safety projects.
- Emerson Electric Co. — Provider of infrared-based detection technologies and integrated process-safety solutions, attractive to process automation buyers.
- Industrial Scientific, RKI, Crowcon, Macurco, GDS, Det‑Tronics, Sensidyne, Global Detection Systems, WatchGas — Each occupies focused niches such as personal detectors, semiconductor fabs, fleet-connected devices, hydrogen models, bespoke system builds, high-reliability process detectors, laboratory applications, and emergency‑response gear respectively.
Recent competitive moves reinforce broader trends: connected portable ranges and fleet management (announced in late 2025), hydrogen-focused product introductions and trade-show debuts in mid‑2026, and refreshed product catalogs targeting enterprise procurement cycles. These events are timely signals for procurement teams and R&D planners.
What the PW Consulting report delivers — practical, transaction-ready intelligence
- Top-line market sizing and seven-year forecasts by value, with sensitivity scenarios to stress-test demand under different regulatory and energy-transition pathways.
- Detailed go-to-market playbooks for hardware vendors and service providers, including channel design, pricing levers, and contract structures that maximize recurring revenue.
- Regulatory matrix mapping jurisdictional requirements to product certification needs and procurement triggers.
- Buyer persona and procurement decision maps for oil & gas operators, chemical plants, utilities, mining firms and public safety agencies.
- Technology adoption curves and sensor selection frameworks that translate gas chemistry and use-case into procurement specifications.
- Competitive benchmarking and M&A screening criteria identifying pockets of consolidation and white-space segments suitable for bolt-on acquisitions.
- Supply chain risk heatmap covering critical components, certification lead times, and recommended mitigation levers for 2026 supply planning.
Strategic implications and recommended actions for 2026
- Compliance-first product roadmaps: Ensure new product specifications are aligned with the latest performance standards and jurisdictional rules. Non‑compliance is an adoption blocker in enterprise tenders.
- Prioritize connected solutions: Accelerate development or partnerships for cloud and fleet‑management capabilities; these features increasingly determine renewals and service contract length.
- Service-led growth: Build calibrated aftermarket offerings (field servicing, accredited calibration, subscription models) that convert one-time hardware buyers into multi-year revenue streams.
- Targeted M&A and partnerships: Use the market’s concentration dynamics to pursue bolt-on technologies (e.g., hydrogen sensing, data analytics) or regional service providers that improve market access.
- Procurement playbooks: For end-users, standardize detector specifications to simplify vendor evaluation and leverage competitive sourcing when regulations force accelerated rollouts.
- Risk and resilience planning: Map supplier single points of failure and build dual-sourcing or inventory buffers for critical sensor types ahead of project ramp-ups.
How to use this briefing — next steps
This briefing is a strategic appetizer: it demonstrates the depth of analysis and the kind of executable intelligence we deliver. For teams preparing 2026 capital plans, procurement strategies, or M&A screens, our full report contains the granular segmentation, regional demand models, vendor scorecards, and financial benchmarks required to convert insight into action. Contact PW Consulting to request the complete study and the supporting spreadsheets that drive scenario modelling and vendor shortlists.
In an environment where regulation, technology and the energy transition converge, the decisions you take in 2026 will shape your safety portfolio and market position for years to come. Use this research to align compliance, commercial and technical priorities — and to move from reactive specification to proactive market capture.
For detailed analysis of this topic, please visit the official page: Gas Detectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com