

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Gas Detectors Market - USD 6,200M in 2025, set for USD 9,630M by 2032 (6.5% CAGR)

Gas Detectors Market 2026: Strategic Briefing for Enterprise Decision-Makers
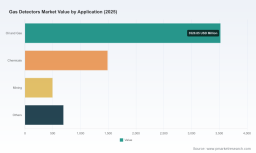
As enterprises plan capital allocation, product roadmaps, and compliance programs for 2026, the global gas detectors market presents both an immediate safety imperative and a sustained commercial growth opportunity. Our market intelligence indicates that total industry revenue expanded from USD 4,400 Million in 2020 to USD 6,200 Million in 2025, and — at a compound annual growth rate (CAGR) of 6.5% — is forecast to approach USD 9,630 Million by 2032. This growth trajectory reflects a combination of regulatory tightening, rising process safety expectations in traditional hydrocarbon sectors, and accelerating demand for new-sensor use cases (notably hydrogen and other low-concentration safety monitoring) across energy transition value chains.
Gas Detectors Market
Why this research matters for 2026 decisions
- Prioritization: The market scale and steady mid-single-digit CAGR make gas detection a defensible area for capital investment in both product development and after-sales services.
- Risk mitigation: New regulatory mandates and safety recommendations are shortening procurement cycles and raising minimum technical specifications for detectors and monitoring systems.
- Strategic windows: The industry structure shows meaningful market concentration among the leading vendors, creating pockets of opportunity for disruptive entrants, partnerships, and carve-out plays.
Market trajectory — what the headline numbers tell you
The industry has moved from a post‑2020 recovery phase into a structurally larger market. Between 2020 and 2025 the market enlarged by roughly 40% in absolute terms, and sustained demand drivers imply continued expansion into the early 2030s. For corporate strategists, this baseline trajectory validates both incremental capacity investments and targeted R&D bets — but it also demands a differentiated approach to customer segmentation, channel strategy, and regulatory readiness to capture disproportionate share.
Gas Detectors Market
Key market dynamics shaping 2026 planning
- Regulatory acceleration: A wave of jurisdictional requirements and standards — from municipal codes for residential gas alarms to pipeline leak-detection mandates and workplace H2S monitoring rules — is elevating the minimum technical and reporting requirements for deployed systems. Operators and OEMs must align product specifications and certification roadmaps to these new baselines.
- Standards-driven procurement: Performance standards and regulatory references are becoming procurement filters. Entities that can demonstrate compliance to recognized standards find it easier to win enterprise-level contracts and long-term service agreements.
- Hydrogen and new gases: Energy transition projects are driving demand for detectors designed for novel atmospheres and lower detection limits, especially hydrogen-focused sensors and explosion-proof enclosures suitable for mixed energy environments.
- Digitization and lifecycle services: Connected detectors, cloud-enabled fleet management and predictive maintenance services are maturing into revenue pools with higher lifetime value than one-off hardware sales.
- Channel and aftermarket economics: Calibration, certification, and localized servicing are rising as strategic levers — firms that integrate hardware, software and service deliver compelling total-cost-of-ownership propositions to large industrial customers.
Regulatory and institutional context — implications for compliance and procurement
Recent and near-term regulatory changes are not abstract; they are operational: municipal building codes now require zoned natural gas detection for certain dwelling classes, pipeline regulators have mandated leak-detection performance thresholds, and major safety agencies are reinforcing standards for workplace monitoring and residential alarms. These shifts compress timelines for deployed upgrades and increase the technical floor for acceptable products. For example, operators subject to pipeline leak-detection rules will prioritize commercially available solutions that meet recognized performance standards when re‑tendering programs.
Gas Detectors Market
Technology and product innovation trends to watch
- Sensing modalities: IR, electrochemical, catalytic, and advanced solid-state sensors each retain distinct use-cases. The choice is increasingly driven by the gas-species mix, required response time, and lifecycle cost considerations.
- Connected and managed solutions: The move from stand-alone detectors to managed fleets — including asset tracking, firmware orchestration, and cloud analytics — is creating recurring revenue opportunities and differentiation.
- Hydrogen-specific designs: New detection chemistries and housings optimized for hydrogen service are appearing in product roadmaps, reflecting event-driven demand from hydrogen production, storage, and fueling projects.
- Integration with process-safety systems: Vendors that bundle gas detection into broader safety and control stacks (including fire, flame, and leak management) are increasing their share of large-scale projects.
Competitive landscape — actionable profile of incumbent and emerging players
The market is commercially mature and moderately concentrated: the top three manufacturers account for a clear majority of market value, with the top five controlling an even larger portion of revenue. Against this backdrop, strategy must balance competitive defense and selective partnership or acquisition.
- Honeywell International Inc. — A broad portfolio across portable and fixed systems, with strong brand recognition in industrial, confined-space and utility applications. Its multi‑brand approach gives it reach across enterprise accounts and service channels.
- MSA Safety Incorporated — Deep in portable multi‑gas detection and established across mining and hazardous-environment use cases; recognized for rugged product lines and field service ecosystems.
- Drägerwerk AG & Co. KGaA — European engineering leader with solid penetration in chemical and process industries; technical depth in oxygen, toxic and combustible gas monitoring.
- Teledyne Gas and Flame Detection — Strengths in open-path and fixed-point systems for oil & gas and marine sectors; often selected for large-scale safety projects.
- Emerson Electric Co. — Provider of infrared-based detection technologies and integrated process-safety solutions, attractive to process automation buyers.
- Industrial Scientific, RKI, Crowcon, Macurco, GDS, Det‑Tronics, Sensidyne, Global Detection Systems, WatchGas — Each occupies focused niches such as personal detectors, semiconductor fabs, fleet-connected devices, hydrogen models, bespoke system builds, high-reliability process detectors, laboratory applications, and emergency‑response gear respectively.
Recent competitive moves reinforce broader trends: connected portable ranges and fleet management (announced in late 2025), hydrogen-focused product introductions and trade-show debuts in mid‑2026, and refreshed product catalogs targeting enterprise procurement cycles. These events are timely signals for procurement teams and R&D planners.
What the PW Consulting report delivers — practical, transaction-ready intelligence
- Top-line market sizing and seven-year forecasts by value, with sensitivity scenarios to stress-test demand under different regulatory and energy-transition pathways.
- Detailed go-to-market playbooks for hardware vendors and service providers, including channel design, pricing levers, and contract structures that maximize recurring revenue.
- Regulatory matrix mapping jurisdictional requirements to product certification needs and procurement triggers.
- Buyer persona and procurement decision maps for oil & gas operators, chemical plants, utilities, mining firms and public safety agencies.
- Technology adoption curves and sensor selection frameworks that translate gas chemistry and use-case into procurement specifications.
- Competitive benchmarking and M&A screening criteria identifying pockets of consolidation and white-space segments suitable for bolt-on acquisitions.
- Supply chain risk heatmap covering critical components, certification lead times, and recommended mitigation levers for 2026 supply planning.
Strategic implications and recommended actions for 2026
- Compliance-first product roadmaps: Ensure new product specifications are aligned with the latest performance standards and jurisdictional rules. Non‑compliance is an adoption blocker in enterprise tenders.
- Prioritize connected solutions: Accelerate development or partnerships for cloud and fleet‑management capabilities; these features increasingly determine renewals and service contract length.
- Service-led growth: Build calibrated aftermarket offerings (field servicing, accredited calibration, subscription models) that convert one-time hardware buyers into multi-year revenue streams.
- Targeted M&A and partnerships: Use the market’s concentration dynamics to pursue bolt-on technologies (e.g., hydrogen sensing, data analytics) or regional service providers that improve market access.
- Procurement playbooks: For end-users, standardize detector specifications to simplify vendor evaluation and leverage competitive sourcing when regulations force accelerated rollouts.
- Risk and resilience planning: Map supplier single points of failure and build dual-sourcing or inventory buffers for critical sensor types ahead of project ramp-ups.
How to use this briefing — next steps
This briefing is a strategic appetizer: it demonstrates the depth of analysis and the kind of executable intelligence we deliver. For teams preparing 2026 capital plans, procurement strategies, or M&A screens, our full report contains the granular segmentation, regional demand models, vendor scorecards, and financial benchmarks required to convert insight into action. Contact PW Consulting to request the complete study and the supporting spreadsheets that drive scenario modelling and vendor shortlists.
In an environment where regulation, technology and the energy transition converge, the decisions you take in 2026 will shape your safety portfolio and market position for years to come. Use this research to align compliance, commercial and technical priorities — and to move from reactive specification to proactive market capture.
For detailed analysis of this topic, please visit the official page: Gas Detectors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com