

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PDMS Market — 11.2% CAGR (2026–2032), USD 888.06M in 2025

Patient Data Management Systems (PDMS) Market — Strategic Briefing for 2026 Decision-Makers
As healthcare providers, technology vendors and investors recalibrate strategy for a post-pandemic, digitally accelerated care environment, Patient Data Management Systems (PDMS) sit at the intersection of clinical workflow optimization, device connectivity and regulatory compliance. This briefing synthesizes the macro dynamics from PW Consulting’s upcoming PDMS market study to highlight the strategic imperatives that will matter for 2026. It is a purposeful preview: we reveal analytical depth and directional conclusions while preserving the granular segmentation and proprietary forecast tables for the complete report.
Patient Data Management Systems (PDMS) Market
Why this research matters for 2026
Hospitals and health systems face compressed decision windows in 2026: capital cycles, regulatory deadlines, and cybersecurity exposures are converging. Our study quantifies the market trajectory and maps the operational pressures that will determine winners and losers. At a high level, the PDMS market demonstrates robust expansion — the sector is forecast to grow at a strong double-digit compound annual growth rate into the next decade, with total market size roughly doubling over the forecast horizon. This pace underscores both the urgency and the opportunity for investment in interoperable, secure PDMS implementations.
Patient Data Management Systems (PDMS) Market
Top-line market context
- Base year and horizon: Our analysis is anchored on 2025 as the base year with a 2026–2032 forecast horizon to capture near-term policy cycles and mid-term technological adoption curves.
- Growth profile: The market is growing at an accelerated clip, driven by hospital digitization programs, acute care modernization, and cloud-native platform transitions. This creates a multi-year window for capture of incremental PDMS revenue and services.
- Commercial structure: The competitive landscape blends specialized PDMS vendors with broader medical device and health IT suppliers. Market control is concentrated among established vendors that combine clinical domain expertise with device integration capabilities.
Market dynamics shaping 2026 decisions
- Regulatory and standards pressure: PDMS are regulated as medical devices in many jurisdictions, requiring documented risk management and compliance pathways. New guidance is increasingly embedded within PDMS feature baselines, which shortens development-to-deployment cycles for compliant offerings but raises the bar for validation and documentation during procurement.
- Public funding and national programs: Targeted funding initiatives in some countries have accelerated PDMS adoption in acute care settings. Buyers capitalizing on such funding windows can leapfrog legacy constraints, but must align procurement timelines with grant or subsidy conditions.
- Cloud transformation vs. operational resilience: Several major hospital programs are transitioning to cloud-based EPD/HIS platforms. Cloud migration enables scalable PDMS integrations and analytics but creates new attack surfaces and operational dependencies, as recent ransomware incidents in the region have starkly demonstrated.
- Workforce constraints and automation ROI: Staff shortages and nursing workload pressures make automated data capture, closed‑loop medication support and streamlined documentation not just efficiency plays but essential risk mitigation measures. PDMS implementations must therefore be assessed for both direct efficiency gains and indirect clinical safety benefits.
Technology and integration trends
- Device-first interoperability: Successful PDMS projects are those that treat device connectivity as a primary product requirement — ventilators, monitors, infusion pumps and OR devices must feed reliable, timestamped data streams into a single clinical view.
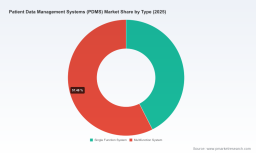
- From point solutions to ecosystem platforms: The market is evolving from single-function modules toward multifunction, hospital-wide platforms that link PDMS, HIS/EPD and middleware. Buyers must decide whether to prioritize best-of-breed clinical depth or vendor-managed integrated stacks that promise faster time-to-value.
- Closed-loop medication and clinical decision support: Integration with medication management and traceability features is moving from “nice to have” to expected baseline functionality in acute care PDMS deployments.
- Security and resiliency engineering: Cybersecurity must be embedded across the PDMS lifecycle — procurement, implementation, and operations. Incident preparedness and recovery are now differentiators in vendor evaluation.
Competitive landscape — what to watch
Our competitive analysis profiles both specialist PDMS providers and broader health IT manufacturers. Several incumbent and regional leaders stand out for different strengths:
Patient Data Management Systems (PDMS) Market
- NEXUS AG (Germany) — Known for certified PDMS integrations that tightly couple ICU device connectivity with hospital information systems (HIS). Their offerings emphasize medication management, nutrition balance and pediatric-specific functionality, positioning them well in specialized acute care workflows.
- Dräger (Germany) — Offers a suite geared toward centralized data management across ICU, OR and NICU environments, with a strong record in monitoring and traceability of prescriptions. Their proposition is attractive for hospitals seeking deep acute care monitoring alignment.
- BIOMEDICA Medizinprodukte GmbH (Germany) — Focused on anaesthesia and intensive care departments with solutions that centralize documentation and improve cross-hospital communication and data quality. Recent deployments illustrate their ability to deliver standardized documentation across multiple institutions.
- ChipSoft B.V. (Netherlands) — Integrates PDMS functionality into broader electronic patient dossier (EPD) platforms with hospital-wide device communication. Their pivot to cloud-native HIS/EPD architectures highlights both the upside of modernization and the operational risks associated with cyber events.
Recent vendor developments exemplify the market’s trajectory and the new risk/return calculus:
- BIOMEDICA’s recent multi-hospital PDMS deployment demonstrates the acceleration of standardized documentation across provincial healthcare networks.
- ChipSoft’s cloud migration programs show how cloud-enabled HIS/EPD initiatives can accelerate integrations, while a contemporaneous ransomware incident underscores the need for rigorous cybersecurity contingencies in vendor selection.
- Industry showcases and integrations (e.g., DMEA 2026 demonstrations) confirm an acceleration in closed-loop and point-of-care integration propositions from niche integrators and device partners.
Strategic implications for 2026 planning
For executive teams, purchasing leads and investors, the study converts macro signals into actionable strategy options:
- Procurement timing: Align capital and implementation schedules with national funding cycles and regulatory deadlines. Early movers who secure grants and start integration projects in 2026 can realize disproportionate operational benefits in the following years.
- Vendor selection framework: Elevate cybersecurity, device interoperability and regulatory-ready documentation to primary selection criteria. Don’t trade clinical depth for integration convenience unless total cost of ownership and clinical outcomes are demonstrably superior.
- Transition planning: For hospitals migrating to cloud-hosted HIS/EPD platforms, architect PDMS projects with robust failover, segmented networks and clear SLAs for incident response — a “lift-and-modernize” strategy without hardened resilience can increase downstream risk.
- Value capture and ROI measurement: Design pilots and phased rollouts to capture both labor-savings and clinical-safety KPI improvements. The most defensible business cases combine efficiency metrics with reduced adverse events and documentation quality gains.
- Partner and M&A playbooks: For vendors and private investors, consolidation opportunities exist in niche clinical PDMS modules and device connectivity middleware. Strategic acquisitions that expand hospital footprint or close critical integration gaps will accentuate competitive advantage.
What the full PW Consulting PDMS study delivers
The full report moves beyond directional commentary to provide the operational intelligence required to act in 2026. Key deliverables include:
- Comprehensive market sizing and forecast model (historical and projected figures, 2020–2032) with scenario simulations reflecting different adoption, funding and regulatory pathways.
- Segmentation analysis by region, solution type and clinical application — with interactive tables and downloadable datasets to inform budgeting and go-to-market planning (note: detailed segmentation tables are included in the full report).
- Vendor scorecards that assess product capability across device connectivity, medication management, regulatory readiness and cybersecurity controls, accompanied by vendor risk matrices and roadmap visibility.
- Implementation playbooks and procurement templates that translate clinical requirements into RFP criteria, validation checklists and contractual cybersecurity clauses.
- Case studies and lessons learned from recent deployments and incidents — practical recommendations for mitigation, workforce training and phased adoption.
How to use this intelligence in 2026
- Health system CIOs and CMIOs can use the forecasts and vendor evaluations to prioritize hospital wards and clinical programs for PDMS rollouts and to justify capital requests with market-backed ROI timelines.
- Vendors can map whitespace and partnership opportunities — assessing whether to pursue cloud-native integrations, niche clinical modules, or device-agnostic middleware strategies.
- Investors and private equity can use the consolidation maps and vendor scorecards to identify targets that offer rapid scaling of device connectivity, compliant feature sets, or strong footholds in funded national programs.
Next steps
This briefing is intentionally directional. If you are facing a PDMS procurement decision, vendor negotiation or strategic investment in 2026, the full PW Consulting report provides the granular segmentation, financial modelling and executable playbooks you will need. Visit our report page to access the complete dataset, interactive forecasting model and vendor scorecards that underpin these strategic recommendations.
For detailed analysis of this topic, please visit the official page: Patient Data Management Systems (PDMS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com