

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Beer Market to Reach USD 1,170.34 Billion by 2032

Beer Market 2026: Strategic Imperatives for Growth, Resilience and Value Creation
As PW Consulting’s Chief Industry Analyst, I present an executive orientation to our latest Beer Market study — a deliberately high-resolution, decision-focused analysis calibrated for leadership teams planning 2026 strategies. This preview synthesizes the macro trajectory, competitive dynamics, structural cost pressures and the operational playbooks that will determine who captures value in the coming cycle. It also follows the “trailer” principle: we show the analytic depth and strategic direction here while preserving the report’s full segment-level data and proprietary modeling behind our source page to preserve commercial utility and encourage direct engagement.
Beer Market
A concise market snapshot
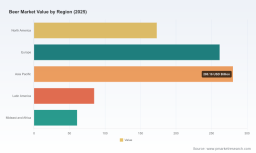
Using 2025 as the base year, the global beer market has expanded materially since 2020. Our topline time series shows the market rising from the mid-700s (USD Billion) in 2020 to USD 860.0 Billion in 2025, reflecting a recovery and reset after pandemic-related disruption. Looking ahead, our forecast model — underpinned by demographic, pricing, and channel dynamics — projects a compound annual growth rate (CAGR) of 4.91% across the 2026–2032 period, taking the market to roughly USD 1,170 Billion by 2032.
Beer Market
That trajectory is not linear: the historical series contains both resilience and volatility, signaling pockets of structural growth (premiumization, non-alcoholic innovation, off-premise omnichannel) alongside episodic headwinds (raw-material cost swings, regulatory shifts, and logistics disruptions). For 2026 planning, executives need to treat the aggregate expansion as an opportunity window — but one that rewards granular positioning, cost architecture, and nimble go-to-market execution.
Beer Market
Why this research matters for 2026 decisions
-
Strategic resource allocation — Our modeling translates the macro growth envelope into probabilistic revenue and margin outcomes under alternative scenarios (e.g., sustained premiumization, accelerated non-alcoholic adoption, or material input-cost inflation). These are designed to inform investment sizing, capacity timing, and channel prioritization for 2026 capital plans.
-
Competitive differentiation — With aggregate concentration metrics indicating a market where the top three and top five players retain meaningful shares, the levers to expand share are increasingly strategic: targeted innovation, regional portfolio optimization and differentiated channel strategies. Our report converts these levers into executable initiatives and KPIs.
-
Risk-aware growth — Input-cost volatility (malt, barley, aluminum) and trade policy shifts can quickly erode margins. We provide scenario stress-tests that quantify EBITDA sensitivity to common shocks and rank mitigation options by effectiveness and time-to-impact.
Core strategic themes for 2026
-
Segmentation-driven premiumization: Consumer willingness to pay continues to migrate toward premium and experiential formats — not uniformly, but in clusters that reward precise local execution. The commercial implication is simple: targeted premium roll-outs, higher mix economics and differentiated pricing governance will be required to convert interest into durable margin expansion.
-
Non-alcoholic and portfolio stretching: Leading brewers are investing in non-alcoholic and alternative malt beverages as both margin and channel-entry plays. Rapid SKU rationalization, accelerated R&D-to-shelf timelines, and marketing investments in mainstream channels will determine winners.
-
Packaging and input-cost strategy: Aluminum and malt cost dynamics are now a core strategic domain. Our research shows packaging conversion choices, supplier contracts, and recycling/closed-loop pilots materially affect cost per liter. Expect integrated packaging strategies — combining material innovation, procurement hedging and circularity — to be a competitive battleground.
-
Omnichannel distribution optimization: The on-trade vs off-trade balance has been recalibrated post-2020. Leading firms are redesigning route-to-consumer strategies with sharper trade promotion economics, subscription and DTC pilots, and data-enabled assortment management.
-
M&A and capability-led consolidation: With medium concentration at the top, M&A is less about scale alone and more about capability capture — craft portfolios, contract-brewing capacity, premium supply chains, and technology-enabled direct channels.
Competitive landscape — what the majors are doing
Our study includes a focused benchmarking of the sector’s largest players and their strategic postures. Highlights:
-
Anheuser-Busch InBev (HQ: Leuven) — Continuing to lean into capacity expansion and local manufacturing investments while prioritizing growth SKUs in the premium and health-forward segments. Leadership is balancing scale with local responsiveness.
-
Heineken N.V. (HQ: Amsterdam) — Reported gains in non-alcoholic and premium segments, underscoring a portfolio play that blends broad distribution with differentiated offerings and brand marketing focused on premiumization.
-
Carlsberg Group (HQ: Copenhagen) — Emphasizing portfolio diversification and market share gains across targeted markets, while calling out packaging and raw-material cost pressures as focal operational priorities.
-
Molson Coors (HQ: Golden, CO) — Managing North American core brands alongside craft and innovation efforts; portfolio complexity and trade dynamics are central to its near-term margin management.
-
Constellation Brands and Boston Beer Company (US firms) — Both illustrate the interplay of import dynamics, tariffs and margin exposure. One firm benefitted from recent tariff removals; another has explicitly flagged tariff pressure as a near-term margin headwind.
These firm-level movements are not isolated: they collectively signal a strategic shift from simple volume growth to margin and capability-driven competition. Our report translates these observations into competitor scorecards and prioritized response options for new entrants and incumbents alike.
Operational levers and near-term playbook
For 2026 plans, we recommend decision-makers focus on a tight set of operational levers that the report models quantitatively:
-
Procurement and forward-buying protocols for key inputs (malt, barley, aluminum), combined with supplier diversification and local sourcing where feasible.
-
Packaging optimization: evaluate can-to-bottle economics through a full TCO lens, incorporate conversion and recycling initiatives, and integrate packaging strategies into SKU and channel economics.
-
SKU portfolio pruning and prioritized NPD: concentrate brand and promo support behind high-ROI SKUs while accelerating rollouts of non-alcoholic and premium SKUs in high-opportunity channels.
-
Channel economics redesign: deploy trade-promo ROI tools, roll out high-frequency DTC pilots in strategic markets, and redesign trade terms to align incentives across the on-trade and off-trade continuum.
-
M&A and partnerships: a playbook for sourcing capability-first targets — contract brewers, premium craft portfolios, or logistics and packaging innovators — along with integration templates and synergy capture metrics.
Risks, policy and near-term shocks to monitor
-
Trade policy surprises: Tariff reintroductions or removals can swing import economics and supply-chain routing. Our scenario work models sensitivity of gross margin to plausible tariff outcomes and offers hedging and sourcing mitigations.
-
Raw-material inflation: Malt and barley remain primary cost drivers; firms with better hedging, supplier partnerships and agronomy programs will enjoy durable margin advantages.
-
Packaging supply constraints: Aluminum availability and conversion economics can amplify costs. Firms investing in recycled content, alternative pack formats and local conversion capacity reduce exposure.
-
Consumer preference shifts: Rapid shifts toward non-alcoholic or flavor-driven formats demand accelerated NPD pipelines and agile manufacturing.
What the full report contains — operationally actionable deliverables
PW Consulting’s full Beer Market study is structured for immediate use by strategy, commercial, supply-chain and investor teams. The deliverables include:
-
Comprehensive historical and forecast topline time series spanning 2020–2032 with scenario variants and sensitivity bands keyed to pricing, volume, and mix assumptions.
-
Proprietary segmentation and channel matrices with interactive dashboards (company- and market-level views) enabling drill-down to SKU, pack-format and distribution economics. Please note: detailed segment splits and proprietary unit economics are available inside the full report.
-
Competitor benchmarking with capability maps, near-term strategic moves, and an M&A target universe scored by strategic fit, integration risk and value uplift.
-
Operational playbooks: pricing and promo optimization templates, procurement and packaging strategies, manufacturing capacity plans, and a validated set of KPIs to track 2026 execution.
-
Stress-test models that quantify EBITDA sensitivity to shocks (tariffs, input-cost spikes, and demand shifts) and rank mitigation levers by speed-to-impact and cost-to-implement.
How to use this intelligence in your 2026 planning cycle
Translate the report’s outputs into three concrete actions before Q2 2026 planning freezes:
-
Run the report’s scenario sets against your current FY26 budget to test resilience of EBITDA targets and adjust capital timing where necessary.
-
Use the competitor scorecards and M&A scoring to identify 1–3 capability-led bolt-ons or partnership plays you can diligence in 2026.
-
Implement a rapid packaging and input-cost task force to capture short-term procurement and conversion wins while developing medium-term circularity projects.
Conclusion — where to go next
The beer market is growing on aggregate, but the next wave of value will be captured by firms that align portfolio, procurement and routes-to-market with the nuanced pockets of demand and cost opportunity we identify in this study. The strategic choices you make for 2026 — about where to invest, where to prune, and which capabilities to acquire — will determine whether you gain share in the higher-margin parts of the market or merely chase volume in a structurally evolving arena.
For the full dataset, interactive dashboards, segmentation matrices and the proprietary playbooks referenced above, please consult the report host page. The core intelligence and the granular numbers that plug directly into planning models are available there — including our market concentration analysis and the full competitor benchmarking dossiers that inform the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Beer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com