

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cloud Gaming Market Poised for 28.25% CAGR Through 2032

Cloud Gaming Market 2026: Strategic Outlook and Decision Playbook
Executive primer
Cloud gaming has moved beyond technology demos and headline trials to become a material, investable segment of digital entertainment. Our new PW Consulting market study — anchored on a 2025 base year and a 2026–2032 forecast window — shows a sustained, high-growth trajectory (CAGR: 28.25%) as the industry scales from an early adopter base into broader consumer and enterprise adoption. From a strategic standpoint, 2026 represents a pivotal inflection: connectivity and compute capabilities have matured enough to enable commercial rollouts at scale, while regulatory and energy headwinds are beginning to shape competitive moats and capital allocation decisions.
Cloud Gaming Market
Why this study matters for 2026 decision-makers
- Timing and conviction: With the market expanding rapidly (our analysis places the global market at USD 8.72 Million in 2025, rising toward USD 49.47 Million by 2032), executives who treat 2026 as the moment to operationalize cloud gaming strategies — rather than merely pilot them — position their organizations to capture disproportionate share.
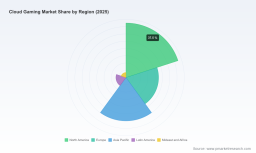
- Competition and concentration: The market exhibits clear concentration at the top: the three largest providers account for a majority share (CR3 ~57.3%), and the top five control roughly three-quarters (CR5 ~74.2%). That dynamic influences partnership choices, pricing tactics, and the viability of niche plays.
- Regulatory and infrastructure risk: Recent regulatory shifts and infrastructure investments are creating asymmetric opportunities across markets. Firms that embed regulatory scenarios and energy-cost sensitivity into their 2026 playbooks will avoid costly mid-course corrections.
Market dynamics that will decide 2026 outcomes
- Edge and 5G are necessary but not sufficient: Carrier-grade 5G Standalone deployments and edge nodes materially reduce latency and broaden addressable audiences; recent national telco packages indicate operators see gaming as a beachhead. Yet, delivering consistent quality also requires cloud platform maturity and developer tooling — a multi-constituent problem that favors alliances between hyperscalers, telcos, and studios.
- Cloud compute, energy, and unit economics: Data center energy demand is rising sharply, and projected increases in power consumption introduce a new layer of operational risk. Cost-of-play economics in 2026 will increasingly hinge on energy sourcing, workload placement (central cloud vs edge), and hardware utilization. Firms must evaluate TCO across these dimensions rather than treating streaming as a pure software expense.
- Regulatory divergence: The regulatory landscape is bifurcating. Some jurisdictions are moving away from net neutrality constraints, while others are doubling down on digital sovereignty and federated telco-cloud initiatives. These opposing forces will create market-specific go-to-market requirements for content delivery, data residency, and interconnection strategies.
- Product and experience differentiation: As baseline streaming quality homogenizes, content licensing, ecosystem integrations, discovery, and latency-tailored UX will separate winners from the rest. Firms that invest in product primitives (adaptive codecs, AI-driven bandwidth optimization, and seamless cross-device state transfer) will win higher ARPU segments.
Competitive landscape: capabilities that matter in 2026
Our vendor analysis synthesizes product roadmaps, go-to-market signals, and recent tactical moves to generate a capability map for 2026 buyers. The leading firms in the space illustrate the strategic archetypes now competing for control of the value chain:
Cloud Gaming Market
- Hyperscaler-integrated platforms (example archetype): Major cloud providers are leveraging global infrastructure and content bundling to offer low-latency, subscription-driven services that scale across devices. Their advantage lies in edge density, platform integrations, and the ability to subsidize customer acquisition via broader bundles.
- Graphics and platform specialists (example archetype): Vendors focused on GPU virtualization and AI-assisted streaming differentiate on fidelity and performance. Their technical lead enables premium experiences (high frame-rate, high-resolution) that appeal to core gamers and premium tier subscribers.
- Integrated device and entertainment firms (example archetype): Console and hardware incumbents convert installed base and exclusive content into cloud propositions designed to retain high-value users without requiring new hardware purchases.
- Regional and niche aggregators (example archetype): Smaller providers and regional champions deliver localized catalogs, device-specific integrations, and white-label solutions that address market-specific content, billing, and latency constraints.
Recent market moves and what they signal
- Platform scaling and optimizations: Leading cloud platforms have doubled down on optimizations and edge expansion to capture broader device footprints. These efforts reduce entry friction for casual users and enable live migrations of game state across devices.
- Hardware and ecosystem integrations: Pre-installation agreements and native integrations on gaming handhelds and smart devices accelerate user acquisition and reduce friction in the funnel from discovery to play.
- AI and quality optimization: The infusion of AI into streaming stacks — from perceptual encoding to dynamic resource allocation — is creating new levers for quality improvement that materially affect perceived value at the point of consumption.
- Telco and edge commercial models: Operators are packaging low-latency gaming services into consumer and enterprise offerings, hinting at subsidized connectivity and B2B2C monetization models that can quickly scale user bases when paired with compelling content catalogs.
What the full PW Consulting report delivers (practical, decision-ready content)
This study is designed as an operational toolkit for corporate leaders, investors, and product teams preparing 2026 strategies. Key deliverables include:
Cloud Gaming Market
- Market sizing and high-resolution forecast model (2026–2032) calibrated to demand elasticity, device penetration, and monetization archetypes.
- Vendor capability matrix and strategic decision trees for choosing partners across cloud providers, telcos, and content studios.
- Go-to-market playbooks for four archetypal entrants (hyperscaler-led, graphics-specialist, console-integrator, regional aggregator) with sample KPIs, pricing experiments, and marketing levers.
- Regulatory scenario planning and mitigation blueprints that translate policy shifts into commercial actions (data residency plans, interconnection strategies, and contingency routing).
- Edge placement and TCO models that quantify trade-offs between centralized cloud and telco-edge deployments under varying energy and bandwidth cost assumptions.
- Studio and content acquisition frameworks that show how to prioritize catalog investment vs. platform feature investment to accelerate monetization.
Strategic imperatives and recommended first moves for 2026
- Reassess content vs. infrastructure trade-offs: Decide whether to compete on content exclusivity, platform experience, or a hybrid approach. Our scenarios demonstrate that customer retention benefits from differentiated content, but unit economics improve with infrastructure partnerships.
- Lock modular partnerships, not monolithic dependencies: Given top-player concentration, firms should design multi-vector partnerships (edge access, interconnect, content licensing) that preserve optionality and reduce single-partner exposure.
- Embed regulatory scenarios into financial planning: Build flexible deployment templates that can be reconfigured by region to meet sovereignty or net-neutrality-related constraints while controlling costs.
- Prioritize energy-aware operations: Incorporate renewable sourcing, workload scheduling, and regional load balancing into capacity plans to mitigate the rising energy footprint risk and secure long-term economics.
- Invest in perceptual quality improvements: Small gains in perceived latency and resolution (achieved through codecs, AI, and adaptive bitrate) yield outsized conversion and retention improvements in consumer cohorts.
Closing perspective
Cloud gaming is entering a commercialization phase where execution clarity and architectural discipline will determine winners. The market is expanding rapidly — growing from an early base in 2020 to a materially larger market by 2025, and projected to continue expanding through 2032 — but the winners in 2026 will be the organizations that combine pragmatic infrastructure decisions, content strategy, and regulatory foresight.
PW Consulting’s full report provides the granular models, vendor scorecards, and step-by-step playbooks required to convert the macro opportunity into executable plans. The analysis is intentionally detailed in source deliverables while this introduction is curated to highlight strategic implications — contact us or visit the report page to unlock the complete datasets, segmentation matrices, and implementation templates necessary for confident decision-making in 2026.
For detailed analysis of this topic, please visit the official page: Cloud Gaming Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com