

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Nursing Bras Market to Reach USD 2,510M by 2032 at 8.1% CAGR
By pmarketresearch, 2026-07-09
Nursing Bras Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s Nursing Bras Market study is designed as an operational playbook for executives, product leads, and investors preparing decisions across 2026. This briefing distills the study’s strategic value: it reveals why the category is shifting from a niche postpartum accessory into a mainstream, innovation-driven subsegment of intimate apparel—and which levers matter most for near-term commercial success. We surface the structural drivers, competitive moves, and supply-chain constraints that will determine winners, while deliberately reserving the full, granular segmentation and scenario tables for the complete report.
Nursing Bras Market
Market trajectory and why 2026 is pivotal
The category moved from a stable niche in the early 2020s to a double-digit growth trajectory by mid-decade. Our base-year analysis (2025) benchmarks the global market at approximately USD 1.48 billion, with a compound annual growth rate of 8.1% across the forecast window (2026–2032). By 2032 the market is projected to exceed USD 2.5 billion under the baseline scenario. That pace is sufficient to change strategic calculus for mainstream apparel brands, private-label retailers, and specialist innovators alike: what was once incremental revenue now represents a platform for adjacent services (pumping solutions, subscription replacement, certified materials) and durable customer relationships across pregnancy and postpartum cohorts.
Nursing Bras Market
Three structural dynamics converge to make 2026 a strategic inflection point:
Nursing Bras Market
- Product innovation (hands‑free pumping, breathable quick‑dry zones, seamless wireless constructions) is moving from premium niche to broad market adoption.
- Regulatory and certification pressures (material safety and Oeko‑TEX® standards) are increasing supplier switching costs and raising barriers for low‑quality entrants—this is shifting the competition from low‑price to product‑quality and compliance differentiation.
- Retail and reimbursement pathways (including selective insurer reimbursement and workplace breastfeeding support programs) are beginning to amplify distribution beyond traditional maternity channels.
Strategic implications for 2026 corporate planning
Leaders who use this report convert macro trends into executable choices across five decision domains:
- Portfolio strategy: Invest selectively across wireless, underwire, and hands‑free pumping variants based on margin and brand fit. The market rewards clarity—brands that present a coherent “from pregnancy to pumping” narrative outperform those that treat nursing bras as an afterthought.
- Manufacturing & sourcing: Expect rising emphasis on certified materials and skilled sewing labor. Firms should map supplier certification status, labor specialization, and audit trail to de‑risk scale. Near‑sourcing options matter for speed-to-market of seasonal innovations.
- Pricing & channel mix: Entry-level price points remain important for volume; premium features (pumping compatibility, advanced fabrics) justify higher ASPs and direct-to-consumer channels. Retail assortment decisions should balance trial-driven low-price SKUs and margin-rich premium cores.
- Go-to-market & partnerships: Strategic collaborations—co‑branded bundles with pumping device manufacturers or lactation service providers—accelerate adoption, as seen in recent industry tie‑ups. Retailer and insurer pathways can materially expand addressable reach when paired with clinical validation.
- M&A & innovation scouting: Consolidation and tuck‑ins are already reshaping concentration in parts of the market. Identify targets that provide proprietary hands‑free designs, pump integration, or certification advantages before competition escalates multiples.
What the full PW Consulting report delivers (practical, transaction‑grade)
This market preview accompanies a comprehensive dossier built for implementation. Key operational deliverables included in the full report:
- Proprietary market sizing and demand model (historical 2020–2025 and forecast 2026–2032) with scenario sensitivities to price, channel mix, and hands‑free adoption rates.
- Go‑to‑market playbooks for direct-to-consumer, specialty retail, and mass retail channels, showing SKU rationalization, pricing ladders, and promotion timing to optimize lifetime value.
- Supplier risk maps and a certification tracker focused on material safety (e.g., Oeko‑TEX®), labor skill requirements for inclusive sizing, and supplier lead times by region.
- Segment playbooks—buyer personas for lactating and pregnant cohorts, retailer decision trees, and product feature-set prioritization to maximize conversion.
- Competitive heat maps and M&A candidate shortlists with valuation heuristics tied to portfolio synergies and scale economics.
- Regulatory impact assessment and reimbursement opportunity matrix by major markets—highlighting where partial insurance coverage or workplace programs can be leveraged.
Note: this preview highlights the types of segmentation and models included. The full report contains the granular regional, type, and application splits and underlying datapoints that leaders use in board‑level business cases.
Competitive landscape: profiles and strategic postures
The market’s competitive structure exhibits moderate concentration; three firms account for a meaningful share of branded sales while the top five control a larger portion of specialty revenues. This leaves room for nimble challengers and retailer private labels, but also benefits incumbents that can scale innovation and certification investments quickly.
Representative competitive archetypes analyzed in the report include:
- Specialist innovators — Brands that foreground hands‑free pumping and inclusive sizing, investing in fabric engineering and user‑centric closures. These players are driving product feature expectations in higher‑value channels.
- Heritage intimates — Established bra manufacturers that bring category expertise and distribution scale; their advantage lies in fit engineering and trusted retail relationships.
- Retail/private‑label players — High-volume, value-focused offerings that accelerate category penetration among price‑sensitive buyers; these players pressure conversion economics for all competitors.
We profile specific companies that illustrate these archetypes and their strategic moves—examples include Kindred Bravely (leader in wireless, hands‑free and inclusive sizing innovations), Cake Maternity (full‑coverage and bust‑support specialization), Bravado Designs (seamless everyday comfort and fit focus), Davin & Adley and Momcozy (pump‑integration and hands‑free design leaders), plus European specialists like Anita and Medela who emphasize technical fabrics and clinical compatibility. Recent activity—product launches, award recognitions, and collaborative bundles—signal an acceleration of product differentiation and channel partnerships that will be decisive in 2026.
Supply chain, regulation, and consumer behavior — the operational constraints
Three “noise” factors in the operating environment require immediate attention:
- Labor specialization: Manufacturing nursing bras requires precise cutting and sewing to deliver inclusive fits across size ranges. Labor skill and factory capacity are bottlenecks for rapid line expansions, increasing the value of supplier relationships and manufacturing flexibility.
- Material compliance: Certification standards for maternal apparel are tightening—Oeko‑TEX® and related textile certifications influence supplier selection and time‑to‑market. Brands that pre‑certify fabrics reduce downstream compliance costs and retailer objections.
- Consumer shifts: Wireless and hands‑free pumping styles are moving from trend to expectation in several leading markets. Pricing remains bifurcated: value SKUs drive trial, while advanced features command premium pricing. Reimbursement and workplace support programs are early amplifiers of demand in select geographies.
Recommended 90‑/180‑day roadmap for 2026
- 30 days: Conduct a rapid supplier certification audit and prioritize fabrics that meet Oeko‑TEX® and quick‑dry specifications; identify at least two near‑sourcing options for pilot SKUs.
- 90 days: Validate two pilot SKUs—one wireless hands‑free and one value everyday style—with controlled retail and DTC channels; run A/B pricing and shopper experience tests linked to conversion and returns metrics.
- 180 days: Finalize channel mix guided by pilot economics, secure strategic partnership(s) with lactation or pump manufacturers for bundled offers, and prepare a 12‑month product roadmap emphasizing certification lead times and inventory cadence.
Why PW Consulting’s study accelerates your 2026 decisions
Executives tell us they need three things to move fast: credible market sizing, actionable operational playbooks, and targeted competitive intelligence tied to transaction opportunities. This study delivers all three. It translates macro momentum (baseline market size and 8.1% CAGR) into executable next steps and measurable KPIs—without overwhelming readers with raw micro‑splits in this preview. The full report contains the segmentation, price‑band models, and competitive benchmarking necessary to build investment cases, product roadmaps, and M&A screens for 2026.
For senior leaders planning product launches, channel expansion, or M&A activity in 2026, the study provides the data, scenarios, and operational tools to convert market growth into sustainable margin and market share. Access the complete report to unlock the detailed regional and application breakdowns, SKU-level demand curves, and candidate lists that underpin our recommendations.
For detailed analysis of this topic, please visit the official page: Nursing Bras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Axial Fan Market 2026: Strategic Intelligence Briefing for Executive Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise yet richly informed preview of our full Axial Fan Market research — calibrated to inform corporate strategy in 2026. Anchored on a 2025 base year and a 2026–2032 forecast horizon, the market exhibits steady expansion with a 5.5% CAGR and a projected upward trajectory through 2032. This briefing distills the factors that will most materially influence investment choices, product roadmaps, supply-chain positioning, and M&A activity next year, while preserving the granular proprietary data in the full report to which this note directs readers.
Axial Fan Market
Why this study matters for 2026 decisions
-
Regulatory inflection points are accelerating product obsolescence windows. New energy-efficiency mandates in key jurisdictions are already reshaping specification curves and procurement criteria for HVAC and cooling infrastructure.
Axial Fan Market -
Technology transitions — notably wider adoption of EC motor platforms and integrated control systems — are altering cost structures, aftermarket service models, and competitive moats.
Axial Fan Market -
Supply-chain volatility driven by tariffs on steel and aluminum, and constrained component supply (motors, bearings, electronic controls) is forcing firms to rethink sourcing, localisation, and pass-through strategies.
-
Market structure remains moderately fragmented: a meaningful share of demand is met by specialist manufacturers and regional players, while a smaller band of global vendors drive scale-based advantages in R&D, channels, and industrial OEM contracts.
-
For boards and commercial leaders, the practical question is not whether the market grows (it does), but how to capture higher-margin share and de-risk portfolios amid tightening efficiency standards and material-cost pressure.
Key dynamics shaping 2026 strategy
-
Regulatory momentum: The EU’s updated energy performance requirements (ErP 2026) and regionally stringent codes (for example, recent updates to nonresidential cooling tower efficacy standards) will force rapid iteration of product lines and qualification cycles for suppliers and systems integrators.
-
Product and systems evolution: EC (electronically commutated) motor platforms, smarter controls, and integrated thermal management solutions are becoming default options for buyers prioritising lifecycle cost over initial purchase price.
-
Commercial cooling and HVAC OEMs will prioritise modular, serviceable designs to meet both regulation and total cost of ownership thresholds demanded by large end-users.
-
Materials and trade policy: Additional duties on steel and aluminum imports impose near-term cost shocks for manufacturers relying on cross-border supply of housings and blades; mitigation options include supplier consolidation, redesign for alternative alloys, and tariff pass-through contracts with customers.
What the full report delivers (practical, execution-oriented)
-
Validated market sizing and demand scenarios across 2020–2032 with base-year granularity and three stretch-case forecasts under alternative regulatory and input-cost assumptions.
-
Segment frameworks (by product type, application, and region) that identify pockets of margin expansion and areas at risk of commoditisation — presented as actionable frameworks rather than raw tables to preserve commercial value.
-
Competitive benchmarking and capability maps for headline vendors, including technology stacks, go-to-market models, channel exposure, and product roadmaps.
-
Decision-support tools: a regulatory compliance playbook, supplier risk matrix, capex vs. opex modelling templates, and a three-tier M&A/value-capture checklist you can run against your own portfolio.
-
Commercially focused recommendations on pricing levers, after-sales monetisation, and product retirement/upgrade timelines tied to expected efficiency thresholds and buyer procurement cycles.
Competitive landscape — strategic takeaways
-
Technology leaders with EC motor expertise and integrated controls will exert disproportionate influence on specification decisions. Firms that combine high-efficiency motor platforms with precision control (for both HVAC and industrial segments) are positioned to command premium pricing and longer OEM relationships.
-
Global players continue to invest in both organic product development and inorganic consolidation to shore up manufacturing scale and broaden addressable markets. Recent corporate moves demonstrate that acquisitions remain a preferred route to accelerate capability build-out.
-
Regional and specialist manufacturers retain advantages in customised, large-format axial fan applications (cooling towers, industrial ventilation) where bespoke engineering and service depth beat product commoditisation.
-
Channel and OEM partnerships matter: vendors integrated into cooling-tower and HVAC equipment supply chains can leverage system-level savings to protect margins even as component prices fluctuate.
-
Notable market activity to watch: product launches and regulatory-compliant ranges rolling out in response to ErP timelines, acquisitions that vertically integrate motor or control capabilities into fan production, and heightened trade-show presence by innovators previewing 2026-compliant portfolios.
Brief company-positioning snapshot
-
Manufacturers with deep EC motor IP and precision-control focus are best placed to lead category refresh cycles and capture the premium segment of HVAC and rail/industrial applications.
-
Established fan specialists with strong industrial OEM relationships dominate large-form-factor applications and retrofit projects, especially where service life and custom engineering are critical.
-
Electronics-led suppliers that marry fan hardware with compact, high-efficiency drives and thermal-management components are creating integrated value propositions attractive to electronics and data-center customers.
Strategic recommendations for 2026 (prioritised)
-
Immediate compliance audit: Map current product ranges against expected jurisdictional efficiency thresholds and set a hard timeline to phase non-compliant SKUs out of key markets.
-
Portfolio stress-testing: Run a margin-impact scenario that combines tariff shocks on steel/aluminum with accelerated EC adoption — use the report’s scenario models to identify which SKUs to re-engineer, retire, or premiumise.
-
Supply-chain rebalancing: Implement a three-tier sourcing strategy (core qualified suppliers, regional dual-sourced suppliers, and contingency partners) to mitigate tariff and logistics risk without sacrificing quality or lead times.
-
Accelerate EC and controls roadmap: Prioritise development or acquisition of electronically commutated motor platforms and embedded controls that enable performance claims needed for new energy codes and service-based monetisation.
-
M&A & partnership playbook: Target bolt-ons that add control-electronics IP, finishing/assembly capacity in low-tariff jurisdictions, or established service networks in high-value segments.
-
Commercial model refresh: Move from transactional unit sales to bundled lifecycle offers (guaranteed performance + predictive maintenance) where contract terms allow for premium capture.
Executive checklist — first 90 days
-
Complete a rapid regulatory impact map for your top three addressable markets and identify immediate compliance gaps.
-
Run dealer and OEM contracts to assess pass-through clauses for input-cost increases and determine levers for renegotiation.
-
Initiate prototype trials for EC retrofits or high-efficiency models in one commercial and one industrial account to validate TCO messaging.
-
Audit your supplier base for exposure to steel/aluminum duties and identify potential low-cost regional partners or consolidation targets.
-
Scan the M&A landscape with a shortlist of targets that accelerate control-electronics capability or provide immediate geographic advantage.
Axial fan markets are transitioning from a component-driven to a systems- and service-driven industry. For executives making capex, sourcing, or M&A decisions in 2026, the winners will be those that align product roadmaps with regulatory windows, de-risk input costs through intelligent sourcing and design, and monetise post-sale services enabled by smarter controls.
PW Consulting’s full Axial Fan Market report supplies the detailed segmentation, vendor scorecards, and the quantitative models you need to operationalise these recommendations. Access to the complete dataset and executable templates is available through our report portal; the full intelligence package equips executive teams to convert the market’s steady growth and regulatory momentum into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Axial Fan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
CTC Market to Reach USD 31.41 Billion by 2032 with 13.92% CAGR — PW Consulting Insights
By pmarketresearch, 2026-07-09
Circulating Tumor Cells Market — Strategic Preview for 2026 Decision-Makers
As life-science firms, investors, and health-system leaders set strategic priorities for 2026, the circulating tumor cells (CTC) market has reached an inflection point. Our new PW Consulting report synthesizes five years of historical performance and presents an actionable forecast through 2032. In short: this market has doubled in scale since 2020, continues to expand at a double‑digit compound annual growth rate, and is being reshaped by targeted product launches, shifting regulatory postures, and payer skepticism that together define near-term commercial risk and long‑term opportunity.
Circulating Tumor Cells Market
Why this study matters for 2026 strategy
-
Timing and clarity: 2026 is the first full year after several pivotal device launches and clinical collaborations; firms need a clear view of adoption curves, reimbursement headwinds, and competitive moats to allocate R&D and commercial resources efficiently.
Circulating Tumor Cells Market -
Risk-aware growth planning: while technological progress is rapid, regulatory and payer assessments remain highly selective. The report equips leadership teams to prioritize investments that are de‑risked by clinical utility or structured to create near‑term revenue streams.
Circulating Tumor Cells Market -
Commercial insight: we translate macro momentum into practical choices — route‑to‑market, channel strategies, pricing levers, and partnership frameworks that can materially change a product’s probability of success in the next 24 months.
High-level market trajectory (concise)
From a macro perspective, the CTC market expanded from approximately USD 6.2 billion in 2020 to USD 12.5 billion in 2025. Our base‑year anchoring in 2025 informs the forecast window 2026–2032, where the market is projected to grow at a compound annual growth rate of 13.92%, reaching roughly USD 31.4 billion by 2032. These aggregate figures reflect accelerating adoption across clinical and research settings, greater throughput in CTC enrichment/detection platforms, and expanding demand for downstream molecular analysis.
What the report delivers — practical, executable content
-
Proprietary market model: bottom‑up revenue model calibrated to device classes, sample throughput, and pricing sensitivity. The model is scenario‑ready (base, conservative, aggressive) for board‑level review and mid‑year reforecasting.
-
Clinical and regulatory intelligence: mapping of cleared and investigational devices, payer policy snapshots, CPT and reimbursement mechanics, and an assessment of what evidence payers will require to shift coverage decisions.
-
Technology and product roadmaps: comparative assessment of enrichment, detection, and analytical modalities — practical guidance on which technology bets are most likely to scale commercially versus those that will remain niche research tools.
-
Commercial playbooks: go‑to‑market recommendations by customer segment (diagnostic labs, oncology centers, CROs, academic reference labs) including channel design, salesforce sizing heuristics, and digital adoption tactics.
-
Competitive landscaping and M&A readiness: profiles of incumbent and emerging vendors, assessment of competitive moats, and valuation anchors for M&A or partnership conversations.
-
Investment and risk framework: identification of the critical inflection points (clinical readouts, regulatory clearances, reimbursement decisions) that should trigger capital deployment or exit planning.
-
Data annex and methodology: transparent assumptions, input tables, and sensitivity analyses to support internal audit and independent validation.
Regulatory and reimbursement dynamics — the gating factors for 2026
The market’s commercial pathway is uneven. A small number of platforms have secured regulatory clearances for limited clinical use, and a broader set of devices remains in investigational or research‑use categories. At the payer interface, major commercial and public payers continue to view routine CTC testing for most indications as investigational, limiting immediate reimbursement upside. That said, existing CPT pathways and discrete billing codes for CTC enumeration and interpretation provide a foundation for staged commercialization where clinical utility is demonstrated.
For 2026 planning this means: companies must sequence evidence generation and commercialization. Those with regulatory clearances should prioritize post‑market studies that link test results to actionable clinical decisions. Firms still in development should design registrational pathways that explicitly address payer endpoints — not just analytical performance.
Competitive landscape — actionable takeaways
The CTC competitive set is anchored by a handful of established players with differing strategic postures. Some firms focus on clinically oriented, IVD‑grade systems; others supply kits and reagents serving research and translational labs. Recent industry activity underscores two concurrent dynamics: incumbents are upgrading core platforms to extend biomarker breadth and workflow efficiency, while agile challengers are advancing clinical collaborations to validate niche, high‑value use cases.
-
Platform incumbents: several established diagnostics companies have deep installed bases and IVD products designed for enumeration and isolation of CTCs. Their strategic advantage lies in regulatory experience, clinical validation networks, and channel access into hospital labs. Recent product upgrades announced by leading platform providers reflect a push to broaden biomarker compatibility and improve cell recovery — moves that reinforce defensibility in clinical settings.
-
Technology challengers: a cohort of specialist firms has focused on intact cell capture or single‑cell recovery for downstream molecular analysis. These companies are executing clinical collaborations aimed at high‑value oncology indications (metastatic disease monitoring, companion diagnostics). Positive interim clinical study results and collaborative designs with academic centers are shortening the path to utility‑driven adoption.
-
Consumables and assay providers: kit and reagent suppliers are pursuing scalable assay formats and partnerships with platform owners to embed downstream analytics. Their business model can be high‑margin recurring revenue once a base instrument install is established.
Strategically, incumbents should defend by extending platform capability and payer‑facing evidence, while challengers should focus on niche indications with clear clinical decisions tied to test output.
Recent industry movements worth 2026 attention
-
Product evolution: a major platform vendor announced an upgraded, next‑generation CTC detection system with broader biomarker support — this has implications for labs planning hardware refresh cycles in 2026–2027.
-
Clinical collaborations: several smaller innovators have initiated or expanded clinical programs with leading academic centers, aiming explicitly at metastatic oncology indications — these programs are potential accelerants for payer conversations if they demonstrate impact on treatment decisions.
-
Positive interim study outcomes: early positive clinical data for a harvest‑based system in indication‑specific monitoring suggests that targeted use‑cases (e.g., therapy response in certain tumor types) could be the beachhead for wider acceptance.
Implications and recommended actions for 2026
-
For device manufacturers: prioritize clearance pathways that align with payer endpoints; invest in platform features that reduce sample loss and increase biomarker compatibility; design commercial pilots with integrated health‑economic endpoints.
-
For diagnostic labs and health systems: plan phased adoption tied to clear clinical programs (e.g., trial integration or tumor boards) rather than broad deployment. Negotiate risk‑sharing agreements with vendors for early adopters to limit downside as evidence matures.
-
For pharma and CROs: use the expanding CTC toolbox to enrich clinical trials for minimal residual disease and response stratification; align assay selection with regulatory expectations for companion diagnostics where appropriate.
-
For investors and corporate development teams: target assets that either (a) provide defensible clinical utility evidence, or (b) enable high-margin recurring revenue through consumables and analytics. Avoid projects with long, uncertain reimbursement timelines unless backed by deep capital and a clear evidence plan.
How the PW Consulting CTC study supports your 2026 roadmap
This report is designed to be a working tool for executives. Beyond directional analysis, it supplies the spreadsheets, scenario levers, and commercial playbooks necessary to make high‑confidence choices in 2026: where to allocate R&D dollars, which markets and customer segments to prioritize, how to structure payer evidence projects, and what M&A targets fit specific strategic theses.
Because this preview intentionally omits granular segment tables and proprietary split data, we encourage decision‑makers to consult the full report for the quantitative maps — regional build‑outs, device class economics, and customer lifetime value models — that underpin the strategic recommendations above. The full dataset will allow rapid integration into board materials and investment memos and can be tailored into an executive workshop to translate findings into a 90‑day action plan.
Bottom line
The CTC market is no longer an experimental niche; it is a commercializing field with clear winners emerging but significant regulatory and reimbursement gates remaining. The next 12–18 months will separate technologies that achieve clinically actionable readouts and payer acceptance from those that remain research‑grade. For organizations making 2026 resource allocations, the choice is between investing to secure the evidence and commercialization infrastructure now — or risking downstream obsolescence once standards consolidate. Our report gives you the market map, the evidence priorities, and the commercial playbook to make that decision with confidence.
For detailed analysis of this topic, please visit the official page: Circulating Tumor Cells Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: X-ray Flat Panel Detector Market to Reach USD 2,535M by 2032
By pmarketresearch, 2026-07-09
X‑ray Flat Panel Detector Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s X‑ray Flat Panel Detector Market briefing synthesizes macro momentum, competitive motion and regulatory inflection points into a compact strategic playbook for organizations preparing critical 2026 decisions. Built on a base year of 2025 and a forecast window spanning 2026–2032, the market is modeled to grow at a steady compound annual growth rate (CAGR) of 5.1% through the forecast period. Our historical reconstruction shows a market expanding from the low‑1500s (USD Million) in the early 2020s to an estimated USD 1,800 Million in 2025, with a projected progression toward roughly USD 2,535 Million by 2032.
X-ray Flat Panel Detector Market
Why this research matters in 2026
- Timing: 2026 is a pivot year — technology maturation (CMOS and IGZO alternatives), regulatory windows for large wireless detectors, and industrial adoption cycles converge, creating both windows of opportunity and risk for suppliers and buyers.
- Rate of change: A mid‑single‑digit CAGR disguises important unevenness. Growth pockets are driven by replacements in healthcare fleets, expansion of industrial non‑destructive testing, and targeted new use‑cases (battery inspection, portable radiography). Understanding where incremental dollars will flow is essential for capital allocation and go‑to‑market sequencing.
- Market structure: The market is meaningfully concentrated (the top three vendors control a dominant share and the top five an even larger portion), producing high barriers to rapid entrant scale but also creating predictable consolidation and partnership dynamics that can be exploited by corporate development teams.
What this report delivers — practical, transaction‑ready intelligence
- Validated market sizing and a seven‑year forecast framework (2026–2032) that ties unit, ASP, and revenue trajectories to realistic adoption curves and pricing scenarios.
- Decision trees for hardware OEMs and component suppliers that translate demand scenarios into production and capex plans, including break‑even timing for new detector lines.
- Regulatory and reimbursement playbooks that map approval paths (including 510(k) implications), recommended clinical evidence packages and timelines tailored to detector class and target markets.
- Commercial playbooks: channel segmentation, tender/lease vs. capital sale modeling, and partnership architectures (technology licensing, battery/industrial OEM co‑development, and radiology service networks).
- Supply‑chain resilience assessments with second‑ and third‑tier supplier mapping, single‑sourcing risk scores and suggested mitigation roadmaps.
- Vendor benchmarking and a negotiation toolkit for procurement teams (TCO models, warranty & service templates, and upgrade clauses).
Note: this introduction intentionally omits the report’s granular regional, application and technology split figures so procurement and strategy teams are incentivized to access the full models and vendor scorecards that power our recommendations.
X-ray Flat Panel Detector Market
Key market dynamics and strategic implications
- Technology evolution is the primary value driver. While amorphous silicon remains a mature backbone, alternative sensor technologies (CMOS, IGZO and advanced selenium implementations) are shifting performance/cost tradeoffs. Each platform implies a different upgrade cadence for hospital fleets and industrial inspection lines — firms must align R&D and product roadmaps to the timing embedded in the forecast.
- Regulatory inflection points accelerate adoption in specific product classes. Recent 510(k) clearances for large wireless detectors and stationary systems broaden the addressable market for wireless, large‑format panels and reduce time‑to‑market barriers for entrants with validated clinical evidence. These approvals alter sales cycles and procurement criteria — regulatory strategy should therefore be integrated into product launch planning from day one.
- Concentration creates tactical openings. With the top three and top five vendors holding substantial combined market share, mid‑tier vendors and innovative component providers can pursue asymmetric plays: focused verticalization (e.g., portable, pediatric, battery inspection), platform licensing, or partnership models with imaging system OEMs to leapfrog scale constraints.
- Industrial adoption is a growth lever but demands different go‑to‑market capabilities — field services, integration support and bespoke inspection algorithms. Companies targeting NDT or manufacturing inspection must invest in systems integration and domain sales talent rather than relying on incumbent healthcare channels.
Competitive landscape — who to watch and why
Our competitive mapping highlights established medical imaging incumbents, specialized detector manufacturers and vertically integrated suppliers. Each profile below reflects strategic positioning observed across product portfolios, go‑to‑market footprints and recent corporate actions.
X-ray Flat Panel Detector Market
- Varex Imaging Corporation (Salt Lake City, UT, USA): Known for amorphous silicon XRD series detectors targeted at digital radiography and high‑dose contexts — a strong play in established medical channels and high‑throughput facilities.
- Canon Medical Systems (Tokyo, Japan): Supplier of high‑resolution CsI‑based detectors, with product lines focused on premium clinical imaging; strength lies in integration with modality systems and global service networks.
- FUJIFILM Holdings Corporation (Tokyo, Japan): Provider of versatile detectors (including portable options) with a history of field service and clinical adoption programs enabling diversified customer access.
- Agfa‑Gevaert Group (Mortsel, Belgium): Integrator of detectors into broader digital radiography systems, leveraging image processing software and hospital informatics relationships.
- Konica Minolta Healthcare Americas (Wayne, NJ, USA): Known for glassless designs and durable panels positioned at radiology purchasing sweet spots that balance cost and lifespan.
- Trixell SAS (Moirans, France) and Hamamatsu Photonics K.K. (Hamamatsu, Japan): High‑performance detector developers with solid reputations in clinical image quality and specialized sensor engineering.
- Teledyne Digital Imaging Inc. (Waterloo, ON, Canada) and Detection Technology Plc (Oulu, Finland): Focused on sensor innovation (CMOS/IGZO) and product diversification into industrial inspection niches.
- Rayence Co., Ltd. and Vieworks Co., Ltd. (South Korea): Agile manufacturers that compete on rapid design cycles and cost‑effective manufacturing for both medical and industrial applications.
- Carestream Health, Inc. (Rochester, NY, USA): A legacy player with a broad detector family and recent regulatory uplifts that reinforce its competitive relevance.
Selected recent developments we track closely (illustrative): Carestream Health received a large wireless detector 510(k) clearance in December 2025; InnoCare Optoelectronics obtained 510(k) clearance for stationary systems in mid‑2025; and Detection Technology expanded IGZO/a‑Si portfolios with new product introductions in late 2025. These events alter product availability, procurement cycles and competitive positioning in near‑term tenders.
How to apply the research to 2026 strategic decisions
- Capital allocation: Use our scenario matrices to stress‑test capex for new detector lines versus licensing/partnership options. The report quantifies payback windows under conservative and upside demand cases.
- Product roadmap prioritization: Map planned sensor upgrades to forecasted replacement waves. Prioritize modularity and backwards compatibility where hospital upgrade cycles drive purchase windows.
- M&A and alliance screening: The concentration metrics identify realistic consolidation targets and partnership candidates that can deliver market access or technology acceleration without paying premium multiples for scale alone.
- Regulatory and clinical evidence planning: Coordinate clinical trials, 510(k) strategies and reimbursement dossiers to align launch timing with the forecasted adoption inflection points highlighted in the report.
- Sales and procurement negotiation: Leverage our vendor benchmarking and TCO templates to renegotiate service contracts, structured payments and upgrade rights tied to product roadmaps.
What we leave out here — and why you’ll need the full report
This introduction intentionally omits the granular regional, application and type‑level splits, specific vendor market shares and detailed price trajectories. Those elements are the core of our proprietary models and underpin the tactical recommendations and playbooks. If your team needs executable forecasts (including unit volumes by detector class, regional roll‑out pacing, per‑segment ASP paths, or a downloadable vendor scorecard and negotiation playbook), the full report contains the calibrated datasets and the Excel model that drive these outputs.
Bottom line
For boards, strategy teams and investors preparing decisive moves in 2026, our X‑ray Flat Panel Detector Market study provides a transaction‑grade synthesis of market size, growth vectors and competitive dynamics. With a forecasted mid‑single‑digit CAGR to 2032 and a market that is both concentrated and technologically dynamic, the right combination of product focus, regulatory timing and selective partnerships will determine winners. PW Consulting’s full report translates those insights into step‑by‑step execution tools — the difference between a plausible strategy and one that secures leadership in the next growth phase.
For detailed analysis of this topic, please visit the official page: X-ray Flat Panel Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vacuum Aluminum Plating Machine Market to reach USD 547.4M by 2032 at 8.9% CAGR
By pmarketresearch, 2026-07-09
Vacuum Aluminum Plating Machine Market — Strategic Outlook for 2026 Decision‑Makers
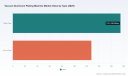
PW Consulting’s latest market study on Vacuum Aluminum Plating Machines provides a strategic, decision‑ready view for executives planning capital allocation, technology choices, and go‑to‑market moves in 2026. The market has moved from a niche industrial capability into a mainstream finishing technology: total industry revenues expanded from roughly USD 180 million in 2020 to about USD 303 million in 2025, and our forecast shows persistent expansion through the 2026–2032 horizon, reaching an estimated USD 547 million by 2032 at a compounded annual growth rate (CAGR) of 8.9%. These topline dynamics create both opportunity and urgency for manufacturers, component suppliers, integrators, and investors.
Vacuum Aluminum Plating Machine Market
Why this study matters for 2026 decisions
-
Timing of capital deployment — With the market on an 8.9% growth path and regulatory timelines accelerating in key geographies, 2026 is a window in which timely equipment upgrades translate directly into avoided compliance risk and first‑mover margin advantage. Our analysis converts market growth and regulation timelines into explicit investment priorities and payback horizons for CFOs and plant managers.
Vacuum Aluminum Plating Machine Market -
Technology selection under cost and compliance pressures — Vacuum aluminum metallizing sits at the intersection of process engineering, environmental regulation, and product aesthetics. The report synthesizes comparative technology tradeoffs (e.g., thermal evaporation, magnetron sputtering, cathodic arc, PVD enhancements) into practical selection matrices keyed to throughput, finish quality, energy profile, and emissions compliance.
Vacuum Aluminum Plating Machine Market -
Supplier strategy and service economics — Given the market’s moderate concentration (the top three players account for a majority share and the top five substantially more), procurement teams must balance scale advantages (reliability, installed base, financing) against the cost and innovation momentum of regional vendors. Our competitor scorecards and procurement playbook help companies negotiate T&Cs, service SLAs, and spare parts strategies that materially affect lifecycle cost.
-
Regulatory and transition risk — Recent changes in air quality and solvent‑use regulations (notably updates to the EPA Clean Air Act frameworks, EU VOC directives, and region‑specific standards such as China’s national emission rules and CARB requirements) are accelerating migration away from wet chemical plating toward vacuum technologies. The study lays out compliance pathways that minimize shutdown risk and provide timelines to meet escalating enforcement.
What the report delivers — operationally focused content
-
Market sizing and trend analysis: a transparent, audit‑ready topline and historical series (2020–2025) with modelled forecasts to 2032. The forecast embeds demand drivers such as packaging automation, electronics finishing, and automotive lighting trends, and tests scenarios for macro slowdown or accelerated regulation.
-
Practical CapEx & OpEx modelling: downloadable templates and scenario calculators that let you model payback for machine classes across throughput bands and automation levels, including sensitivity to raw material (metal wire) prices and labor intensity associated with loading/unloading processes.
-
Vendor benchmarking and procurement playbooks: standardized scorecards for technical fit, service coverage, lead times, financing options, after‑sales support, and total cost of ownership. These are designed to be used in RFPs and supplier workshops.
-
Regulatory compliance playbook: timelines and mitigation steps tied to jurisdictional actions so you can prioritize retrofits vs. greenfield investments and quantify the benefits of replacing wet processes with vacuum aluminum metallizing.
-
Go‑to‑market and M&A roadmaps: strategic options for incumbent OEMs, contract coaters, captive finishers, and private equity — including bolt‑on targets and capability gaps that unlock margin expansion or rapid revenue growth.
-
Risk matrices and scenario planning: operational, supply chain and policy risks with recommended contingency actions and trigger points for reassessment.
Competitive landscape — how to read vendor dynamics
The competitive field combines specialist equipment manufacturers with vertically integrated regional players. Leading Western specialists provide high‑spec sputtering and evaporation systems optimized for high‑brightness reflectors and automotive lighting, while a set of Asia‑based firms offer broad portfolios that include PVD thermal evaporation, multi‑arc coating, and roll‑to‑roll metallizing geared to plastics and films.
-
Mustang Vac (United States) — a specialist oriented to high‑brightness reflectors, automotive lighting and decorative functional coatings. Strengths include domain expertise for high‑value optical applications and deep service relationships in OEM channels.
-
Shanghai Royal Technology Inc. (China) — rapidly positioning itself with next‑generation PVD and decorative chrome/color coating equipment as alternatives to traditional electroplating. Recent 2026 product activity (catalog updates, product optimization announcements, and a Generation III high‑vacuum deposition machine targeted at forensic and premium decorative applications) signals an aggressive push into higher‑margin applications and compliance‑friendly solutions.
-
Guangdong Zhenhua, Atop Industry, Zhaoqing Kerun, Lanzhou Vacuum and HCVAC (China and regional players) — together they form a technology and price competitive cluster that supplies a wide range of evaporation, sputtering, and vacuum metalizing lines. Their strengths lie in cost competitiveness, customization for local supply chains, and integrated production lines for plastics, films and mirrors.
Strategic takeaway: buyers should view supplier choice as a multidimensional decision (technical fit, service footprint, financing, upgrade path). The market concentration metrics in our study show a moderate level of supplier dominance at the top, but meaningful capability and price competition among regional vendors — creating opportunities for selective outsourcing or dual‑sourcing strategies.
Key dynamics that will shape competitive advantage in 2026
-
Regulatory acceleration — Legislative and standards pressure is shifting demand from solvent‑based wet finishes to vacuum technologies. Companies that map their compliance roadmap to equipment procurement timelines will reduce retrofit costs and secure capacity advantages.
-
Capital intensity and financing innovation — A typical upgrade or greenfield cell attracts significant capex (industry references suggest equipment and infrastructure investments commonly range from several hundred thousand to multiple millions of USD per facility). This creates demand for vendor financing, lease models, and performance‑based contracts; buyers who negotiate such structures improve near‑term cash flow while preserving long‑term upside.
-
Labor and process automation — Aluminum metallizing retains labor‑intensive steps (metal wire handling, vacuum chamber fixtures, manual loading/unloading). Automation and modular line designs will be decisive in reducing unit labour costs and improving throughput predictability, particularly for high‑volume packaging and electronics applications.
-
Product differentiation via material science and finishes — New PVD color and chrome processes, and hybrid workflows that combine sputtering with downstream treatments, are opening premium niches where finish quality commands significant price premiums.
-
Aftermarket and service economy — Spare parts, consumables, and proactive maintenance contracts represent a persistent revenue stream. Suppliers that build robust remote monitoring and predictive maintenance capabilities will capture higher lifecycle margins and create switching costs for customers.
Actionable next steps for corporate decision‑makers in 2026
-
Run a rapid CapEx prioritization exercise using our payback templates to identify which production lines to upgrade in 2026 versus 2027–2028, incorporating local regulatory deadlines.
-
Implement a supplier dual‑track RFP: engage a proven Western specialist for high‑value optical/automotive lines while soliciting competitive bids from regional OEMs for volume and cost‑sensitive lines.
-
Pursue modular automation investments to lower labor intensity in loading/unloading operations and to future‑proof lines against rising labour costs.
-
Negotiate performance‑linked financing with equipment vendors to preserve liquidity while meeting near‑term compliance obligations.
-
Assess M&A targets in adjacent services — spare parts distributors, remote‑monitoring platforms, and specialty consumables — to rapidly build aftermarket capabilities.
How PW Consulting helps
This introduction outlines the strategic context and operational levers that matter in 2026. The full PW Consulting report contains the granular market tables, proprietary segment models, region‑ and application‑level forecasts, supplier scorecards, and downloadable financial models you need to execute. We intentionally present the strategic insight here while reserving the full segment tables and vendor scorecards for the complete report and interactive briefing.
Contact PW Consulting for a tailored executive briefing that maps the report findings to your facility footprint, product mix, and regulatory context — or access the full study to obtain the detailed segment-level intelligence, pricing grids, and supplier negotiation templates required to act with confidence this year.
For detailed analysis of this topic, please visit the official page: Vacuum Aluminum Plating Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Caprolactone market set for USD 305.62M by 2032 (3.27% CAGR)
By pmarketresearch, 2026-07-09
Caprolactone Market — 2026 Strategic Preview
Why this briefing matters for 2026 corporate decision-making
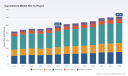
As a focused feedstock and intermediate for a growing set of specialty polymers, caprolactone sits at the intersection of sustainability-driven material substitution, specialty coatings and adhesives demand, and evolving regulatory scrutiny. PW Consulting’s forthcoming full Caprolactone Market study (base year 2025, historical 2020–2025, forecast 2026–2032) frames these dynamics against an empirical market trajectory: the sector expanded from roughly USD 209 million in 2020 to about USD 244 million in 2025, and is projected to reach roughly USD 257 million in 2026 on the path to an estimated USD 306 million by 2032. The forecast period carries a compound annual growth rate of approximately 3.27% — enough steady expansion to justify near-term commercial action but not so rapid as to remove the need for disciplined capital and partner selection.
Caprolactone Market
Headline market dynamics
-
Demand composition is diversifying. End-markets such as biodegradable polymers, polycaprolactone (PCL) polyols used in polyurethanes, thermoplastic elastomers (TPU) and specialty adhesives and coatings continue to anchor demand. This mix creates differentiated margin pools and product-specification requirements that favor focused technical-commercial strategies over one-size-fits-all supply plays.
Caprolactone Market -
Feedstock and process constraints matter. Technically, caprolactone production remains linked to cyclohexanone-based chemistries (notably via hydrogen peroxide oxidation routes). Feedstock availability, energy intensity and process yields therefore translate directly into unit economics and carbon intensity — critical inputs for sustainability claims and customer procurement decisions.
Caprolactone Market -
Regulatory and registration barriers change competitive access. Recent regulatory actions and registration achievements — for example companies securing REACH and K-REACH registrations — alter which suppliers are qualified for certain industrial customers and geographies. Compliance timelines and dossier quality are now de facto market access levers.
-
Infrastructure upgrades are uneven. Evidence of strategic debottlenecking and selective capacity expansion among established players points to a market that will tighten in pockets and loosen in others. These micro-imbalances create short-term arbitrage opportunities for nimble traders and long-term capacity signalling for investors.
-
Commercial models are shifting toward distribution and channel specialization. Recent exclusive-distribution arrangements and localized sales agency expansions demonstrate a move to optimize route-to-market for niche applications such as bioplastics and specialty coatings.
Strategic implications for 2026 decisions
-
Capacity and capital allocation — calibrate investment to realistic demand growth. With an overall market growing at low-single digits, greenfield builds should be anchored to secured off-take or integrated feedstock access. Consider smaller, modular expansions or debottlenecking projects where lead times and capital intensity are lower than full new plants.
-
M&A and portfolio optimization — target capability, not only volume. Acquisitions that bring regulatory registrations, application-specific know-how (e.g., pharmaceutical-grade, PCL polyols formulation expertise), or complementary intermediates will create outsized value versus scale-only deals.
-
Commercial and channel strategy — prioritize application-led go-to-market plays. Distribution partnerships and localized sales desks can accelerate penetration into high-margin niches such as biodegradable polymer supply chains and specialty coatings, while direct sales remain advantageous where technical support and regulatory documentation are critical.
-
Supply chain resilience — lock feedstock optionality. Given the underlying chemistry linkage to cyclohexanone derivatives, securing diversified feedstock contracts, or integrated upstream agreements, reduces exposure to input-price shocks and regulatory-driven disruptions.
-
Pricing and contracting — move from spot exposure to hybrid models. The market’s steady growth profile favors contract structures that blend index-linked short-term volumes with fixed-price or take-or-pay elements for strategic accounts, maintaining flexibility while underpinning utilization.
-
Regulatory and product stewardship — prioritize registrations and dossier quality. Investment in regulatory science (to support REACH/K-REACH or other jurisdictional dossiers) is a market access enabler; companies with strong regulatory footprints command preferential placement in qualified supplier lists.
-
R&D and sustainability — focus on low-carbon pathways and circular feedstocks. Material buyers increasingly value lifecycle assessments and lower carbon intensity. R&D that reduces process energy intensity, enables bio-based feedstocks, or improves recyclability will enhance commercial differentiation.
Competitive landscape: what recent moves signal
The supplier map remains led by integrated chemical companies, specialty producers and regional manufacturers that have invested in both process know-how and market-facing capabilities.
-
Ingevity Corporation — an established global brand with a focused caprolactone product family and a clear channel approach. Recent activity such as appointing an exclusive distributor in North America for bioplastics applications and sustained trade-show engagement signals a go-to-market acceleration strategy. The announced consideration to divest related polymer technology assets introduces an M&A vector for potential entrants or consolidation-minded incumbents.
-
Hunan Juren Chemical — a regionally aggressive producer with capacity expansions and regulatory registrations that improve international access. Its business development activity in coating shows and new sales agencies highlight a push from manufacturing scale toward global commercialization.
-
Merck’s Sigma-Aldrich — plays to specialty and research applications, providing high-purity material to formulation and R&D customers; an attractive channel for early-stage product developers and small-scale specialty formulators.
-
BASF, Daicel, Solvay, Perstorp — incumbents with integrated portfolios or targeted debottlenecking programs. Their actions (for example operational debottlenecking) point to selective capacity optimization rather than broad new-builds. These suppliers are likely to defend premium applications and regulatory-sensitive accounts.
What the PW Consulting full report delivers (practical components)
-
Quantified market trajectory and scenario models — validated historical series (2020–2025), baseline and alternative scenarios for 2026–2032 with sensitivity to feedstock cost, regulatory friction and adoption rates in biodegradable polymer segments.
-
Demand-supply overlays and short-term timing maps — pinpointing where and when pockets of under/over-supply will emerge so buyers and sellers can time contracts and investments.
-
Feedstock cost model and carbon-intensity toolkit — unit-cost breakdowns, emissions drivers and pathway options for decarbonization investments.
-
Regulatory risk matrix and market-access checklist — an actionable guide to prioritize registrations, dossier gaps and timelines for target markets.
-
Company dossiers and deal tracker — concise commercial and technical profiles of active suppliers, recent strategic moves, and a running log of distribution, capacity and M&A developments.
-
Investment appraisal and negotiation playbooks — capex screening templates, payback sensitivity tables, and sample negotiation terms for hybrid supply contracts.
90–360 day action plan for executives
-
90 days — Rapid risk scan: validate feedstock exposure, assess critical customer contracts, and initiate a regulatory-gap review for key markets.
-
180 days — Secure optionality: negotiate hybrid supply contracts, pilot local distribution partnerships in priority markets, and test small-scale debottlenecking or tolling arrangements to boost utilization.
-
360 days — Make the strategic call: progress M&A diligence on targets that provide regulatory access or application know-how, commit to capex projects where off-take is secured, and scale sustainability investments that support premium pricing.
Closing perspective: why read the full study
This preview provides the strategic signposts your executive team needs to prioritize near-term actions in 2026. The full PW Consulting Caprolactone Market report converts these signposts into executable intelligence: validated historical data, scenario-driven forecasts, supplier capability maps and commercial playbooks. If your 2026 plans include capacity commitments, regional market entry, supply-chain redesign, or M&A, the full report will materially shorten your decision cycle and reduce execution risk.
For executives evaluating tactical moves in a slowly expanding but technically nuanced market, the right combination of regulatory foresight, feedstock management and selective commercial partnerships will differentiate winners from the rest. PW Consulting’s comprehensive dataset and strategic tools are designed to do exactly that — equipping you to act with conviction in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Caprolactone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pharma-Grade Sodium Chloride Market to Reach USD 630M by 2032, 5.6% CAGR (PW Consulting)
By pmarketresearch, 2026-07-09
Pharmaceutical Grade Sodium Chloride Market: Strategic Primer for 2026 Decision-Makers
As healthcare systems normalize post‑pandemic and manufacturers recalibrate supply chains, pharmaceutical grade sodium chloride has re‑emerged as a quietly critical commodity underpinning therapies, diagnostics and life‑saving procedures. This primer synthesizes the key market dynamics from PW Consulting’s new study (base year 2025) and frames the concrete strategic choices executives must make in 2026. It demonstrates the analytical depth available in the full report while intentionally withholding detailed sub‑segment tables and regional breakouts to preserve the value of the underlying intelligence.
Pharmaceutical Grade Sodium Chloride Market
Market trajectory at a glance
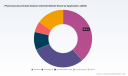
The market for pharmaceutical grade sodium chloride has expanded steadily through the historical window (2020–2025), moving from an estimated USD 470.0 Million in 2020 to USD 525.0 Million in the base year 2025. PW Consulting’s forecast for 2026–2032 models a compound annual growth rate (CAGR) of 5.6%, projecting continued expansion to an estimated USD 630.0 Million by 2032. This secular growth is underpinned by rising procedural volumes in mature health systems, expanding dialysis and injectable drug markets in growth regions, and an elevated emphasis on pharmaceutical‑grade raw materials driven by regulatory scrutiny and patient safety demands.
Pharmaceutical Grade Sodium Chloride Market
Why this matters for 2026 strategic planning
-
Supply resilience is no longer optional. The 5.6% forecast CAGR implies meaningful incremental demand that will collide with constrained processing capacity and quality‑assured supply chains. Firms that secure validated, multi‑sourced supply lines and invest in buffer inventories will avoid margin‑eroding disruptions.
Pharmaceutical Grade Sodium Chloride Market -
Quality and compliance are premium drivers. Regulatory expectations for pharmaceutical excipients and APIs are tightening. Manufacturers and contract buyers must architect traceable processes, third‑party audit readiness and documentation ecosystems that differentiate their products in tender processes.
-
Commercial negotiations will hinge on value‑added services. Buyers are increasingly purchasing “assurance” — validated supply, chain transparency, and packaging/sterilization options — not simply commodity salt. Suppliers that bundle technical support, certification, and logistics will command better economic terms.
-
Medium‑term investment choices (2026–2028) are pivotal. Decisions on capacity additions, greenfield vs brownfield projects, and automation will determine market positioning for the majority of the forecast period. PW Consulting’s scenario models show that early movers who calibrate capacity to projected demand corridors capture disproportionate share with limited price concessions.
Data‑driven implications for different business functions
-
Procurement: Shift from single‑source contracts to a tiered, qualification‑based supplier portfolio. Introduce contractual KPIs for lead times, batch release, and recall response, and price mechanisms that reflect service components.
-
Manufacturing & Quality: Prioritize investments in analytical capacity (impurity profiling, particulate monitoring) and batch release automation. Prepare for increased regulatory audits and expand documentation control to support cross‑border distribution.
-
Commercial: Reframe value propositions — sell risk mitigation and compliance as much as volume. Tender strategies should weigh lower unit costs against supplier resilience and service guarantees.
-
M&A & Corporate Development: The market’s moderate concentration profile creates opportunities for bolt‑on acquisitions that expand geographic coverage, technical capabilities, or API credentials.
Report highlights — what the full study delivers (practical, deal‑ready outputs)
-
Demand forecasting and scenario planning for 2026–2032 with sensitivity analyses across macro, regulatory and clinical adoption levers.
-
Detailed supplier assessment framework and benchmarking templates to expedite vendor qualification and risk scoring.
-
Commercial playbooks tailored to buyers and sellers: tender construction, price indexation clauses, and logistics optimization strategies.
-
Capex decision support: cost‑benefit models for capacity expansion, including break‑even timelines under conservative and aggressive demand scenarios.
-
Regulatory & quality readiness checklist aligned to FDA, EMA and major emerging market authorities, enabling faster market entry and fewer audits.
-
Consumer safety and sustainability pathway: roadmaps to reduce carbon intensity of salt production, water management best practices, and end‑to‑end traceability blueprints.
Competitive landscape — contours and strategic moves
The pharmaceutical grade sodium chloride market remains fragmented by design: a mix of global chemicals companies, regional salt specialists and life sciences suppliers. Aggregate concentration metrics indicate that leading groups do not overwhelmingly dominate — a structural feature that preserves negotiation leverage for well‑organized buyers and creates acquisition openings for strategic consolidators.
-
K+S Aktiengesellschaft (Germany): A vertically integrated player with deep experience in mining and processing. Their strengths are consistent raw material access and scale in bulk operations. Strategic focus for 2026 should be on converting industrial scale into pharma‑grade throughput via enhanced purification lines and pharmaceutical QA systems.
-
Nouryon (Netherlands): A specialty chemicals incumbent with global distribution and technical service capabilities. Nouryon’s advantage lies in formulation know‑how and regulatory familiarity — assets that facilitate partnerships with injectable and dialysis solution manufacturers.
-
Tata Chemicals Ltd. (India): A low‑cost producer with regional reach and experience across food and industrial sectors. For 2026, opportunities include upgrading facilities to meet pharma GMP, and leveraging domestic contract manufacturing growth.
-
Dominion Salt Ltd. (Canada): A producer whose market position is strengthened by regional logistics and stable feedstock. Their strategic play is to offer near‑market supply resilience and to target adjacent life‑science customers requiring tight lead times.
-
Cargill (Salt Business, USA): A global CPG and ingredient giant with strong customer relationships across healthcare and nutrition. Cargill’s distribution network and quality systems enable it to be a preferred supplier for multinational pharmaceutical manufacturers.
-
Salinen Austria AG & Sudsalz GmbH (Austria & Germany): European salt specialists with longstanding production assets. Their niche is high‑purity crystalline salt and regional regulatory know‑how — attractive to European pharma customers prioritizing short, controlled supply chains.
-
Cheetham Salt (Australia) & Compass Minerals (USA): Producers with logistics and bulk supply advantages. Their strategic differentiation rests on export capabilities and the ability to serve both industrial and pharma verticals by dedicating GMP lines.
-
Swiss Saltworks: A smaller, specialty supplier able to offer tight traceability and tailored packaging solutions for sensitive applications.
-
Merck KGaA & Spectrum Chemical (Germany & USA): Life‑science oriented suppliers that bridge commodity supply and application support. They possess distribution channels into clinical and research labs, making them credible partners for high‑margin pharma uses.
-
Hubei Xingfa Chemicals Group (China): A high‑volume producer with strong manufacturing scale. Their growth vector is serving local API and contract manufacturing hubs while investing selectively in GMP upgrades for export markets.
Across these players, three strategic fault lines define competition in 2026: (1) quality and compliance versus cost leadership, (2) global scale and distribution versus regional responsiveness, and (3) sustainable production credentials as a differentiator for sophisticated buyers.
Recommended strategic moves for 2026
-
For suppliers: Prioritize certification roadmaps (GMP, ISO and client‑specific standards), modularize capacity to support both large‑volume contracts and high‑margin small‑batch production, and develop transparent chain‑of‑custody reporting to command premium pricing.
-
For buyers: Implement multi‑tier sourcing with contractual service level metrics, invest in supplier development programs to uplift capability in strategic regions, and adopt hedging or collaborative inventory models to smooth price and availability volatility.
-
For investors/M&A teams: Target regional leaders with strong quality credentials or smaller specialists with proprietary purification technologies that can be scaled through capital and distribution assets.
-
For policy and sustainability officers: Begin capital projects and supplier dialogues that reduce freshwater usage and energy intensity — both regulatory risk and buyer preference are converging on environmental performance.
Methodology & confidence intervals
PW Consulting’s analysis uses a bottoms‑up synthesis of historical consumption (2020–2025), industry audit trails, company disclosures, and proprietary channel checks. The base year is 2025 (USD, revenue unit: Million). Forecasts for 2026–2032 reflect a central scenario at a 5.6% CAGR with alternate upside and downside pathways modeled for policy shifts, major capacity additions, or abrupt clinical demand changes. Where the market shows fragmentation, concentration ratios were computed to assess competitive intensity and acquisition potential.
Conclusion — next steps for executives
Pharmaceutical grade sodium chloride presents a classic strategic choice: treat it as a routine commodity or recognize it as a mission‑critical input whose availability, quality and provenance materially affect product safety, regulatory compliance and economics. PW Consulting’s full report transforms that choice into operationally actionable plans — detailed supplier scorecards, capex calculators, and regulatory readiness templates that executives can deploy immediately. The executive summary here is a preview of the decision‑grade intelligence behind the paywall; for the granular regional, application and company segment data that will shape contracting and investment rounds in 2026, consult the full study.
For detailed analysis of this topic, please visit the official page: Pharmaceutical Grade Sodium Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blood Collection Tubes Market to Reach USD 344.8 Million by 2032 at 7.2% CAGR
By pmarketresearch, 2026-07-09
Blood Collection Tubes Market — Strategic Imperatives for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present the executive introduction to our latest Blood Collection Tubes Market study. This briefing synthesizes the market’s recent evolution, regulatory and supply dynamics, and the competitive forces that will shape strategic choices in 2026. The full report contains the granular segment-level forecasts, company scorecards, and executable playbooks that corporate leadership teams will need; here we highlight the high‑value insights while reserving the detailed tables and proprietary models for subscribers.
Blood Collection Tubes Market
Market Pulse — What the numbers tell you
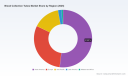
Between 2020 and 2025 the global Blood Collection Tubes market recorded steady expansion, rising from approximately USD 163.2 Million in 2020 to USD 215.0 Million in the base year 2025. Under our central forecast, the market continues on an upward trajectory through the 2026–2032 horizon, with a compound annual growth rate (CAGR) of 7.2% that lifts the market toward the high hundreds of millions by the horizon year. This combination of resilient historic growth and a mid‑single‑digit-plus CAGR signals a market that is both enduring and receptive to targeted investment and innovation.
Blood Collection Tubes Market
Two macro takeaways are immediate for executives: (1) this is a growth market with predictable structural drivers — aging populations, expanded diagnostic throughput, and diversification of sample types — and (2) growth is not uniform across product forms, applications, or channels. That unevenness creates concentrated pockets of margin expansion and, conversely, nodes of regulatory and supply risk that merit active management.
Blood Collection Tubes Market
Why this report matters to decisions you will make in 2026
- Precision Opportunity Sizing. Our report translates headline growth into actionable, time‑phased opportunity windows. Whether your objective is to secure share in clinical diagnostics, to expand into therapeutic monitoring, or to pursue OEM supply agreements, you must allocate capex and commercial bandwidth to pockets of above‑average return. The forecast and scenario modules in the full study allow you to stress‑test investment timing and scale under alternate policy and pandemic recovery scenarios.
- Regulatory and Quality Risk Management. Recent enforcement actions and recalls have amplified the business impact of quality systems and supplier governance. Our analysis quantifies the financial and operational consequences of regulatory events and outlines remediation playbooks — from design controls and supplier audits to 510(k) pathway strategy.
- Supply‑chain resilience and sourcing strategy. The report maps raw‑material and outsourced manufacturing risk by node (e.g., glass vs. plastic tubes, additive chemistries, cap technologies). For 2026, management teams must weigh near‑shoring, dual sourcing, or vertical integration against cost efficiency. We provide a prioritized matrix of supplier contingencies and expected cost impacts.
- Competitive positioning and M&A prioritization. A market with mid‑single‑digit CAGR and modest top‑line concentration presents attractive acquisition and partnership opportunities. We identify the capability clusters (preanalytics, safety‑engineered systems, capillary solutions) where M&A or licensing can accelerate market entry or margin expansion, and we provide valuation frameworks keyed to market multiples and integration risk.
What the report delivers — practical, executable outputs
- Comprehensive market model (2020–2032) with base‑case and alternate scenarios, delivered in an editable Excel workbook for rapid corporate planning.
- Segmented demand forecasts by type, application, and geography (note: detailed sub‑segment tables are available in the full report).
- Supplier heat maps, including manufacturing footprint, QC maturity, and single‑sourcing exposures.
- Regulatory risk register and a prioritized remediation playbook including 510(k) strategy, labeling control, and EU MDR alignment.
- Competitive benchmarking and strategic profiles with go‑to‑market analysis for major incumbents and fast‑growing challengers.
- Commercial playbooks: pricing levers, tender strategies, hospital system engagement, and distribution model optimization.
- M&A and partnership scorecards: deal rationale, synergies, and integration risk assessments tailored to strategic buyers and financial sponsors.
Competitive Landscape — who matters and why
The blood collection tube market remains characterized by a set of well‑established global players alongside a broad field of regional and niche manufacturers. Aggregate concentration metrics indicate a dispersed competitive structure: the top three and five players hold a minority share of the market, validating the presence of meaningful regional and product‑level fragmentation. That fragmentation both creates room for new entrants and raises the bar for scale players that must manage complexity across product variants and regulatory jurisdictions.
- Becton, Dickinson and Company (BD) — As the inventor of the Vacutainer® concept, BD retains a leadership position anchored in brand recognition, broad product breadth, and a heavy emphasis on sample quality and analytical consistency. Strategic implications: BD’s scale and established clinical relationships make it a reference partner for diagnostics OEMs and hospital networks, but also a target for differentiation by niche players offering specialized preanalytic solutions.
- Greiner Bio‑One — Known for the VACUETTE® line and a strong preanalytics focus, Greiner’s strengths lie in separator technologies and safety models. Recent recall activity in North America (labeling/gelling execution) underscores how manufacturing control and change management can materially affect market access. For 2026 strategies, companies must assess counterparty quality processes before forming long‑term supply deals with such manufacturers.
- Terumo Corporation — With deep roots in Asia and a global distribution footprint, Terumo is positioned to capture growth where diagnostic expansion is most rapid. Its playbook emphasizes high‑quality materials and chemistry, making it a logical partner for regional distributors and point‑of‑care initiatives.
- Sarstedt — The S‑Monovette® system and an emphasis on flexible collection formats give Sarstedt an appealing value proposition for clinical labs seeking adaptability. Its competitive thread is operational flexibility rather than scale.
These incumbent profiles are augmented in the full report with operational KPIs, profitability proxies, and scenario tests that show how recall events, regulatory enforcement, or rapid raw‑material price swings can re‑rank competitive advantage.
Regulatory dynamics and recent enforcement — immediate action items
Regulators have made enforcement visible and consequential. In 2025–2026 there were multiple notable enforcement actions: a May 2025 FDA warning letter that triggered an import alert for a capillary tube supplier and later Class 2 recalls tied to labeling and supplier management breakdowns. These events bring two operational imperatives to the fore:
- Rigorous change control and labeling governance. Labeling errors and gel omission events can trigger recalls that inflict reputational and financial damage — and can close market access to key geographies.
- Supplier oversight and corrective action rigor. FDA citations related to supplier management illustrate how downstream incidents can reverberate through the supply chain; buyer companies must audit and strengthen supplier QC and CAPA mechanisms.
On the product side, the requirement for 510(k) clearance (FDA product code JKA for vacuum tubes with anticoagulant) remains a gating factor for US market access and shapes product development timelines. The report breaks down expected regulatory timelines and submission strategies so that your 2026 product roadmaps align with clearance and reimbursement windows.
Strategic playbook for 2026 — prioritized moves
- Invest in QC and regulatory capability: strengthen design controls, supplier audits, and MDR/510(k) readiness to de‑risk market access and reduce recall probability.
- Targeted product differentiation: prioritize preanalytic innovation (e.g., separator chemistry, hemolysis reduction, safety caps) that yields clinical value and margin premium.
- Sourcing resilience: implement dual‑sourcing and inventory buffers for critical inputs (glass, specific polymer batches, separator gels), and evaluate selective near‑shoring for mission‑critical SKUs.
- Commercial focus: refine tender and hospital engagement playbooks; use data to demonstrate total‑cost‑of‑ownership advantages (sample stability, fewer redraws, workflow savings).
- M&A and partnerships: prioritize bolt‑on acquisitions that add preanalytics capabilities or distribution reach, and structure earnouts around regulatory and quality milestones to mitigate integration risk.
Closing — why PW Consulting’s study is a 2026 must‑have
For executive teams deciding where to allocate capital, where to compete, and how to operationalize risk controls in 2026, our Blood Collection Tubes Market study provides both the strategic line of sight and the operational playbooks required to move from intent to execution. The market’s growth profile, combined with observable regulatory friction and low top‑line concentration, favors disciplined, well‑timed moves by companies that can marry quality assurance with focused innovation and supply resilience.
To access the full dataset, the proprietary Excel model, and the company‑level scorecards that underpin these recommendations, please visit the report page on our website. The summary here is deliberately high‑impact and directional; the full study contains the granular forecasts, regional and application breakdowns, and executable annexes you will need to operationalize your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Blood Collection Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com