

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Caprolactone market set for USD 305.62M by 2032 (3.27% CAGR)

Caprolactone Market — 2026 Strategic Preview
Why this briefing matters for 2026 corporate decision-making
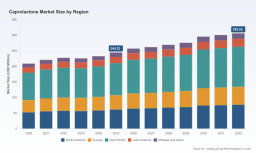
As a focused feedstock and intermediate for a growing set of specialty polymers, caprolactone sits at the intersection of sustainability-driven material substitution, specialty coatings and adhesives demand, and evolving regulatory scrutiny. PW Consulting’s forthcoming full Caprolactone Market study (base year 2025, historical 2020–2025, forecast 2026–2032) frames these dynamics against an empirical market trajectory: the sector expanded from roughly USD 209 million in 2020 to about USD 244 million in 2025, and is projected to reach roughly USD 257 million in 2026 on the path to an estimated USD 306 million by 2032. The forecast period carries a compound annual growth rate of approximately 3.27% — enough steady expansion to justify near-term commercial action but not so rapid as to remove the need for disciplined capital and partner selection.
Caprolactone Market
Headline market dynamics
-
Demand composition is diversifying. End-markets such as biodegradable polymers, polycaprolactone (PCL) polyols used in polyurethanes, thermoplastic elastomers (TPU) and specialty adhesives and coatings continue to anchor demand. This mix creates differentiated margin pools and product-specification requirements that favor focused technical-commercial strategies over one-size-fits-all supply plays.
Caprolactone Market -
Feedstock and process constraints matter. Technically, caprolactone production remains linked to cyclohexanone-based chemistries (notably via hydrogen peroxide oxidation routes). Feedstock availability, energy intensity and process yields therefore translate directly into unit economics and carbon intensity — critical inputs for sustainability claims and customer procurement decisions.
Caprolactone Market -
Regulatory and registration barriers change competitive access. Recent regulatory actions and registration achievements — for example companies securing REACH and K-REACH registrations — alter which suppliers are qualified for certain industrial customers and geographies. Compliance timelines and dossier quality are now de facto market access levers.
-
Infrastructure upgrades are uneven. Evidence of strategic debottlenecking and selective capacity expansion among established players points to a market that will tighten in pockets and loosen in others. These micro-imbalances create short-term arbitrage opportunities for nimble traders and long-term capacity signalling for investors.
-
Commercial models are shifting toward distribution and channel specialization. Recent exclusive-distribution arrangements and localized sales agency expansions demonstrate a move to optimize route-to-market for niche applications such as bioplastics and specialty coatings.
Strategic implications for 2026 decisions
-
Capacity and capital allocation — calibrate investment to realistic demand growth. With an overall market growing at low-single digits, greenfield builds should be anchored to secured off-take or integrated feedstock access. Consider smaller, modular expansions or debottlenecking projects where lead times and capital intensity are lower than full new plants.
-
M&A and portfolio optimization — target capability, not only volume. Acquisitions that bring regulatory registrations, application-specific know-how (e.g., pharmaceutical-grade, PCL polyols formulation expertise), or complementary intermediates will create outsized value versus scale-only deals.
-
Commercial and channel strategy — prioritize application-led go-to-market plays. Distribution partnerships and localized sales desks can accelerate penetration into high-margin niches such as biodegradable polymer supply chains and specialty coatings, while direct sales remain advantageous where technical support and regulatory documentation are critical.
-
Supply chain resilience — lock feedstock optionality. Given the underlying chemistry linkage to cyclohexanone derivatives, securing diversified feedstock contracts, or integrated upstream agreements, reduces exposure to input-price shocks and regulatory-driven disruptions.
-
Pricing and contracting — move from spot exposure to hybrid models. The market’s steady growth profile favors contract structures that blend index-linked short-term volumes with fixed-price or take-or-pay elements for strategic accounts, maintaining flexibility while underpinning utilization.
-
Regulatory and product stewardship — prioritize registrations and dossier quality. Investment in regulatory science (to support REACH/K-REACH or other jurisdictional dossiers) is a market access enabler; companies with strong regulatory footprints command preferential placement in qualified supplier lists.
-
R&D and sustainability — focus on low-carbon pathways and circular feedstocks. Material buyers increasingly value lifecycle assessments and lower carbon intensity. R&D that reduces process energy intensity, enables bio-based feedstocks, or improves recyclability will enhance commercial differentiation.
Competitive landscape: what recent moves signal
The supplier map remains led by integrated chemical companies, specialty producers and regional manufacturers that have invested in both process know-how and market-facing capabilities.
-
Ingevity Corporation — an established global brand with a focused caprolactone product family and a clear channel approach. Recent activity such as appointing an exclusive distributor in North America for bioplastics applications and sustained trade-show engagement signals a go-to-market acceleration strategy. The announced consideration to divest related polymer technology assets introduces an M&A vector for potential entrants or consolidation-minded incumbents.
-
Hunan Juren Chemical — a regionally aggressive producer with capacity expansions and regulatory registrations that improve international access. Its business development activity in coating shows and new sales agencies highlight a push from manufacturing scale toward global commercialization.
-
Merck’s Sigma-Aldrich — plays to specialty and research applications, providing high-purity material to formulation and R&D customers; an attractive channel for early-stage product developers and small-scale specialty formulators.
-
BASF, Daicel, Solvay, Perstorp — incumbents with integrated portfolios or targeted debottlenecking programs. Their actions (for example operational debottlenecking) point to selective capacity optimization rather than broad new-builds. These suppliers are likely to defend premium applications and regulatory-sensitive accounts.
What the PW Consulting full report delivers (practical components)
-
Quantified market trajectory and scenario models — validated historical series (2020–2025), baseline and alternative scenarios for 2026–2032 with sensitivity to feedstock cost, regulatory friction and adoption rates in biodegradable polymer segments.
-
Demand-supply overlays and short-term timing maps — pinpointing where and when pockets of under/over-supply will emerge so buyers and sellers can time contracts and investments.
-
Feedstock cost model and carbon-intensity toolkit — unit-cost breakdowns, emissions drivers and pathway options for decarbonization investments.
-
Regulatory risk matrix and market-access checklist — an actionable guide to prioritize registrations, dossier gaps and timelines for target markets.
-
Company dossiers and deal tracker — concise commercial and technical profiles of active suppliers, recent strategic moves, and a running log of distribution, capacity and M&A developments.
-
Investment appraisal and negotiation playbooks — capex screening templates, payback sensitivity tables, and sample negotiation terms for hybrid supply contracts.
90–360 day action plan for executives
-
90 days — Rapid risk scan: validate feedstock exposure, assess critical customer contracts, and initiate a regulatory-gap review for key markets.
-
180 days — Secure optionality: negotiate hybrid supply contracts, pilot local distribution partnerships in priority markets, and test small-scale debottlenecking or tolling arrangements to boost utilization.
-
360 days — Make the strategic call: progress M&A diligence on targets that provide regulatory access or application know-how, commit to capex projects where off-take is secured, and scale sustainability investments that support premium pricing.
Closing perspective: why read the full study
This preview provides the strategic signposts your executive team needs to prioritize near-term actions in 2026. The full PW Consulting Caprolactone Market report converts these signposts into executable intelligence: validated historical data, scenario-driven forecasts, supplier capability maps and commercial playbooks. If your 2026 plans include capacity commitments, regional market entry, supply-chain redesign, or M&A, the full report will materially shorten your decision cycle and reduce execution risk.
For executives evaluating tactical moves in a slowly expanding but technically nuanced market, the right combination of regulatory foresight, feedstock management and selective commercial partnerships will differentiate winners from the rest. PW Consulting’s comprehensive dataset and strategic tools are designed to do exactly that — equipping you to act with conviction in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Caprolactone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com