

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Blood Collection Tubes Market to Reach USD 344.8 Million by 2032 at 7.2% CAGR

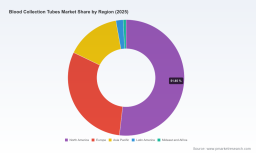
Blood Collection Tubes Market — Strategic Imperatives for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present the executive introduction to our latest Blood Collection Tubes Market study. This briefing synthesizes the market’s recent evolution, regulatory and supply dynamics, and the competitive forces that will shape strategic choices in 2026. The full report contains the granular segment-level forecasts, company scorecards, and executable playbooks that corporate leadership teams will need; here we highlight the high‑value insights while reserving the detailed tables and proprietary models for subscribers.
Blood Collection Tubes Market
Market Pulse — What the numbers tell you
Between 2020 and 2025 the global Blood Collection Tubes market recorded steady expansion, rising from approximately USD 163.2 Million in 2020 to USD 215.0 Million in the base year 2025. Under our central forecast, the market continues on an upward trajectory through the 2026–2032 horizon, with a compound annual growth rate (CAGR) of 7.2% that lifts the market toward the high hundreds of millions by the horizon year. This combination of resilient historic growth and a mid‑single‑digit-plus CAGR signals a market that is both enduring and receptive to targeted investment and innovation.
Blood Collection Tubes Market
Two macro takeaways are immediate for executives: (1) this is a growth market with predictable structural drivers — aging populations, expanded diagnostic throughput, and diversification of sample types — and (2) growth is not uniform across product forms, applications, or channels. That unevenness creates concentrated pockets of margin expansion and, conversely, nodes of regulatory and supply risk that merit active management.
Blood Collection Tubes Market
Why this report matters to decisions you will make in 2026
- Precision Opportunity Sizing. Our report translates headline growth into actionable, time‑phased opportunity windows. Whether your objective is to secure share in clinical diagnostics, to expand into therapeutic monitoring, or to pursue OEM supply agreements, you must allocate capex and commercial bandwidth to pockets of above‑average return. The forecast and scenario modules in the full study allow you to stress‑test investment timing and scale under alternate policy and pandemic recovery scenarios.
- Regulatory and Quality Risk Management. Recent enforcement actions and recalls have amplified the business impact of quality systems and supplier governance. Our analysis quantifies the financial and operational consequences of regulatory events and outlines remediation playbooks — from design controls and supplier audits to 510(k) pathway strategy.
- Supply‑chain resilience and sourcing strategy. The report maps raw‑material and outsourced manufacturing risk by node (e.g., glass vs. plastic tubes, additive chemistries, cap technologies). For 2026, management teams must weigh near‑shoring, dual sourcing, or vertical integration against cost efficiency. We provide a prioritized matrix of supplier contingencies and expected cost impacts.
- Competitive positioning and M&A prioritization. A market with mid‑single‑digit CAGR and modest top‑line concentration presents attractive acquisition and partnership opportunities. We identify the capability clusters (preanalytics, safety‑engineered systems, capillary solutions) where M&A or licensing can accelerate market entry or margin expansion, and we provide valuation frameworks keyed to market multiples and integration risk.
What the report delivers — practical, executable outputs
- Comprehensive market model (2020–2032) with base‑case and alternate scenarios, delivered in an editable Excel workbook for rapid corporate planning.
- Segmented demand forecasts by type, application, and geography (note: detailed sub‑segment tables are available in the full report).
- Supplier heat maps, including manufacturing footprint, QC maturity, and single‑sourcing exposures.
- Regulatory risk register and a prioritized remediation playbook including 510(k) strategy, labeling control, and EU MDR alignment.
- Competitive benchmarking and strategic profiles with go‑to‑market analysis for major incumbents and fast‑growing challengers.
- Commercial playbooks: pricing levers, tender strategies, hospital system engagement, and distribution model optimization.
- M&A and partnership scorecards: deal rationale, synergies, and integration risk assessments tailored to strategic buyers and financial sponsors.
Competitive Landscape — who matters and why
The blood collection tube market remains characterized by a set of well‑established global players alongside a broad field of regional and niche manufacturers. Aggregate concentration metrics indicate a dispersed competitive structure: the top three and five players hold a minority share of the market, validating the presence of meaningful regional and product‑level fragmentation. That fragmentation both creates room for new entrants and raises the bar for scale players that must manage complexity across product variants and regulatory jurisdictions.
- Becton, Dickinson and Company (BD) — As the inventor of the Vacutainer® concept, BD retains a leadership position anchored in brand recognition, broad product breadth, and a heavy emphasis on sample quality and analytical consistency. Strategic implications: BD’s scale and established clinical relationships make it a reference partner for diagnostics OEMs and hospital networks, but also a target for differentiation by niche players offering specialized preanalytic solutions.
- Greiner Bio‑One — Known for the VACUETTE® line and a strong preanalytics focus, Greiner’s strengths lie in separator technologies and safety models. Recent recall activity in North America (labeling/gelling execution) underscores how manufacturing control and change management can materially affect market access. For 2026 strategies, companies must assess counterparty quality processes before forming long‑term supply deals with such manufacturers.
- Terumo Corporation — With deep roots in Asia and a global distribution footprint, Terumo is positioned to capture growth where diagnostic expansion is most rapid. Its playbook emphasizes high‑quality materials and chemistry, making it a logical partner for regional distributors and point‑of‑care initiatives.
- Sarstedt — The S‑Monovette® system and an emphasis on flexible collection formats give Sarstedt an appealing value proposition for clinical labs seeking adaptability. Its competitive thread is operational flexibility rather than scale.
These incumbent profiles are augmented in the full report with operational KPIs, profitability proxies, and scenario tests that show how recall events, regulatory enforcement, or rapid raw‑material price swings can re‑rank competitive advantage.
Regulatory dynamics and recent enforcement — immediate action items
Regulators have made enforcement visible and consequential. In 2025–2026 there were multiple notable enforcement actions: a May 2025 FDA warning letter that triggered an import alert for a capillary tube supplier and later Class 2 recalls tied to labeling and supplier management breakdowns. These events bring two operational imperatives to the fore:
- Rigorous change control and labeling governance. Labeling errors and gel omission events can trigger recalls that inflict reputational and financial damage — and can close market access to key geographies.
- Supplier oversight and corrective action rigor. FDA citations related to supplier management illustrate how downstream incidents can reverberate through the supply chain; buyer companies must audit and strengthen supplier QC and CAPA mechanisms.
On the product side, the requirement for 510(k) clearance (FDA product code JKA for vacuum tubes with anticoagulant) remains a gating factor for US market access and shapes product development timelines. The report breaks down expected regulatory timelines and submission strategies so that your 2026 product roadmaps align with clearance and reimbursement windows.
Strategic playbook for 2026 — prioritized moves
- Invest in QC and regulatory capability: strengthen design controls, supplier audits, and MDR/510(k) readiness to de‑risk market access and reduce recall probability.
- Targeted product differentiation: prioritize preanalytic innovation (e.g., separator chemistry, hemolysis reduction, safety caps) that yields clinical value and margin premium.
- Sourcing resilience: implement dual‑sourcing and inventory buffers for critical inputs (glass, specific polymer batches, separator gels), and evaluate selective near‑shoring for mission‑critical SKUs.
- Commercial focus: refine tender and hospital engagement playbooks; use data to demonstrate total‑cost‑of‑ownership advantages (sample stability, fewer redraws, workflow savings).
- M&A and partnerships: prioritize bolt‑on acquisitions that add preanalytics capabilities or distribution reach, and structure earnouts around regulatory and quality milestones to mitigate integration risk.
Closing — why PW Consulting’s study is a 2026 must‑have
For executive teams deciding where to allocate capital, where to compete, and how to operationalize risk controls in 2026, our Blood Collection Tubes Market study provides both the strategic line of sight and the operational playbooks required to move from intent to execution. The market’s growth profile, combined with observable regulatory friction and low top‑line concentration, favors disciplined, well‑timed moves by companies that can marry quality assurance with focused innovation and supply resilience.
To access the full dataset, the proprietary Excel model, and the company‑level scorecards that underpin these recommendations, please visit the report page on our website. The summary here is deliberately high‑impact and directional; the full study contains the granular forecasts, regional and application breakdowns, and executable annexes you will need to operationalize your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Blood Collection Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com