

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Axial Fan Market Poised for 5.5% CAGR (2026–2032)

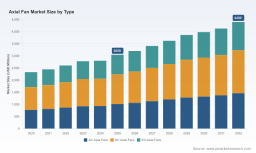
Axial Fan Market 2026: Strategic Intelligence Briefing for Executive Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise yet richly informed preview of our full Axial Fan Market research — calibrated to inform corporate strategy in 2026. Anchored on a 2025 base year and a 2026–2032 forecast horizon, the market exhibits steady expansion with a 5.5% CAGR and a projected upward trajectory through 2032. This briefing distills the factors that will most materially influence investment choices, product roadmaps, supply-chain positioning, and M&A activity next year, while preserving the granular proprietary data in the full report to which this note directs readers.
Axial Fan Market
Why this study matters for 2026 decisions
-
Regulatory inflection points are accelerating product obsolescence windows. New energy-efficiency mandates in key jurisdictions are already reshaping specification curves and procurement criteria for HVAC and cooling infrastructure.
Axial Fan Market -
Technology transitions — notably wider adoption of EC motor platforms and integrated control systems — are altering cost structures, aftermarket service models, and competitive moats.
Axial Fan Market -
Supply-chain volatility driven by tariffs on steel and aluminum, and constrained component supply (motors, bearings, electronic controls) is forcing firms to rethink sourcing, localisation, and pass-through strategies.
-
Market structure remains moderately fragmented: a meaningful share of demand is met by specialist manufacturers and regional players, while a smaller band of global vendors drive scale-based advantages in R&D, channels, and industrial OEM contracts.
-
For boards and commercial leaders, the practical question is not whether the market grows (it does), but how to capture higher-margin share and de-risk portfolios amid tightening efficiency standards and material-cost pressure.
Key dynamics shaping 2026 strategy
-
Regulatory momentum: The EU’s updated energy performance requirements (ErP 2026) and regionally stringent codes (for example, recent updates to nonresidential cooling tower efficacy standards) will force rapid iteration of product lines and qualification cycles for suppliers and systems integrators.
-
Product and systems evolution: EC (electronically commutated) motor platforms, smarter controls, and integrated thermal management solutions are becoming default options for buyers prioritising lifecycle cost over initial purchase price.
-
Commercial cooling and HVAC OEMs will prioritise modular, serviceable designs to meet both regulation and total cost of ownership thresholds demanded by large end-users.
-
Materials and trade policy: Additional duties on steel and aluminum imports impose near-term cost shocks for manufacturers relying on cross-border supply of housings and blades; mitigation options include supplier consolidation, redesign for alternative alloys, and tariff pass-through contracts with customers.
What the full report delivers (practical, execution-oriented)
-
Validated market sizing and demand scenarios across 2020–2032 with base-year granularity and three stretch-case forecasts under alternative regulatory and input-cost assumptions.
-
Segment frameworks (by product type, application, and region) that identify pockets of margin expansion and areas at risk of commoditisation — presented as actionable frameworks rather than raw tables to preserve commercial value.
-
Competitive benchmarking and capability maps for headline vendors, including technology stacks, go-to-market models, channel exposure, and product roadmaps.
-
Decision-support tools: a regulatory compliance playbook, supplier risk matrix, capex vs. opex modelling templates, and a three-tier M&A/value-capture checklist you can run against your own portfolio.
-
Commercially focused recommendations on pricing levers, after-sales monetisation, and product retirement/upgrade timelines tied to expected efficiency thresholds and buyer procurement cycles.
Competitive landscape — strategic takeaways
-
Technology leaders with EC motor expertise and integrated controls will exert disproportionate influence on specification decisions. Firms that combine high-efficiency motor platforms with precision control (for both HVAC and industrial segments) are positioned to command premium pricing and longer OEM relationships.
-
Global players continue to invest in both organic product development and inorganic consolidation to shore up manufacturing scale and broaden addressable markets. Recent corporate moves demonstrate that acquisitions remain a preferred route to accelerate capability build-out.
-
Regional and specialist manufacturers retain advantages in customised, large-format axial fan applications (cooling towers, industrial ventilation) where bespoke engineering and service depth beat product commoditisation.
-
Channel and OEM partnerships matter: vendors integrated into cooling-tower and HVAC equipment supply chains can leverage system-level savings to protect margins even as component prices fluctuate.
-
Notable market activity to watch: product launches and regulatory-compliant ranges rolling out in response to ErP timelines, acquisitions that vertically integrate motor or control capabilities into fan production, and heightened trade-show presence by innovators previewing 2026-compliant portfolios.
Brief company-positioning snapshot
-
Manufacturers with deep EC motor IP and precision-control focus are best placed to lead category refresh cycles and capture the premium segment of HVAC and rail/industrial applications.
-
Established fan specialists with strong industrial OEM relationships dominate large-form-factor applications and retrofit projects, especially where service life and custom engineering are critical.
-
Electronics-led suppliers that marry fan hardware with compact, high-efficiency drives and thermal-management components are creating integrated value propositions attractive to electronics and data-center customers.
Strategic recommendations for 2026 (prioritised)
-
Immediate compliance audit: Map current product ranges against expected jurisdictional efficiency thresholds and set a hard timeline to phase non-compliant SKUs out of key markets.
-
Portfolio stress-testing: Run a margin-impact scenario that combines tariff shocks on steel/aluminum with accelerated EC adoption — use the report’s scenario models to identify which SKUs to re-engineer, retire, or premiumise.
-
Supply-chain rebalancing: Implement a three-tier sourcing strategy (core qualified suppliers, regional dual-sourced suppliers, and contingency partners) to mitigate tariff and logistics risk without sacrificing quality or lead times.
-
Accelerate EC and controls roadmap: Prioritise development or acquisition of electronically commutated motor platforms and embedded controls that enable performance claims needed for new energy codes and service-based monetisation.
-
M&A & partnership playbook: Target bolt-ons that add control-electronics IP, finishing/assembly capacity in low-tariff jurisdictions, or established service networks in high-value segments.
-
Commercial model refresh: Move from transactional unit sales to bundled lifecycle offers (guaranteed performance + predictive maintenance) where contract terms allow for premium capture.
Executive checklist — first 90 days
-
Complete a rapid regulatory impact map for your top three addressable markets and identify immediate compliance gaps.
-
Run dealer and OEM contracts to assess pass-through clauses for input-cost increases and determine levers for renegotiation.
-
Initiate prototype trials for EC retrofits or high-efficiency models in one commercial and one industrial account to validate TCO messaging.
-
Audit your supplier base for exposure to steel/aluminum duties and identify potential low-cost regional partners or consolidation targets.
-
Scan the M&A landscape with a shortlist of targets that accelerate control-electronics capability or provide immediate geographic advantage.
Axial fan markets are transitioning from a component-driven to a systems- and service-driven industry. For executives making capex, sourcing, or M&A decisions in 2026, the winners will be those that align product roadmaps with regulatory windows, de-risk input costs through intelligent sourcing and design, and monetise post-sale services enabled by smarter controls.
PW Consulting’s full Axial Fan Market report supplies the detailed segmentation, vendor scorecards, and the quantitative models you need to operationalise these recommendations. Access to the complete dataset and executable templates is available through our report portal; the full intelligence package equips executive teams to convert the market’s steady growth and regulatory momentum into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Axial Fan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com