

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Cables Market to reach USD 357.35M by 2032 at 6.3% CAGR
By pmarketresearch, 2026-07-09
Cables Market 2026: Strategic Imperatives for Executive Decision‑Making
As companies calibrate strategies for 2026, the cables market is resurfacing as a critical enabler of energy transition, digital infrastructure and industrial automation. PW Consulting’s latest market study — built on a 2025 base year with a historical window from 2020–2025 and a forward-looking forecast to 2032 — provides the context and tools executives need to convert market momentum into profitable, durable advantage. The global market, which expanded steadily through the early 2020s and recorded notable acceleration into 2024–2025, is projected to continue growing at a mid-single-digit compound annual growth rate (CAGR) of 6.3% through the 2026–2032 forecast horizon.
Cables Market
Why this study matters for 2026 decisions
-
Timing of capex and capacity decisions: With market growth re‑accelerating post‑2024 and material costs under pressure, the report translates top‑line forecasts into investment timing guidance — where to defer, where to accelerate and where to right‑size capacity.
Cables Market -
Supply‑chain resilience and sourcing strategy: The confluence of commodity volatility and escalating trade measures makes procurement strategy a board‑level priority. This study models scenario outcomes — from tariff shocks to raw material squeezes — and quantifies the cost exposure of different sourcing strategies.
Cables Market -
Go‑to‑market and product prioritization: Energy transition, submarine/offshore projects, EV charging infrastructure, data centers and smart buildings each exert distinct demand profiles. Our research identifies which product architectures and value propositions are likely to deliver margin resilience versus volume play.
-
M&A and partnership playbook: As the sector remains relatively fragmented, disciplined M&A can deliver scale or niche superiority. The report provides screening criteria, precedent transactions and a prioritized list of capability gaps where partnership or acquisition would accelerate access to end markets.
What the report delivers — a practical playbook, not a catalog
PW Consulting’s Cables Market study is explicitly designed for executive action. It combines rigorous market sizing and forecasting with operationally relevant diagnostics and templates that decision‑makers can deploy immediately. Key deliverables include:
-
Top‑down market sizing and a 2026–2032 forecast built on validated demand drivers and scenario analysis; historical performance from 2020–2025 is included to ground assumptions.
-
Demand-driver decomposition across end markets (energy transmission, telecommunications, industrial and building electrification) with sensitivity matrices that help translate macro scenarios into revenue and margin outcomes.
-
Competitive landscape mapping and capability heatmaps to inform where to invest in product development, manufacturing scale or channel expansion.
-
Supply‑chain and raw‑material stress tests, including pass‑through modelling, hedging playbooks and alternative procurement routes to mitigate tariff and commodity shocks.
-
Commercial playbooks — pricing, contracting, and lifecycle services strategies — designed to protect margin under volatile input cost conditions.
-
M&A screening tools and integration planning templates targeted at rapid value capture in consolidation or capability‑access transactions.
Market dynamics shaping 2026 agendas
-
Energy transition and grid modernization: Continued investments in renewable generation, offshore wind, and grid reinforcements are structural demand drivers for high- and medium‑voltage systems. This is a multi‑year spend theme that favors firms with proven HV capabilities and project execution credentials.
-
Digital infrastructure and data centers: Surge in cloud capacity and edge deployments sustains demand for high‑performance telecom and data cabling solutions. Small‑diameter, high‑throughput products and connector ecosystems are becoming de‑facto purchasing criteria.
-
Electrification of transport and buildings: Automotive wiring harnesses, EV charging networks and smart buildings create differentiated niches. Suppliers that can bundle cables with sensors, connectors and lifecycle services capture premium positions.
-
Raw‑material and trade volatility: Copper and aluminum price dynamics, coupled with recent trade measures, have materially altered cost profiles. For example, copper price escalation and new import duties on aluminum and copper derivatives emerged as defining constraints in 2025, making procurement strategy and local content planning essential for 2026 procurement cycles.
Regulatory and trade risks — what to factor into 2026 plans
Regulatory interventions in 2025 reshaped near‑term cost and sourcing calculus. Policymakers implemented higher duties on certain aluminum and copper products and enacted measures affecting imports from key geographies. Companies must therefore model scenarios that include elevated tariffs, phased tariff escalations and the potential for further export restrictions. The PW report offers a modular risk‑adjusted financial model that allows procurement and commercial teams to stress‑test contracts and budgeting decisions under these regimes.
Competitive landscape — strategic positioning and tactical moves
The market remains competitive but not monopolistic: leading global players bring distinct strengths that create opportunities for targeted competitive plays.
-
Prysmian Group (Milan): Scale and breadth across high/medium voltage and optical fibre place Prysmian as a reference operator in large infrastructure projects. Their 2025 investments in industrial cable capacity and fibre innovation can accelerate project delivery timelines for clients seeking integrated HV and fibre solutions.
-
Nexans (Paris): A product innovation and sustainability emphasis positions Nexans well for customers prioritizing lifecycle efficiency and decarbonization. Recent industrial cable launches sharpen their offering for energy‑efficient applications.
-
NKT A/S (Copenhagen): Strong credentials in submarine and offshore wind systems make NKT a preferred partner in marine energy projects; their technical experience reduces execution risk in large subsea deployments.
-
Fujikura (Tokyo) and LS Cable & System (Anyang): Both bring complementary strengths in optical transmission and integrated energy/telecom portfolios — making them natural partners for end‑to‑end deployments in dense urban and industrial zones.
-
Leoni AG (Nuremberg): A leader in automotive wiring and harnesses, Leoni is well positioned to capture gains from vehicle electrification and factory automation, though automotive cyclicality requires different capital allocation discipline than utility projects.
-
Amphenol, TE Connectivity and Belden: These connectivity and interconnect specialists are increasingly adjacent competitors as signal integrity, sensor integration and smart‑building ecosystems become differentiators. Recent product introductions from players in the building connectivity space highlight accelerating innovation and cross‑sector competition.
For strategic buyers and partners, the implication is clear: pursue alliances that plug capability gaps — for example, pairing HV project expertise with small‑form optical specialisms or combining harness know‑how with connector and sensor ecosystems to offer bundled electrification solutions.
Practical moves recommended for 2026
-
Rebalance procurement toward diversified sourcing and index‑linked contracts to mitigate tariff and commodity shocks; where possible, pursue localized content strategies for major projects to reduce tariff exposure and shorten lead times.
-
Prioritize investments that unlock adjacent value — e.g., optical fibre and connectivity solutions that complement power product lines — rather than broad horizontal scale alone.
-
Use portfolio decomposition to identify high‑margin niches (project EPC, lifecycle services, specialist subsea work) and establish differentiated go‑to‑market models for each segment.
-
Design a two‑track M&A approach: tuck‑ins to accelerate product innovation and select platform deals to capture regional scale where execution risk is low and regulatory exposure is manageable.
-
Strengthen commercial contracts with cost‑pass‑through and indexation clauses tied to primary commodities and published tariff schedules; couple this with enhanced customer education on total lifecycle costs.
What we intentionally withhold here — and why
To preserve the integrity of the analysis and adhere to the “trailer” principle, this introduction intentionally avoids disclosing detailed regional or application split figures and granular segment revenue tables. The full report contains the precise segmentation by region, type and application across the historical and forecast periods, accompanied by downloadable datasets and customizable model files. Those datasets are essential for transactional diligence, precise capital budgeting and contract negotiations; they are provided in the full study so that executives can run bespoke scenarios on live numbers.
Next steps for executives
For leadership teams preparing 2026 budgets, supplier negotiations, or strategic reviews, PW Consulting recommends an immediate three‑step action plan:
-
Run the model: Use the report’s scenario templates to stress‑test your revenue and margin plans under alternative commodity and tariff outcomes.
-
Prioritize capability audits: Map your current assets against the capability heatmaps in the study to identify must‑have investments and potential partnership targets.
-
Engage on strategy: Book a briefing with PW Consulting to convert the report’s evidence into a 90‑day plan for procurement, product and M&A actions tailored to your balance sheet and risk appetite.
PW Consulting’s Cables Market study translates a complex, fast‑evolving ecosystem into actionable priorities for 2026 decision‑makers. The full report contains the datasets, segmentation tables, supplier scorecards and executable templates referenced here. For organizations that need to operationalize these insights quickly — whether to defend margins, accelerate growth or secure strategic assets — the complete intelligence package is the next step.
For detailed analysis of this topic, please visit the official page: Cables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Advanced IC Packaging Equipment Market Poised for 12.5% CAGR Through 2032
By pmarketresearch, 2026-07-09
Advanced IC Packaging Equipment Market: Strategic Imperatives for 2026 Decision‑Makers
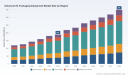
This briefing introduces PW Consulting’s Advanced IC Packaging Equipment Market study — a practical, decision‑focused analysis designed for executives who must set technology, capital‑investment, and supply‑chain strategy in 2026. Built on a 2025 base year with a historical window covering 2020–2025 and a forward view to 2032, the study frames opportunities and risks for equipment OEMs, OSATs, IDM packaging groups, private equity investors, and national policy planners. At the macro level, the market is forecast to expand from approximately USD 190 Million (base year 2025) to roughly USD 350 Million by 2032, representing a compound annual growth rate of about 12.5% — a pace that signals meaningful capital redeployment and technology refresh cycles across the ecosystem.
Advanced IC Packaging Equipment Market
Why this study matters in 2026
-
Technology inflection: Advanced packaging has moved from a performance differentiator to a foundational enabler for AI accelerators, high‑bandwidth memory (HBM), and heterogeneous system integration. Industry indicators show a majority of AI accelerator shipments already leveraging advanced packaging formats, driving demand for fine‑pitch interconnects and hybrid bonding process tools.
Advanced IC Packaging Equipment Market -
Policy and capital: Public programs (for example, national semiconductor initiatives awarded to packaging projects) and fresh private investments are de‑risking domestic capacity builds. That shift is creating windows for suppliers and OSATs to secure subsidies, but it also compresses timelines for equipment qualification and factory ramp‑up.
Advanced IC Packaging Equipment Market -
Market economics: The projected mid‑teens CAGR for equipment demand outpaces many adjacent semiconductor capital categories, reflecting both unit volume growth and significant per‑unit price escalation tied to higher automation, metrology integration, and yield enhancement capabilities.
Key market dynamics shaping buyer choices
-
Integration complexity: The move to multi‑die and silicon‑interposer solutions elevates requirements for precision dicing, thinning, hybrid bonding, and wafer‑level assembly. Buyers must prioritize equipment that integrates metrology and in‑line inspection to contain yield loss as overlay and planarity tolerances tighten.
-
Throughput vs. fidelity tradeoffs: As device architectures push pitch and density limits, the classic tradeoff between throughput and process fidelity becomes strategic. Early adopters of process platforms that maintain yield at scale will extract the largest marginal returns during the 2026–2029 ramp.
-
Automation and labor dynamics: Rising labor costs and workforce shortages in key geographies are increasing the value of robotics and end‑to‑end automation. Capital allocation should reflect not only machine cost but operational expense savings and reduced qualification time through standardization.
-
Supply resilience and localization: Geopolitical dynamics are prompting OSATs and IDMs to diversify equipment sourcing and to seek regional redundancy. Supplier selection today must factor export controls, spare‑parts logistics, and the ability to establish local service footprints.
-
Materials and process validation timelines: Raw‑material availability and incremental process windows (e.g., for new plating chemistries or thermal interface materials) are increasingly rate‑limiting. The most competitive equipment suppliers are those that partner upstream with materials vendors to accelerate qualification.
What the PW Consulting study delivers (practical, executable content)
-
Forward‑looking market sizing and demand modeling: a disciplined baseline (2020–2025) and a scenario‑based projection (2026–2032) that translate technology adoption curves into equipment spend profiles.
-
Technology and process roadmaps: mapping of key equipment classes to packaging architectures (e.g., wafer‑level, fan‑out, 2.5D/3D) and expected lifecycle timing for next‑generation modules.
-
Procurement playbook: specification templates, qualification checkpoints, and total cost of ownership (TCO) calculators designed for procurement teams to accelerate RFQs and reduce vendor selection risk.
-
CapEx phasing models and ROI scenarios: interactive frameworks showing how different mix choices (automation intensity, throughput targets, local vs. external service models) affect payback timelines.
-
Supplier scorecards and negotiation levers: qualitative and quantitative criteria to rank suppliers across technical capability, installed base, service network, and roadmap alignment.
-
Risk heatmaps and mitigation playbooks: regulatory exposures, critical‑spare dependencies, and geopolitical scenarios with prioritized mitigation actions for 12–36 month horizons.
Competitive landscape — reading supplier intent and capacity
Our study synthesizes public disclosures, engineering footprints, and product roadmaps to generate commercially actionable insight on leading equipment suppliers. Some strategic themes emerge across the competitive set:
-
Specialists with domain depth: Firms focused on discrete process steps (for example, wafer singulation, precision dicing, or molding) continue to command premium positions where process tolerance is the primary bottleneck. These vendors preserve margin by owning critical process IP and providing turnkey qualification support.
-
System integrators and platform players: Larger suppliers that bundle metrology, bonding, and fine‑line redistribution (RDL) solutions are positioning to sell higher‑value, fully integrated lines, shortening time‑to‑yield for customers but increasing supplier lock‑in risk for buyers.
-
Robotics and automation entrants: Companies delivering high‑precision handling and pick‑and‑place systems are increasingly central to packaging lines as vendors seek to automate labor‑intensive steps and reduce footprint.
-
Geographic strategy: Some OEMs are extending manufacturing capacity in target regions to better serve local OSAT ecosystems; others are doubling down on R&D and advanced process centers to protect IP and foster co‑development.
Highlights on named competitors (directional, strategic implications):
-
PacTech — laser and wafer‑level assembly specialist: strong in laser soldering and wafer‑level ball placement; attractive partner for OSATs pursuing heterogeneous integration pathways.
-
DISCO Corporation — precision singulation and grinding leader: foundational for 3D/2.5D flows where thinning and singulation determine yield. Their product maturity shortens qualification timelines.
-
Kulicke & Soffa — assembly and bonding breadth: combines bonding platforms with lithography tools for fan‑out and other advanced processes, enabling end‑to‑end assembly solutions.
-
BESI — focused on wafer‑level and hybrid bonding processes: advantaged where substrate and leadframe variety requires adaptable assembly equipment.
-
Applied Materials — materials engineering and hybrid bonding scale: recent strategic acquisitions broadened their plug‑and‑play portfolio for heterogeneous integration, accelerating their competitiveness in pilot‑to‑production transitions.
-
SUSS MicroTec, TOWA, Yamaha Robotics, Tokyo Seimitsu, Advantest, HANMI — each brings distinct strengths across lithography, molding, robotics, grinding, test, and AI/HBM oriented packaging tools. Buyers should prefer multi‑vendor collaboration models where no single OEM covers all specialized process steps.
Recent developments shaping near‑term strategy
-
Strategic R&D and facility moves: Industry announcements in 2025–2026 — new plants, rebranding and consolidation of bonding lines, and the opening of innovation centers — reflect supplier investments in production capacity and customer co‑development. These moves shorten qualification cycles and improve responsiveness for early‑stage pilots.
-
M&A and team integrations: Acquisitions that merge niche teams into larger semiconductor groups change the competitive topology, creating more vertically integrated suppliers that can offer bundled solutions, but sometimes at the cost of reduced outside interoperability.
-
Public funding: National semiconductor programs that include packaging initiatives materially affect where new capacity will be placed and which suppliers will be favored for local content requirements.
How to translate insight into 2026 action
-
Prioritize pilot investments now: Allocate a meaningful portion of 2026 process‑development budgets to pilot lines that validate hybrid bonding, high‑density RDL, and HBM assembly. Early qualification wins shorten time‑to‑volume in 2027–2029.
-
Design for supplier modularity: When specifying equipment, insist on open interfaces and clear IP handover paths to avoid technical lock‑in while still capturing the operational benefits of integrated systems.
-
Negotiate performance‑based contracts: Shift procurement toward outcome‑based SLAs that tie payment and warranty terms to throughput and yield milestones during ramp phases.
-
Use scenario planning: Develop three prioritized scenarios (baseline demand growth, accelerated AI adoption, and fragmented/regulatory constrained supply) and stress‑test capex and sourcing plans against each.
-
Leverage public incentives strategically: Target grants and subsidies for the riskiest qualification stages (materials/process validation) while using commercial capital to scale later stages.
Closing — where to go next
The Advanced IC Packaging Equipment Market will be a high‑velocity domain between 2026 and 2032. For executives, the imperative is clear: move beyond vendor claims to quantify how equipment choices affect yield, time‑to‑volume, and unit economics across plausible demand scenarios. PW Consulting’s full report provides the granular segmentation, supplier scorecards, and downloadable CapEx models that practitioners need to convert strategy into executable programs. For the complete datasets, detailed segmentation, and executable procurement templates, please refer to the report’s primary access channel.
For detailed analysis of this topic, please visit the official page: Advanced IC Packaging Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aramid Paper Market to Reach USD 892.38M by 2032 at 6.1% CAGR
By pmarketresearch, 2026-07-09
Aramid Paper Market: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a forward‑looking synthesis of the aramid paper market intended to frame executive decisions in 2026. Built on a 2025 base and a modeled forecast window through 2032, our analysis shows a resilient market trajectory—historical growth from 2020 into 2025 and a modeled compound annual growth rate (CAGR) of 6.1% across the forecast period. The study integrates primary supplier intelligence, raw‑material and regulatory dynamics, and scenario‑based financial modeling to deliver a pragmatic playbook for procurement, product strategy, and capital allocation.
Aramid Paper Market
Why this report matters in 2026
-
Market momentum: The aramid paper market has expanded materially over the past five years and is expected to continue expanding under multiple demand vectors (industrial electrification, transportation safety standards, and aerospace/high‑temperature applications). Understanding the magnitude and drivers of that expansion is necessary to prioritize investment in capacity, qualification programs, and supplier contracts.
Aramid Paper Market -
Regulatory inflection points: New European rules and global fire‑safety standards are reshaping product specifications and traceability requirements. These changes will affect product design, compliance costs, and route‑to‑market strategies for exporters and converters in 2026 and beyond.
Aramid Paper Market -
Supply‑chain sensitivity: Feedstock cost volatility and import tariff regimes are creating structural cost and availability risks. Companies that incorporate feedstock and tariff scenarios into commercial and operational planning will preserve margins and avoid disruptive shortages.
-
Competitive concentration: The industry exhibit a high level of supplier concentration, leading to structural pricing power among top producers and meaningful barriers to rapid commoditization—implications that should inform sourcing and strategic partnership decisions.
How PW Consulting’s aramid paper study is structured (practical content)
-
Executive Briefing and 60‑minute board deck for immediate use by leadership.
-
Top‑down and bottom‑up market-sizing framework (2020–2025 historical, 2026–2032 forecast) with scenario outputs (base, downside, upside) and sensitivity to feedstock and regulatory inputs.
-
Cost‑curve and margin model for producer economics that ties raw‑material price paths to finished‑product margins under multiple pricing and tariff scenarios.
-
Supplier landscaping and scorecards (capacity, route‑to‑market, technology differentiation, compliance readiness, and conversion capabilities). Note: detailed segment‑level tables and company share matrices are reserved for the full report.
-
Regulatory and standards impact map covering ecodesign/traceability, chemical registration, and transportation/fire safety test matrices—plus a compliance gap analysis and remediation roadmap.
-
Commercial playbook: procurement negotiation levers, qualification accelerators for OEMs, pricing playbooks under tariff regimes, and go‑to‑market options for converters and specialty distributors.
-
M&A and partnership shortlists with an acquisition valuation framework keyed to synergies, capacity uplift timelines, and integration risk.
-
Implementation roadmaps (90‑, 180‑, and 365‑day plans) for four typical buyer archetypes: OEMs (aerospace/transport), utilities & transformers, converters/distributors, and producers.
Competitive landscape — who matters and why
-
E. I. du Pont de Nemours and Company (DuPont) — A primary technology and brand leader, producing legacy meta‑ and para‑aramid papers (Nomex® and Kevlar®). DuPont’s recent portfolio refresh emphasizes higher thermal‑resistance grades for industrial and aerospace markets, signaling continued investment in premium product differentiation and qualification support for strategic OEMs.
-
Teijin Aramid — Vertical integration from fiber to paper gives Teijin advantages in traceability and material specification control. Their early rollout of Digital Product Passport (DPP)‑compliant products aligns them with Europe’s traceability requirements and positions them favorably with sustainability‑focused OEM procurement teams.
-
Regional Chinese producers (several leading manufacturers and converters) — These players are scaling capacity to serve domestic and regional demand with a focus on cost competitiveness and converter services. They are critical participants in Asia‑Pacific supply networks and fast qualification cycles for electrical insulation markets.
-
Kolon Industries and Japanese specialists — Offer complementary portfolios, regional customer support, and established qualifications for automotive and industrial insulation customers.
-
Converters and specialty distributors — Companies that perform slitting, die‑cutting, lamination and supply chain services provide critical customer proximity and customization, and are an increasingly strategic partner type for producers seeking to accelerate market access.
-
Market concentration metrics indicate a high degree of consolidation among the top suppliers. That concentration translates into differentiated supplier negotiation dynamics: tier‑one players can defend pricing and control capacity rollouts, while regional players compete on speed, customization, and cost.
Recent industry signals and their operational impacts
-
Product introductions and portfolio upgrades: Several leading manufacturers have introduced new grades optimized for thermal resistance or transformer/motor insulation. For decision‑makers, this raises the bar for qualification cycles and creates near‑term opportunities for product migration and premium pricing.
-
Traceability and DPP preparation: Manufacturers aligning with Digital Product Passport rules are building capabilities that will become procurement prerequisites in regulated markets by 2030. Buyers that pre‑qualify DPP‑ready suppliers avoid retrofit costs and procurement delays.
-
Feedstock pressure: Primary feedstocks remain concentrated and price swings have material short‑term effects on producer margins. Recent spot‑price upticks underscore the need for hedging strategies, long‑term supplier agreements, and alternate‑feedstock R&D investments.
-
Tariff and trade friction: Cumulative tariffs on certain imports have altered routing and landed cost dynamics in key markets. Buyers must incorporate landed‑cost and time‑to‑qualify tradeoffs into near‑term sourcing decisions rather than relying solely on unit price comparisons.
Strategic imperatives for 2026 — what companies should do now
-
Prioritize dual levers: supply security and product differentiation. For OEMs and utilities, secure multi‑source supply agreements with tiered penalty clauses and capacity carve‑outs for critical grades. For producers, accelerate premium grade commercialization and shorten OEM qualification timelines.
-
Operationalize traceability. Invest in the data, labeling and supplier audit capabilities required for Digital Product Passports and tighter chemical‑registration regimes. Early movers will capture procurement RFPs that exclude non‑DPP suppliers by design.
-
Hedge feedstock risk. Implement a blended approach: fixed‑price supply contracts for baseline volumes, spot exposure for opportunistic purchases, and targeted R&D into lower‑cost or regulated‑friendly chemistries to de‑risk long‑term feedstock constraints.
-
Reassess go‑to‑market partnerships. Producers should deepen relationships with converters and specialty distributors to accelerate localized service and qualification support. Buyers should build preferred‑supplier programs with clear escalation paths for technical failures and capacity shortfalls.
-
Embed tariffs and non‑tariff barriers into price/cost models. Model landed cost to the point of use and include qualification lag as a cost of switching suppliers—this will change the economics of near‑term reshoring vs. sourcing from low‑cost regions.
-
Use M&A as a tactical instrument. Given supplier concentration, bolt‑on acquisitions of converters or niche capacity can be the fastest way to secure market access, technological differentiation, or localized manufacturing footprints.
How to use this research in executive decision cycles
-
Board and investment committees: Use the scenario outputs and sensitivity matrices to stress‑test capex proposals and to set hurdle rates that account for feedstock and regulatory risk.
-
Procurement leaders: Convert the supplier scorecards and contractual playbooks into a 12‑ to 24‑month negotiation agenda, focusing on capacity reservation, DPP readiness, and inbound logistics contingency.
-
Product and R&D: Prioritize qualification resources on grades that unlock the highest incremental margin or defend the most strategic revenue bases (transformer, aerospace, and critical industrial segments).
-
Corporate development: Deploy the M&A target list and valuation framework to accelerate small, accretive deals that expand downstream capabilities or shorten time‑to‑market for new grades.
PW Consulting’s full publication contains the granular datasets, segment demand matrices, producer economics spreadsheets, supplier scorecards, and an implementation toolkit that operational teams can deploy immediately. This summary is designed to demonstrate the analytical depth of the study while preserving the segment‑level intelligence that underpins high‑value commercial decisions. To access the full market models, executable supplier playbooks, and the M&A shortlist that complement this executive overview, please visit the report page linked from PW Consulting’s Aramid Paper Market announcement.
For detailed analysis of this topic, please visit the official page: Aramid Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aquaculture Cages Market to Reach USD 464M by 2032 (6.8% CAGR)
By pmarketresearch, 2026-07-09
Aquaculture Cages Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic preview of the Aquaculture Cages Market intended to orient senior executives, investors, and operations leaders preparing decisions in 2026. This preview showcases the analytical depth of our forthcoming market study while deliberately withholding detailed subsegment tables and proprietary forecasts that sit behind our paywall. Think of this as the trailer: enough insight to plan your next moves with confidence, but you’ll need the full report to execute with precision.
Aquaculture Cages Market
Market Snapshot — Macro Readings You Can Use Today
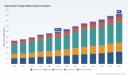
Built on a 2025 base year, our market model shows the aquaculture cages market expanding at a steady compound annual growth rate (CAGR) of 6.8% through the 2026–2032 forecast horizon. The market has shown consistent recovery and expansion since 2020, reflecting rising protein demand, investments in farmed seafood, and technology adoption that improves yield and compliance. In revenue terms (USD, Million), the market is transitioning from the high‑to‑low hundreds in the mid‑2020s toward a substantially larger base by the end of the decade. Market concentration metrics confirm a fragmented supplier landscape: the top three firms account for roughly a quarter of market value (CR3 ≈ 24.5%) and the top five remain below 30% (CR5 ≈ 28.5%). That fragmentation creates both risk and opportunity for incumbents and new entrants alike.
Aquaculture Cages Market
Why 2026 Is a Strategic Inflection Point
- Regulatory stringency meets premium market access. Tightening rules on water quality, waste, and disease control are accelerating the adoption of advanced cage designs and real‑time monitoring. Simultaneously, certification regimes such as ASC and BAP are increasingly gatekeeping premium procurement channels. Companies that can demonstrate compliance and traceability will win margin‑rich contracts and offtake agreements.
- Material economics are reshaping capex decisions. HDPE has emerged as the dominant material for marine cages because of its durability and ability to withstand exposed conditions. While initial material costs are higher relative to older alternatives, service life improvements reduce total cost of ownership — a classic capex vs. lifecycle cost tradeoff executives must model explicitly in 2026 procurement cycles.
- Technology convergence demands system-level thinking. Floating closed cages, semi‑closed designs, submersible nets, and integrated RAS (recirculating aquaculture systems) are no longer niche. Customers now buy integrated production solutions: containment hardware, sensors, automation, and service contracts. Suppliers who compete only on hardware risk being marginalized unless they broaden into system services or partner strategically.
Structural Drivers and Market Dynamics
Several interlocking dynamics underpin the forecast trajectory:
Aquaculture Cages Market
- Sustainability and certification: Access to premium buyers increasingly requires ASC/BAP compliance. That is pushing producers to upgrade pen design, waste‑management, and monitoring capabilities, creating demand for advanced cage systems and compliance services.
- Raw material and lifecycle economics: HDPE and high‑performance fibers (e.g., Dyneema®, UHMWPE) are preferred in many marine applications for longevity and resistance to biofouling and mechanical stress. Buyers are trading higher upfront cost for lower replacement frequency and reduced operational disruption.
- Regulatory constraint and ecological concerns: In select jurisdictions, stricter rules around stocking densities, prohibited areas, and environmental impact are predicted to restrain growth in certain nearshore models. This sets up regionalized demand for offshore, closed, or land‑based solutions.
- Fragmented supply base: A relatively low CR5 means many local and specialist suppliers coexist with global systems integrators. This fragmentation encourages acquisition strategies by larger firms and presents opportunities for niche technology providers to capture premium segments.
Competitive Landscape — Who Matters and Why
The competitive field combines global integrators, specialist fabricators, and regional manufacturers. Below are the strategic profiles of core players you’ll observe in our market map and why they matter for 2026 strategy:
- AKVA Group (Norway) — A global leader in plastic pens and complete cage systems; strong in HDPE solutions and system integration. Their strength is breadth: combining hardware with control systems and service offerings makes them a natural partner for large producers targeting certified markets. ( https://www.akvagroup.com/)
- Badinotti Group (Italy) — Specialist in net cages and submersible systems, with recent M&A to broaden containment capabilities. Their acquisition activity signals consolidation among high‑end containment specialists. ( https://www.badinotti.com/)
- Selstad AS (Norway) — Supplier of multiple cage geometries and high‑strength materials. Their product breadth across nylon, HDPE, Dyneema®, and UHMWPE positions them to serve bespoke projects where design and material selection are critical. ( https://selstad.no/)
- AquaMaof (Israel) — Focus on floating closed systems and RAS integration, representing the growing intersection between offshore and land‑based technologies. Their offerings illustrate the premium placed on biosecurity and containment. ( https://www.aquamaof.com/)
- Qingdao Qihang Fishing Cage Co., Ltd (China) — Volume manufacturer of offshore HDPE cages; key supplier for large scale projects where unit economics matter. ( https://qhfishing.com/)
- Hunan Xinhai Co., Ltd (China) and Zhejiang Honghai (China) — Regional manufacturers catering to large domestic and export demand, often competing on price and lead time.
- Garware Technical Fibres Ltd (India) — Material supplier of high‑performance synthetic netting, an essential upstream player for nets and containment systems. ( https://www.garwarepolyester.com/)
Recent market activity underscores strategic themes you should consider: product supply agreements that create bundled offerings (November 2024), and acquisitions that expand technical capability and market reach (September 2024). These moves are consistent with a market in which system capability and geographic reach increasingly determine contract awards.
Operational and Commercial Implications for 2026 Decision Cycles
- Procurement: move from unit price to lifecycle cost models. Expect procurement teams and lenders to demand lifecycle projections that explicitly incorporate HDPE longevity, replacement cycles, and operational downtime. Financial models that fail to include these will misprice projects.
- Product strategy: prioritize modularity and serviceability. Designs that enable on‑site maintenance, sensor upgrades, and phased migration to closed or semi‑closed systems will win larger long‑term contracts.
- Partnerships and M&A: tilt toward capability fills. For hardware specialists, a tilt toward partnerships with automation, sensing, and biosecurity providers is a rational route to sustaining value capture. Acquisitions that fill technological gaps in monitoring, nets, or mooring systems will be accretive.
- Supply chain resilience: Locking material supply (HDPE resin, high‑strength fibers) and diversifying fabrication capacity across geographies will be necessary to manage lead times and price volatility in 2026 procurement windows.
- Regulatory strategy: Firms should invest in regulatory intelligence and certification roadmaps to accelerate market access for premium buyers. Early investment in ASC/BAP compliance provides pricing leverage and de‑risking for financiers.
What PW Consulting’s Full Report Delivers
Our complete Aquaculture Cages Market report (base year 2025) is structured to convert insight into action for 2026 decisions. Highlights include:
- Proprietary market sizing and seven‑year forecasts at product, application, and regional levels (2026–2032).
- Supply‑side mapping and competitive benchmarking with capability and financial proxies for major global and regional players.
- Scenario models for regulatory tightening, raw material price shocks, and accelerated certification adoption — with actionable sensitivities for project finance teams.
- Vendor selection frameworks and TO‑BE purchase decision matrices that align technical specifications with lifecycle economics.
- Commercial playbooks for OEMs, integrators, and producers, including partnership archetypes, M&A screening checklists, and go‑to‑market strategies tailored to different buyer segments.
Note: This preview intentionally omits the granular segment tables, region/application revenue splits, and proprietary pricing schedules that underwrite our revenue forecasts. These items are included only in the licensed report to preserve the competitive advantage they confer. If your planning horizon requires executable numbers (e.g., tender bids, capex approval, or acquisition underwriting), access to those tables is essential.
Actionable Next Steps for Executives in 2026
- Commission an internal lifecycle cost analysis now that HDPE and high‑performance fibers dominate product selection. Use scenario runs to test vendor proposals against 7–10 year service life assumptions.
- Prioritize partnerships with system integrators or sensor providers to offer bundled, certified solutions to premium buyers.
- Evaluate M&A targets among specialist containment designers and net‑material manufacturers to close capability gaps quickly.
- Institute a supply‑risk audit covering resin and fiber suppliers, and redesign procurement contracts to include price adjustment clauses and capacity guarantees.
- Invest in certification roadmaps for target production sites to access ASC/BAP channels and secure higher offtake prices.
PW Consulting’s full Aquaculture Cages Market report equips you with the precise tables, scenario models, and vendor scorecards required to operationalize the strategies above. For teams preparing capital allocations, OEM sourcing, or strategic M&A in 2026, that level of granularity is non‑negotiable.
To request the full report, licensing options, or a tailored executive briefing that applies these insights to your portfolio, contact PW Consulting’s Market Intelligence team. Our next cohort of advisory engagements begins in Q3 2026 — seats for bespoke modeling are limited.
For detailed analysis of this topic, please visit the official page: Aquaculture Cages Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dental chair market set for 5.4% CAGR through 2032, unlocking USD 848M potential
By pmarketresearch, 2026-07-09
Dental Chair Market — 2026 Strategic Preview
Executive trailer
By the close of our 2025 base year the global dental chair market had consolidated into a mature, steadily expanding sector with an installed-base-driven services economy. PW Consulting’s latest research quantifies the market at approximately USD 587.7 million in 2025 and projects a steady compound annual growth rate (CAGR) of 5.4% through the 2026–2032 forecast window, taking the market toward an estimated USD 848.0 million by 2032. These headline figures mask an important strategic truth for 2026: incremental revenue is increasingly sourced from connectivity, aftermarket services and regulatory-driven product refreshes rather than from replacement volumes alone.
Dental Chair Market
Why this report is strategically material for 2026 decisions
- Portfolio prioritization: With moderate overall growth but rising aftermarket and integration opportunities, OEMs must decide which product lines become platform investments versus maintenance lines. Our research converts market momentum into concrete go/no-go decision triggers for 2026 capex cycles.
- Regulatory readiness: Recent device-class guidance and standard updates are compressing time-to-market for compliant devices. Companies entering or expanding in regulated markets must embed regulatory timelines into commercial plans in 2026.
- Service and margin engineering: As concentration metrics show a fragmented supplier base, service, consumables and retrofit offerings represent outsized margin expansion opportunities — and key defenses against low-cost entrants.
What the report delivers (practical, actionable content)
- Validated market sizing (historical 2020–2025) and high- and mid-case forecasts (2026–2032) with sensitivity scenarios that isolate the impact of regulatory shock events, adoption curves for connected units, and price erosion.
- Competitive playbooks for the leading OEMs plus a mapped set of challenger strategies — including go-to-market options, channel economics, and partner ecosystems.
- Operational checklists and templates: RFQ scoring model for clinical buyers, a 12–24 month rollout planner for new units, a retrofit ROI calculator for service organisations, and a procurement negotiation playbook for distributors.
- Regulatory and compliance tracker: device-class implications, 510(k) considerations for the U.S., and recommended testing regimens aligned with proposed standards — designed to reduce submission cycles and rework risk.
- M&A and partnership screening matrix: twenty-one qualitative and quantitative criteria to quickly score targets for tuck-in acquisitions, aftermarket platform buys, and distribution alliances.
- Buyer personas and purchasing cycles: clinic-level profiles across practice types and procurement cadences, enabling calibrated commercial outreach and pricing stratification.
Market dynamics and what they mean for strategy
The 5.4% CAGR we model reflects a market where steady demand meets technological differentiation. Several dynamics are shaping supplier economics in 2026:
Dental Chair Market
- Digital integration: Dental chairs are evolving from standalone capital equipment into nodes within a digital operatory. Units offering IoT-enabled maintenance monitoring, AI-assisted positioning, and seamless connectivity with digital imaging and practice-management platforms are unlocking higher service attach rates.
- Regulatory friction: Classification rules and submission requirements (including 510(k) pathways for certain product codes) are creating a premium for regulatory competence. Time and cost-to-clearance will be decisive in prioritizing launches and market entry timing.
- Infection control and ergonomics: Post-pandemic infection-control expectations and practitioner ergonomics are now core purchase drivers; product features tied to these considerations significantly shorten sales cycles in credential-sensitive buyers.
- Fragmented supplier landscape: Concentration ratios show a market that remains relatively unconsolidated. That fragmentation creates space for regional champions and low-cost incumbents, but also raises the value of scale in service networks and spare-parts logistics.
Competitive landscape — what to watch from the major players
Our competitive analysis synthesizes public product portfolios, recent product launches, regulatory filings and trade-show disclosures into comparative strategic profiles. The market is occupied by a mix of large global platform vendors, specialist ergonomics houses and lower-cost regional suppliers. Three strategic archetypes emerge:
Dental Chair Market
- Platform integrators (e.g., global firms with digital workflow capabilities): These players compete on ecosystem value — integrating chairs with imaging, scheduling and AI tools to capture recurring software and service revenue. Their strengths are scale, brand reach and cross-sell; their vulnerability is slower OEM-level innovation cycles.
- Ergonomics and infection-control specialists: Firms with portfolios emphasizing practitioner comfort, accessibility and barrier-free designs win in credential-sensitive clinics and public-health procurement. Their opportunity is premium positioning; risk comes from copycat features at lower price points.
- Cost-focused regional suppliers: These vendors compete on total cost-of-ownership and rapid channel responsiveness. Clearance into highly regulated markets (and the accompanying support infrastructure) is their growth limiter — but successful U.S. 510(k) or EU conformity entries materially expand their addressable markets.
Illustrative recent moves are instructive. A leading European OEM introduced a new generation of operatory units with ambidextrous delivery and modular consoles at IDS 2025 — a feature set designed to accelerate adoption in high-turnover clinics and multi-disciplinary suites. A major Chinese supplier secured U.S. regulatory clearance for an integrated dental unit during 2025, demonstrating how regulatory progress converts to immediate commercial opportunity. Separately, a major dental association has proposed updated standards addressing air, water and wastewater systems for stationary dental units — a development that will shape laboratory testing and procurement specifications for years to come.
Regulatory and operational 'noise' that matters
- Device classification and 510(k) pathways: Firms must map product variants to applicable device codes early and budget for pre-submission validation. Regulatory delays are the most common cause of launch slippage in our modeling.
- Proposed standards for utility systems: Standards addressing air, water, suction and wastewater will pressure design teams to validate subsystem robustness and maintenance protocols — an opportunity for vendors to productize validated maintenance contracts.
- Clinical training and maintenance labor: As device complexity increases, buyer decisions increasingly weigh the availability of trained maintenance personnel. Training requirements create both a barrier-to-entry for new vendors and an upsell channel for established ones.
Strategic imperatives for executives planning in 2026
- Shift investment toward services and software: With capped hardware growth, prioritize development of predictive maintenance, subscription-based consumables and digital service offers that raise lifetime value.
- Regulatory-first product roadmaps: Embed regulatory milestones into product roadmaps and commercial launch calendars. A clear 510(k)/CE strategy reduces time-to-revenue and conserves R&D cash.
- Selective geographic expansion: Use regulator-approved product variants as entry tokens into high-return markets, pairing clearances with channel partnerships to accelerate adoption.
- Operationalize retrofit and upgrade programs: Design retrofit kits and upgrade packages for installed bases to accelerate pull-through revenue without capturing full replacement cycles.
- M&A: Screen targets that add either a service-delivery network or a software/IoT capability rather than bolt-on hardware alone; these yield faster margin improvements in our scenario runs.
How PW Consulting supports your 2026 playbook
PW Consulting’s Dental Chair Market research is structured as a practical decision-support toolkit. Clients gain access to interactive dashboards, reproducible financial models and a prioritized list of moves calibrated to different corporate objectives (growth, margin expansion, defensive market share). For teams planning product launches or market entries in 2026, we provide:
- A 24–36 month commercialization roadmap synchronized to regulatory timelines and regional procurement cycles.
- Deal-ready M&A target shortlists with valuation heuristics and integration risk assessments.
- Customized pricing and service bundling models that translate attach-rate improvements into EBIT impact.
- Implementation toolkits: RFQ templates, training curricula for service partners, and a sprint-plan for pilot deployments.
Next steps — where to find the full intelligence
This preview surfaces the signal trends and operational implications we expect to drive strategic decisions in 2026. For the granular, segment-level breakdowns, competitive scorecards, full one-to-one channel maps, and the downloadable financial model that underpins our forecasts, please consult the full PW Consulting Dental Chair Market report on our website. The detailed tables and dashboards are intentionally gated: they contain the precise segment splits and regional allocations that operational teams and dealmakers need to convert insight into action.
If your 2026 planning cycle requires scenario testing, regulatory submission roadmaps, or an M&A target vetting brief, PW Consulting can deploy a tailored engagement to align market intelligence with executable plans within 6–8 weeks.
For detailed analysis of this topic, please visit the official page: Dental Chair Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Calcium Aluminate Cement Market 2026: Strategic Preview for Executive Decision‑Making
As PW Consulting’s senior strategic advisor and chief industry analyst, I present a focused industry preview of the Calcium Aluminate Cement (CAC) market designed to support executive decisions in 2026. This brief synthesizes the macro trajectory, competitive dynamics, and near‑term disruption vectors that will determine winners and losers through the 2026–2032 forecast horizon. It showcases the kind of high‑caliber analysis included in our full market study while intentionally reserving granular segment and company volume data for subscribers. Consider this a strategic trailer: enough insight to inform short‑term moves and strategic planning, and an invitation to access the full report for transaction‑grade detail.
Calcium Aluminate Cement Market
Market snapshot: trajectory and scale
The CAC market has demonstrated steady, resilient expansion across the past half decade. Between 2020 and 2025 global revenues rose meaningfully, and the market is projected to continue expanding at a compound annual growth rate (CAGR) of approximately 5.2% over the 2026–2032 forecast period. By our base year 2025 the market reached a substantive size, and under current assumptions it is expected to continue toward a materially larger market by the end of the forecast window.
Calcium Aluminate Cement Market
Why this matters for 2026 decisions: the market’s consistent mid‑single‑digit CAGR signals a balance between structural demand drivers (refractories, infrastructure repair, specialized construction) and episodic pressures (raw‑material volatility, regulatory shifts). Organizations planning capacity investments, M&A, or product repositioning in 2026 should treat the CAC sector as an established yet evolving niche where timing, technical differentiation, and supply‑chain resilience determine returns.
Calcium Aluminate Cement Market
Key market dynamics shaping 2026 strategy
- Raw‑material concentration and price volatility: The bauxite‑to‑alumina value chain remains geographically concentrated. While recent projections point to a short‑term decline in alumina prices, the concentration of feedstock sourcing creates asymmetric supply‑risk that can transmit rapidly into CAC input costs. For 2026 planning, firms must stress‑test procurement strategies for scenarios that include both price rebounds and logistics disruptions.
- Transition of downstream industries: Steelmakers accelerating conversion to electric‑arc furnaces (EAFs) are increasing demand for alumina‑rich refractory linings that withstand extreme operating temperatures. This secular shift changes not just volumes but the technical specification matrix for CAC grades—favoring higher‑alumina formulations and specialty binders.
- Regulatory and standards evolution: Adoption of performance standards (for example, sulfate‑resistant mortars in wastewater applications and updated monolithic specifications) is increasing the technical bar for CAC products in certain end markets. Compliance and participation in standards development offer both defensive protection and a route to premiumization.
- Thermal energy storage and cyclic durability requirements: Emerging energy‑storage use cases require matrices that withstand hundreds of cycles at elevated temperatures without significant mechanical degradation. This opens a high‑value adjacent market where CAC formulations can compete with specialty refractories.
- Supply‑side enhancements and capacity moves: Recent capacity expansions and facility investments by major producers reflect a strategic pivot toward regional resilience and faster time to market. Expect logistics, lead times, and product availability to become important commercial differentiators in 2026 contracting.
Competitive landscape — what leaders are doing
The CAC industry is concentrated at the top, with a relatively compact group of global suppliers controlling a dominant share of production. Market concentration metrics indicate a meaningful incumbency advantage, but not an insurmountable moat—creating space for differentiated entrants and regional champions.
- Calucem (Pula, Croatia): A global leader known for its flagship Ciment Fondu and specialty grades. Recent capacity acceleration at its New Orleans facility underscores an offensive growth posture aimed at infrastructure and refractory demand spikes—an explicit signal that execution speed and regional proximity are core competitive levers in 2026.
- Almatis (Frankfurt, Germany): A materials specialist that continues to introduce next‑generation CAC products targeted at thermal resistance and durability in steel and foundry sectors. Product innovation remains Almatis’ primary route to defend pricing and margin.
- Imerys Aluminates (Paris, France): Positioning around specialty binders and low‑carbon formulations represents a dual play: capture premium technical applications while aligning with decarbonization trends. Recent portfolio updates emphasize sustainability as a strategic differentiator.
- Çimsa (Istanbul, Turkey): One of the world’s largest CAC producers; its scale and regional footprint make it a go‑to supplier for construction‑linked volumes and export flows.
- Kerneos (now part of Imerys): Continues to play a foundational role in high‑temperature binders—its technology heritage is a key asset for industrial applications.
- Other notable players: A mix of regional specialists and high‑alumina manufacturers (including entities operating in Europe, North America, and Asia) remain active, often focusing on niche technical grades or local supply advantages.
For 2026, competitive advantage will be defined by three capabilities: technical differentiation (formulations and low‑carbon binders), supply‑chain agility (regional production and inventory models), and commercial sophistication (value‑based pricing and performance guarantees).
Recent industry moves — tactical signals
- Capacity expansions and new facility investments reflect an emphasis on lead‑time reduction and local service. Companies that announced expansions in late 2025–early 2026 are positioning to capture near‑term infrastructure projects and refractory replacement cycles.
- Product launches and R&D up‑weighting point toward a bifurcation of the market: commodity grades compete on price and availability, while advanced binders command premiums based on performance and sustainability credentials.
- Sustainability‑oriented product updates and low‑carbon binder introductions are already influencing procurement decisions among infrastructure owners and engineering firms; expect green specifications to be a gating criterion in large tenders by the end of 2026.
What our full report delivers (practical, action‑oriented tools)
PW Consulting’s complete market study is built as a toolkit for executives, investors, and commercial leaders who must make decisions in 2026. Highlights include:
- Scenario‑based demand forecasts through 2032 incorporating macroeconomic, regulatory, and technology adoption variables.
- Supply chain risk matrix that quantifies exposure to feedstock concentration, logistics bottlenecks, and energy cost shocks, with mitigation playbooks for each risk class.
- Competitor playbooks and capability maps covering product portfolios, plant footprints, strategic investments, and M&A posture—sufficiently granular to support diligence and negotiation strategies.
- Commercial optimization tools: pricing elasticity models, channel strategies for monolithics vs. castables, and tender response templates that reflect technical value rather than commodity pricing alone.
- CapEx and capacity planning frameworks that translate demand scenarios into plant size, payback profiles, and optimal timing for brownfield vs. greenfield options.
- Regulatory and standards tracker highlighting jurisdictions where evolving norms (e.g., wastewater and refractory standards) will materially change buyer requirements.
Importantly, the report provides downloadable datasets and interactive dashboards with segmented demand by region, application, and grade, as well as company‑level estimates—reserved for the full publication. This granular view is essential for transaction teams, procurement, and product managers preparing 2026 budgets.
Implications for 2026 corporate strategy
- For incumbent producers: Prioritize investments that improve regional responsiveness—shorter lead times and localized inventory reduce customer churn. Targeted R&D on low‑carbon and high‑performance grades will protect premium segments from margin erosion.
- For new entrants or adjacent‑market players: Identify narrow technical niches (e.g., thermal‑cycling durable matrices, sulfate‑resistant mortars) where certification barriers and technical switching costs create defensible positions. Partnering with engineering houses can accelerate specification adoption.
- For investors and M&A teams: Focus diligence on feedstock security, energy cost exposure, and the presence of premium product lines. A modest premium for targets with validated low‑carbon products or proprietary formulations is justified by accelerating tender preferences.
- For procurement and end users: Shift contracting toward performance‑based agreements and supplier diversification. Incorporate resilience metrics into supplier scorecards (e.g., regional inventory, alternative sourcing, product traceability).
Why PW Consulting’s report matters for your 2026 decisions
Decisions made in 2026—CapEx approvals, merger targets, product roadmaps, and procurement frameworks—will lock in competitive positioning for the better part of a decade. Our study combines market‑grade forecasting (anchored to the current trajectory and a 5.2% forecast CAGR) with executable tools that translate insight into plans: scenario playbooks, supplier risk matrices, and transaction support materials. The content you see here indicates the analytical depth of the full study; the datasets, company‑level metrics, and segment model outputs in the full report are what operationalize strategy.
Next steps
- Download the full report to access segmented forecasts, company volumes, pricing curves, and the interactive scenario toolset (note: detailed regional and application splits and company‑level volumes are available only in the full report).
- Engage PW Consulting for a tailored 2‑day strategy workshop: we will map your portfolio to the scenarios most relevant to your balance sheet and produce a prioritized 18‑month action plan.
For teams preparing 2026 budgets: treat CAC not as a static raw material cost line but as a set of technical offerings that can be productized, priced, and defended. The market’s mid‑single‑digit growth and concentrated supplier base create opportunity for disciplined players who can align technical differentiation with resilient supply chains and decisive commercial models. PW Consulting’s full study delivers the precise inputs you need to convert that opportunity into measurable returns.
For detailed analysis of this topic, please visit the official page: Calcium Aluminate Cement Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plasma Protein Therapeutics Market to Reach USD 43.26 Billion by 2032 at 5.6% CAGR
By pmarketresearch, 2026-07-09
Plasma Protein Therapeutics Market — Strategic Outlook for 2026 Decision-Making
Executive summary
The plasma protein therapeutics market has transitioned from steady growth to a phase of strategic inflection. After expanding from roughly USD 22.2 billion in 2020 to about USD 29.7 billion by our 2025 base year, the sector is forecast to continue climbing to an estimated USD 43.3 billion by 2032 at a compound annual growth rate (CAGR) of approximately 5.6% across the 2026–2032 forecast window. This growth is real, durable and unevenly distributed — driven by demographic tails, rising chronic immunological indications, evolving regulatory expectations, and persistent supply-side constraints tied to plasma sourcing and concentrated manufacturing footprints.
Plasma Protein Therapeutics Market
Why this report matters for 2026 strategic choices
-
Timing of investment: 2026 is the first full planning year in which recent capacity additions, regulatory approvals and industry governance changes materially reshape supply dynamics. Decisions made this year about capacity, offtake contracts and M&A will materially affect competitiveness for the remainder of this decade.
Plasma Protein Therapeutics Market -
Risk management: The industry is operating with a persistent plasma collection gap — conservatively estimated in the single-digit millions of liters per year — which translates into higher marginal cost of goods, allocation dynamics, and strategic prioritization of indications and customers.
Plasma Protein Therapeutics Market -
Competitive repositioning: Recent product approvals and commercial launches are altering incumbents’ access to key therapeutic segments and geographies. These discrete events create short windows of opportunity for partnerships, niche plays and defensive moves.
-
Regulatory inflection: Agencies have moved beyond stability guidance into targeted supply-chain interventions for specific products, raising the bar for compliance, traceability and localized manufacturing in certain jurisdictions.
What our PW Consulting report delivers (practical, implementation-focused)
-
Actionable scenario modeling: Four demand-supply scenarios calibrated to 2026 policy and capacity milestones, with stress tests for plasma availability, price elasticity and reimbursement shifts. Each scenario is mapped to a recommended set of commercial and operational actions.
-
Investment playbooks: Decision trees for brownfield vs. greenfield manufacturing, capacity-scaling thresholds, and modular CAPEX pathways that preserve optionality while accelerating time-to-market for new or reformulated immunoglobulins.
-
Supply resilience toolkit: Negotiation templates for long-term plasma offtake, checklist for establishing captive collection networks, and criteria for outsourcing vs. in-house fractionation under constrained plasma availability.
-
Commercial go-to-market frameworks: Segmentation-informed pricing levers, tender strategies, and channel optimization for hospital, specialty clinic and government procurement customers (note: the report preserves detailed regional and application splits for subscribers).
-
Regulatory & market-access playbook: Jurisdiction-specific entry strategies that balance local manufacturing, tech-transfer timelines and regulatory dossier priorities to reduce approval and launch risk.
-
M&A & partnership playbook: Valuation sensitivities, integration risk checklists and target profiles to prioritize bolt-on acquisitions, capacity partnerships, or minority investments aimed at securing raw-material flows or filling therapeutic gaps.
Five strategic priorities for executives in 2026
-
Secure plasma at scale and diversify sourcing. The ongoing gap in plasma collection requires immediate attention. For manufacturers, the options are to expand captive collection, enter long-term purchase agreements with independent centers, or invest in geographic diversification of donor bases. Each approach carries trade-offs between speed, cost and reputational risk; our report quantifies these trade-offs under multiple price and supply shock scenarios.
-
Prioritize capacity that enables agility over scale alone. Given demand growth but variable plasma supply, modular and flexible fractionation capacity can outperform large inflexible plants. Investments that allow rapid product mix shifts (e.g., proportioning immunoglobulin vs. albumin output) reduce allocation risk and protect margin under short-supply conditions.
-
Use targeted M&A and partnerships to bridge capability gaps. The market concentration metrics underscore that a handful of players control significant share; yet there remain attractive targets — plasma collectors, regional manufacturers and specialized contract manufacturers — that can be accretive to supply and market access. Our M&A framework ranks targets by strategic fit, integration difficulty and payback under base and downside cases.
-
Embed regulatory intelligence into product strategy. Recent regulatory moves — from targeted EMA guidance to FDA certifications of new facilities — mean regulatory timelines and supply-chain requirements must be integrated upfront into product launch plans. Strategies that de-risk supply for critical products (for instance, through redundant certified facilities or validated tech transfers) will command pricing premium and customer preference.
-
Revisit commercial segmentation and contracting. As availability tightens, commercial teams must migrate from volume-driven relationships to value-based supply partnerships: prioritized contracts, outcome-linked pricing, and multi-year agreements that include escalation clauses tied to plasma-cost indexes. These models protect both manufacturer margins and customer continuity.
Competitive landscape — how to interpret the moving pieces
The competitive field is dominated by established plasma players with integrated collection-to-manufacturing footprints and deep therapeutic portfolios. Market concentration is meaningful: the top three firms account for well over half of market share, and the top five command nearly seven in ten dollars of market revenue. This concentration creates both barriers for new entrants and opportunities for niche differentiation.
Key incumbents each have distinct strategic advantages:
-
Global integrated producers with captive collection networks leverage scale economics and secure upstream access, but face higher capital intensity and slower portfolio pivoting.
-
Regional specialists excel at local regulatory navigation and nimble launches; their appeal as partners or acquisition targets is high for firms seeking rapid market entry.
-
Specialty drug manufacturers with broader biologics portfolios can cross-leverage manufacturing platforms and commercial channels to accelerate uptake of new plasma-derived products.
Recent events illustrate these dynamics. New product approvals and launches in 2024–2025 have shifted near-term access to certain immunoglobulin formulations, while association-level governance changes in 2026 signal evolving industry coordination on supply resilience. For executives, the implication is that competitive advantage will increasingly rest on the orchestration of supply, regulatory certainty and differentiated commercial agreements — not only on product novelty.
Signals to monitor through 2026 (early-warning indicators)
-
Plasma collection volumes and donor trends regionally — watch for deviations from baseline that would tighten or relax supply constraints.
-
Regulatory advisories and targeted guidance for specific products — these create asymmetric supply risk and can trigger procurement reallocations.
-
Certification and commissioning of fractionation facilities — new FDA or EMA-certified plants materially change available capacity.
-
Notable approvals and commercial launches — newly approved products with rapid adoption can reallocate demand across existing portfolios.
-
Contracting behavior among major payers and large hospital systems — shifts toward prioritized supply agreements will pressure spot-market channels and small suppliers.
How to use this report in your 2026 planning cycle
-
Run strategic options against our four supply-demand scenarios before committing to CAPEX. Use the report’s stress-tested decision trees to preserve upside optionality and limit downside exposure.
-
Prioritize immediate supplier engagements: initiate or renegotiate long-term plasma offtake and manufacturing capacity options in the next 6–12 months to secure 2027–2029 throughput.
-
Deploy the regulatory playbook to compress approval timelines: align dossier development, tech transfer and site certification activities with jurisdiction-specific expectations described in the report.
-
Use our commercial frameworks to redesign contracting models by mid-2026 — shift a portion of volumes to prioritized, outcome- or availability-linked contracts to stabilize revenue and margin streams.
Closing perspective
The plasma protein therapeutics market is neither a simple growth story nor a zero-sum game; it is a complex, capital- and resource-constrained ecosystem where strategic foresight in 2026 will determine market positioning through 2032. With the market moving from roughly USD 29.7 billion at the 2025 base year toward an anticipated USD 43.3 billion by 2032 at a 5.6% CAGR, companies that align supply strategies, regulatory planning and commercial contracting now will capture disproportionate value.
PW Consulting’s full market study provides the granular segmentation, regional demand curves, product-level economics and executable playbooks required to make those decisions with confidence. For executives building resilient strategies in a constrained resource environment, the detailed data and tools in the full report are the difference between reactive tactics and proactive advantage.
For detailed analysis of this topic, please visit the official page: Plasma Protein Therapeutics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hydrazine Hydrate Market at USD 280.6M in 2025 — PW Consulting Market Insight
By pmarketresearch, 2026-07-09
Hydrazine Hydrate Market 2026 — Strategic Outlook and Decision Framework
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise yet substantive preview of our Hydrazine Hydrate Market research — designed specifically to inform executive decisions across procurement, R&D, regulatory affairs, and M&A in 2026. This briefing synthesizes the market’s trajectory, structural dynamics, and the practical intelligence contained in the full study. It deliberately illustrates the analytical depth you can expect while withholding detailed segment-level financial tables and proprietary model outputs — the strategic “teaser” intended to guide you to the full report for transaction- and project-critical granularity.
Hydrazine Hydrate Market
High-level market trajectory: what the numbers mean for 2026 decisions
The global hydrazine hydrate market shows a steady expansion through the mid-2020s. From a baseline that rose materially across 2020–2025, the market size reached USD 280.6 Million in our base year (2025). Under our central case assumptions the market continues to expand at a compound annual growth rate (CAGR) of approximately 5.5% across the 2026–2032 forecast window, reaching an overall valuation north of USD 400 Million by the end of the horizon. This pace is consistent with a specialty-chemicals product experiencing mixed cyclical demand — solid industrial applications balanced by regulatory and logistics frictions that constrain unfettered upside.
Hydrazine Hydrate Market
For 2026 corporate planning, this implies a market environment where demand growth is reliable but not explosive. Firms should prioritize operational resilience, selective capacity investments, and downstream partnerships that capture higher-margin specialty applications rather than broad-volume plays that assume rapid commoditization.
Hydrazine Hydrate Market
Drivers shaping near-term supply and demand
- End-market mix and downstream pull: Demand is anchored in legacy industrial uses (water treatment, polymer and foam systems, agrochemical synthesis, pharmaceutical intermediates) and is being reshaped by pockets of higher technical intensity (high-purity grades for aerospace and advanced synthesis).
- Regulatory tightening: Classification and authorization requirements in major markets (notably the EU) are raising compliance costs and influencing sourcing choices, favoring suppliers that can demonstrate robust regulatory dossiers and chain-of-custody controls.
- Logistics and handling constraints: Shipping and handling standards, including insulated pressure-rated packaging and certified handlers under international transport rules, increase landed costs and favor regional supply hubs or nearshoring strategies.
- Feedstock and input inflation: Upstream feedstock cost pressures have increased production costs materially in recent periods — a factor that constrains margin expansion unless offset by product mix optimization or pass-through pricing.
Market structure and competitive landscape — how to interpret concentration metrics
The hydrazine hydrate sector is best characterized as a specialized, moderately fragmented market. Aggregate concentration metrics show that the largest few players do not dominate the sector to the degree seen in highly consolidated commodities; instead, a handful of established chemical manufacturers, particularly those with integrated synthesis capabilities and regional production assets, capture a meaningful share while a broad tail of regional producers serves local demand.
Key industry participants whose strategies merit attention include:
- Otsuka-MGC Chemical Company, Inc. (Japan): The largest global manufacturer and the sole domestic producer in Japan; its scale and domestic footprint make it a natural price-maker for Asian flows and a critical counterparty for supply continuity in the region.
- Arkema S.A. (France): A diversified specialty-chemicals group that offers hydrazine hydrate across a range of concentrations and derivatives. Arkema’s strengths are its formulation know-how and customer relationships in polymer foam and crop protection intermediates.
- LANXESS AG (Germany): A supplier with a strong agrochemical orientation and recent strategic moves into higher-purity grades aimed at aerospace and advanced industrial applications — signaling a play for margin differentiation.
- Nippon Carbide Industries, Japan Finechem, Kanto Chemical (Japan): These firms provide a mix of regional supply, technical grades, and specialty services (e.g., analytical and technical-grade products), supporting localized supply chain needs and regulatory compliance for customers in pharmaceuticals and agrochemicals.
The competitive picture is dynamic: product-quality differentiation (e.g., high-purity, aerospace-grade variants), supply security, and regulatory readiness are increasingly salient axes of competition. Recent corporate activity — product launches targeted at high-value applications and focused trade-show engagement — underscores a strategic shift from volumetric growth to capability-led differentiation.
Regulatory, safety and logistics headwinds
Regulation is a central constraint on market development and a primary driver of supplier selection:
- Hydrazine’s inclusion as a substance of very high concern in some regulatory regimes raises the cost and time-to-market for affected uses through authorization dossiers and tighter EHS controls.
- Recent alignment of domestic rules in the United States to updated international standards created near-term compliance costs — relabeling, retraining, and revised transport protocols — with ongoing implications for cross-border supply chains.
- Transport regulations under the UN model require pressure-rated, insulated packaging and certified handlers, which limits the pool of logistics providers and raises barriers to ad hoc cross-border shipments.
Companies that prioritize regulatory compliance, invest in documented stewardship programs, and develop certified logistics footprints will reduce both operational risk and the total cost of ownership for customers, creating a defensible commercial position in 2026.
Cost pressure and margin implications
Upstream feedstock inflation has been a material margin headwind, with recent periods showing a significant rise in input costs. This forces hard choices for producers: absorb margin contraction, pursue product-mix upgrades toward higher-margin specialty grades, or pass costs through — each option has different competitive and commercial consequences. Procurement leaders should stress-test supplier contracts for indexation, hedging mechanisms, and flexibility clauses as part of sourcing decisions in 2026.
Practical content of the full PW Consulting report
Our full report is structured to support immediate decision-making and project planning. It includes:
- Proprietary demand-modeling across 2020–2032 with base-year calibration to 2025 and scenario runs that reflect regulatory, feedstock, and logistics shocks;
- Price and cost decks that reconcile raw material inputs, production OPEX, and regional logistics cost components;
- Supplier and capacity maps with facility-level commentary, permitting status, and compliance readiness;
- Applications-level demand narratives (water treatment, polymerization & blowing agents, agrochemicals, pharmaceuticals, and others) with qualitative substitution and elasticity analysis — note: detailed segment-level value tables are available in the premium dataset;
- Regulatory impact assessment and a practical compliance checklist for market entry and product stewardship programs;
- An actionable M&A and partnership playbook: screening criteria for targets, indicative valuation sensitivities given feedstock and regulatory risk, and integration checklists;
- Scenario-driven go-to-market recommendations for producers and downstream buyers, including procurement contracting templates and a supplier-risk matrix;
- Executive-ready slide sets and editable data extracts to embed in board materials or investor decks.
How to use this intelligence in 2026 — four priority actions
- For producers: prioritize investments in higher-purity product lines, regulatory dossier completion, and certified logistics to capture premium end-markets. Defer greenfield capacity focused purely on volume unless backed by long-term offtake.
- For buyers/procurement: rebalance sourcing toward suppliers that combine price competitiveness with demonstrated regulatory robustness and logistics certification; negotiate clauses that mitigate feedstock inflation through shared-index mechanisms or measured pass-throughs.
- For M&A and private equity: target niche, regionally entrenched assets with clean regulatory records and technical-grade capabilities; valuation multiples must explicitly account for authorization risk and potential capex to meet higher-purity specifications.
- For R&D and product teams: accelerate workstreams that enable substitution into higher-value applications and explore formulation strategies that reduce hydrazine load while retaining performance to avoid regulatory bottlenecks.
Risk framework — exposures to monitor
Key risks that will affect strategy in 2026 include regulatory authorization outcomes in major markets, sudden feedstock price spikes, disruptions to certified logistics capacity, and technological substitution in downstream formulations. Our report provides a quantified risk matrix and mitigation playbook tailored to each stakeholder group.
Next steps — where to find the granular intelligence
This preview outlines the strategic contours and practical imperatives that PW Consulting’s Hydrazine Hydrate Market report delivers. The full study contains the segment-level revenue tables, regional and application splits, supplier facility maps, and the proprietary scenario models that are intentionally omitted here to preserve the value of the primary dataset. For procurement tenders, M&A diligence, or capital expenditure approvals in 2026, those dataset elements are the operational inputs you will need.
Contact PW Consulting to request the complete report package, which includes editable data extracts, scenario-model access, and a one-hour briefing with our lead analysts to align the findings to your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Hydrazine Hydrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com