

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Plasma Protein Therapeutics Market to Reach USD 43.26 Billion by 2032 at 5.6% CAGR

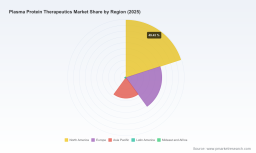
Plasma Protein Therapeutics Market — Strategic Outlook for 2026 Decision-Making
Executive summary
The plasma protein therapeutics market has transitioned from steady growth to a phase of strategic inflection. After expanding from roughly USD 22.2 billion in 2020 to about USD 29.7 billion by our 2025 base year, the sector is forecast to continue climbing to an estimated USD 43.3 billion by 2032 at a compound annual growth rate (CAGR) of approximately 5.6% across the 2026–2032 forecast window. This growth is real, durable and unevenly distributed — driven by demographic tails, rising chronic immunological indications, evolving regulatory expectations, and persistent supply-side constraints tied to plasma sourcing and concentrated manufacturing footprints.
Plasma Protein Therapeutics Market
Why this report matters for 2026 strategic choices
-
Timing of investment: 2026 is the first full planning year in which recent capacity additions, regulatory approvals and industry governance changes materially reshape supply dynamics. Decisions made this year about capacity, offtake contracts and M&A will materially affect competitiveness for the remainder of this decade.
Plasma Protein Therapeutics Market -
Risk management: The industry is operating with a persistent plasma collection gap — conservatively estimated in the single-digit millions of liters per year — which translates into higher marginal cost of goods, allocation dynamics, and strategic prioritization of indications and customers.
Plasma Protein Therapeutics Market -
Competitive repositioning: Recent product approvals and commercial launches are altering incumbents’ access to key therapeutic segments and geographies. These discrete events create short windows of opportunity for partnerships, niche plays and defensive moves.
-
Regulatory inflection: Agencies have moved beyond stability guidance into targeted supply-chain interventions for specific products, raising the bar for compliance, traceability and localized manufacturing in certain jurisdictions.
What our PW Consulting report delivers (practical, implementation-focused)
-
Actionable scenario modeling: Four demand-supply scenarios calibrated to 2026 policy and capacity milestones, with stress tests for plasma availability, price elasticity and reimbursement shifts. Each scenario is mapped to a recommended set of commercial and operational actions.
-
Investment playbooks: Decision trees for brownfield vs. greenfield manufacturing, capacity-scaling thresholds, and modular CAPEX pathways that preserve optionality while accelerating time-to-market for new or reformulated immunoglobulins.
-
Supply resilience toolkit: Negotiation templates for long-term plasma offtake, checklist for establishing captive collection networks, and criteria for outsourcing vs. in-house fractionation under constrained plasma availability.
-
Commercial go-to-market frameworks: Segmentation-informed pricing levers, tender strategies, and channel optimization for hospital, specialty clinic and government procurement customers (note: the report preserves detailed regional and application splits for subscribers).
-
Regulatory & market-access playbook: Jurisdiction-specific entry strategies that balance local manufacturing, tech-transfer timelines and regulatory dossier priorities to reduce approval and launch risk.
-
M&A & partnership playbook: Valuation sensitivities, integration risk checklists and target profiles to prioritize bolt-on acquisitions, capacity partnerships, or minority investments aimed at securing raw-material flows or filling therapeutic gaps.
Five strategic priorities for executives in 2026
-
Secure plasma at scale and diversify sourcing. The ongoing gap in plasma collection requires immediate attention. For manufacturers, the options are to expand captive collection, enter long-term purchase agreements with independent centers, or invest in geographic diversification of donor bases. Each approach carries trade-offs between speed, cost and reputational risk; our report quantifies these trade-offs under multiple price and supply shock scenarios.
-
Prioritize capacity that enables agility over scale alone. Given demand growth but variable plasma supply, modular and flexible fractionation capacity can outperform large inflexible plants. Investments that allow rapid product mix shifts (e.g., proportioning immunoglobulin vs. albumin output) reduce allocation risk and protect margin under short-supply conditions.
-
Use targeted M&A and partnerships to bridge capability gaps. The market concentration metrics underscore that a handful of players control significant share; yet there remain attractive targets — plasma collectors, regional manufacturers and specialized contract manufacturers — that can be accretive to supply and market access. Our M&A framework ranks targets by strategic fit, integration difficulty and payback under base and downside cases.
-
Embed regulatory intelligence into product strategy. Recent regulatory moves — from targeted EMA guidance to FDA certifications of new facilities — mean regulatory timelines and supply-chain requirements must be integrated upfront into product launch plans. Strategies that de-risk supply for critical products (for instance, through redundant certified facilities or validated tech transfers) will command pricing premium and customer preference.
-
Revisit commercial segmentation and contracting. As availability tightens, commercial teams must migrate from volume-driven relationships to value-based supply partnerships: prioritized contracts, outcome-linked pricing, and multi-year agreements that include escalation clauses tied to plasma-cost indexes. These models protect both manufacturer margins and customer continuity.
Competitive landscape — how to interpret the moving pieces
The competitive field is dominated by established plasma players with integrated collection-to-manufacturing footprints and deep therapeutic portfolios. Market concentration is meaningful: the top three firms account for well over half of market share, and the top five command nearly seven in ten dollars of market revenue. This concentration creates both barriers for new entrants and opportunities for niche differentiation.
Key incumbents each have distinct strategic advantages:
-
Global integrated producers with captive collection networks leverage scale economics and secure upstream access, but face higher capital intensity and slower portfolio pivoting.
-
Regional specialists excel at local regulatory navigation and nimble launches; their appeal as partners or acquisition targets is high for firms seeking rapid market entry.
-
Specialty drug manufacturers with broader biologics portfolios can cross-leverage manufacturing platforms and commercial channels to accelerate uptake of new plasma-derived products.
Recent events illustrate these dynamics. New product approvals and launches in 2024–2025 have shifted near-term access to certain immunoglobulin formulations, while association-level governance changes in 2026 signal evolving industry coordination on supply resilience. For executives, the implication is that competitive advantage will increasingly rest on the orchestration of supply, regulatory certainty and differentiated commercial agreements — not only on product novelty.
Signals to monitor through 2026 (early-warning indicators)
-
Plasma collection volumes and donor trends regionally — watch for deviations from baseline that would tighten or relax supply constraints.
-
Regulatory advisories and targeted guidance for specific products — these create asymmetric supply risk and can trigger procurement reallocations.
-
Certification and commissioning of fractionation facilities — new FDA or EMA-certified plants materially change available capacity.
-
Notable approvals and commercial launches — newly approved products with rapid adoption can reallocate demand across existing portfolios.
-
Contracting behavior among major payers and large hospital systems — shifts toward prioritized supply agreements will pressure spot-market channels and small suppliers.
How to use this report in your 2026 planning cycle
-
Run strategic options against our four supply-demand scenarios before committing to CAPEX. Use the report’s stress-tested decision trees to preserve upside optionality and limit downside exposure.
-
Prioritize immediate supplier engagements: initiate or renegotiate long-term plasma offtake and manufacturing capacity options in the next 6–12 months to secure 2027–2029 throughput.
-
Deploy the regulatory playbook to compress approval timelines: align dossier development, tech transfer and site certification activities with jurisdiction-specific expectations described in the report.
-
Use our commercial frameworks to redesign contracting models by mid-2026 — shift a portion of volumes to prioritized, outcome- or availability-linked contracts to stabilize revenue and margin streams.
Closing perspective
The plasma protein therapeutics market is neither a simple growth story nor a zero-sum game; it is a complex, capital- and resource-constrained ecosystem where strategic foresight in 2026 will determine market positioning through 2032. With the market moving from roughly USD 29.7 billion at the 2025 base year toward an anticipated USD 43.3 billion by 2032 at a 5.6% CAGR, companies that align supply strategies, regulatory planning and commercial contracting now will capture disproportionate value.
PW Consulting’s full market study provides the granular segmentation, regional demand curves, product-level economics and executable playbooks required to make those decisions with confidence. For executives building resilient strategies in a constrained resource environment, the detailed data and tools in the full report are the difference between reactive tactics and proactive advantage.
For detailed analysis of this topic, please visit the official page: Plasma Protein Therapeutics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com