

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Aramid Paper Market to Reach USD 892.38M by 2032 at 6.1% CAGR

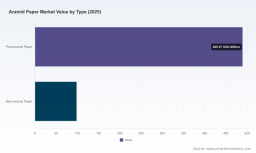
Aramid Paper Market: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a forward‑looking synthesis of the aramid paper market intended to frame executive decisions in 2026. Built on a 2025 base and a modeled forecast window through 2032, our analysis shows a resilient market trajectory—historical growth from 2020 into 2025 and a modeled compound annual growth rate (CAGR) of 6.1% across the forecast period. The study integrates primary supplier intelligence, raw‑material and regulatory dynamics, and scenario‑based financial modeling to deliver a pragmatic playbook for procurement, product strategy, and capital allocation.
Aramid Paper Market
Why this report matters in 2026
-
Market momentum: The aramid paper market has expanded materially over the past five years and is expected to continue expanding under multiple demand vectors (industrial electrification, transportation safety standards, and aerospace/high‑temperature applications). Understanding the magnitude and drivers of that expansion is necessary to prioritize investment in capacity, qualification programs, and supplier contracts.
Aramid Paper Market -
Regulatory inflection points: New European rules and global fire‑safety standards are reshaping product specifications and traceability requirements. These changes will affect product design, compliance costs, and route‑to‑market strategies for exporters and converters in 2026 and beyond.
Aramid Paper Market -
Supply‑chain sensitivity: Feedstock cost volatility and import tariff regimes are creating structural cost and availability risks. Companies that incorporate feedstock and tariff scenarios into commercial and operational planning will preserve margins and avoid disruptive shortages.
-
Competitive concentration: The industry exhibit a high level of supplier concentration, leading to structural pricing power among top producers and meaningful barriers to rapid commoditization—implications that should inform sourcing and strategic partnership decisions.
How PW Consulting’s aramid paper study is structured (practical content)
-
Executive Briefing and 60‑minute board deck for immediate use by leadership.
-
Top‑down and bottom‑up market-sizing framework (2020–2025 historical, 2026–2032 forecast) with scenario outputs (base, downside, upside) and sensitivity to feedstock and regulatory inputs.
-
Cost‑curve and margin model for producer economics that ties raw‑material price paths to finished‑product margins under multiple pricing and tariff scenarios.
-
Supplier landscaping and scorecards (capacity, route‑to‑market, technology differentiation, compliance readiness, and conversion capabilities). Note: detailed segment‑level tables and company share matrices are reserved for the full report.
-
Regulatory and standards impact map covering ecodesign/traceability, chemical registration, and transportation/fire safety test matrices—plus a compliance gap analysis and remediation roadmap.
-
Commercial playbook: procurement negotiation levers, qualification accelerators for OEMs, pricing playbooks under tariff regimes, and go‑to‑market options for converters and specialty distributors.
-
M&A and partnership shortlists with an acquisition valuation framework keyed to synergies, capacity uplift timelines, and integration risk.
-
Implementation roadmaps (90‑, 180‑, and 365‑day plans) for four typical buyer archetypes: OEMs (aerospace/transport), utilities & transformers, converters/distributors, and producers.
Competitive landscape — who matters and why
-
E. I. du Pont de Nemours and Company (DuPont) — A primary technology and brand leader, producing legacy meta‑ and para‑aramid papers (Nomex® and Kevlar®). DuPont’s recent portfolio refresh emphasizes higher thermal‑resistance grades for industrial and aerospace markets, signaling continued investment in premium product differentiation and qualification support for strategic OEMs.
-
Teijin Aramid — Vertical integration from fiber to paper gives Teijin advantages in traceability and material specification control. Their early rollout of Digital Product Passport (DPP)‑compliant products aligns them with Europe’s traceability requirements and positions them favorably with sustainability‑focused OEM procurement teams.
-
Regional Chinese producers (several leading manufacturers and converters) — These players are scaling capacity to serve domestic and regional demand with a focus on cost competitiveness and converter services. They are critical participants in Asia‑Pacific supply networks and fast qualification cycles for electrical insulation markets.
-
Kolon Industries and Japanese specialists — Offer complementary portfolios, regional customer support, and established qualifications for automotive and industrial insulation customers.
-
Converters and specialty distributors — Companies that perform slitting, die‑cutting, lamination and supply chain services provide critical customer proximity and customization, and are an increasingly strategic partner type for producers seeking to accelerate market access.
-
Market concentration metrics indicate a high degree of consolidation among the top suppliers. That concentration translates into differentiated supplier negotiation dynamics: tier‑one players can defend pricing and control capacity rollouts, while regional players compete on speed, customization, and cost.
Recent industry signals and their operational impacts
-
Product introductions and portfolio upgrades: Several leading manufacturers have introduced new grades optimized for thermal resistance or transformer/motor insulation. For decision‑makers, this raises the bar for qualification cycles and creates near‑term opportunities for product migration and premium pricing.
-
Traceability and DPP preparation: Manufacturers aligning with Digital Product Passport rules are building capabilities that will become procurement prerequisites in regulated markets by 2030. Buyers that pre‑qualify DPP‑ready suppliers avoid retrofit costs and procurement delays.
-
Feedstock pressure: Primary feedstocks remain concentrated and price swings have material short‑term effects on producer margins. Recent spot‑price upticks underscore the need for hedging strategies, long‑term supplier agreements, and alternate‑feedstock R&D investments.
-
Tariff and trade friction: Cumulative tariffs on certain imports have altered routing and landed cost dynamics in key markets. Buyers must incorporate landed‑cost and time‑to‑qualify tradeoffs into near‑term sourcing decisions rather than relying solely on unit price comparisons.
Strategic imperatives for 2026 — what companies should do now
-
Prioritize dual levers: supply security and product differentiation. For OEMs and utilities, secure multi‑source supply agreements with tiered penalty clauses and capacity carve‑outs for critical grades. For producers, accelerate premium grade commercialization and shorten OEM qualification timelines.
-
Operationalize traceability. Invest in the data, labeling and supplier audit capabilities required for Digital Product Passports and tighter chemical‑registration regimes. Early movers will capture procurement RFPs that exclude non‑DPP suppliers by design.
-
Hedge feedstock risk. Implement a blended approach: fixed‑price supply contracts for baseline volumes, spot exposure for opportunistic purchases, and targeted R&D into lower‑cost or regulated‑friendly chemistries to de‑risk long‑term feedstock constraints.
-
Reassess go‑to‑market partnerships. Producers should deepen relationships with converters and specialty distributors to accelerate localized service and qualification support. Buyers should build preferred‑supplier programs with clear escalation paths for technical failures and capacity shortfalls.
-
Embed tariffs and non‑tariff barriers into price/cost models. Model landed cost to the point of use and include qualification lag as a cost of switching suppliers—this will change the economics of near‑term reshoring vs. sourcing from low‑cost regions.
-
Use M&A as a tactical instrument. Given supplier concentration, bolt‑on acquisitions of converters or niche capacity can be the fastest way to secure market access, technological differentiation, or localized manufacturing footprints.
How to use this research in executive decision cycles
-
Board and investment committees: Use the scenario outputs and sensitivity matrices to stress‑test capex proposals and to set hurdle rates that account for feedstock and regulatory risk.
-
Procurement leaders: Convert the supplier scorecards and contractual playbooks into a 12‑ to 24‑month negotiation agenda, focusing on capacity reservation, DPP readiness, and inbound logistics contingency.
-
Product and R&D: Prioritize qualification resources on grades that unlock the highest incremental margin or defend the most strategic revenue bases (transformer, aerospace, and critical industrial segments).
-
Corporate development: Deploy the M&A target list and valuation framework to accelerate small, accretive deals that expand downstream capabilities or shorten time‑to‑market for new grades.
PW Consulting’s full publication contains the granular datasets, segment demand matrices, producer economics spreadsheets, supplier scorecards, and an implementation toolkit that operational teams can deploy immediately. This summary is designed to demonstrate the analytical depth of the study while preserving the segment‑level intelligence that underpins high‑value commercial decisions. To access the full market models, executable supplier playbooks, and the M&A shortlist that complement this executive overview, please visit the report page linked from PW Consulting’s Aramid Paper Market announcement.
For detailed analysis of this topic, please visit the official page: Aramid Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com