

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cables Market to reach USD 357.35M by 2032 at 6.3% CAGR

Cables Market 2026: Strategic Imperatives for Executive Decision‑Making
As companies calibrate strategies for 2026, the cables market is resurfacing as a critical enabler of energy transition, digital infrastructure and industrial automation. PW Consulting’s latest market study — built on a 2025 base year with a historical window from 2020–2025 and a forward-looking forecast to 2032 — provides the context and tools executives need to convert market momentum into profitable, durable advantage. The global market, which expanded steadily through the early 2020s and recorded notable acceleration into 2024–2025, is projected to continue growing at a mid-single-digit compound annual growth rate (CAGR) of 6.3% through the 2026–2032 forecast horizon.
Cables Market
Why this study matters for 2026 decisions
-
Timing of capex and capacity decisions: With market growth re‑accelerating post‑2024 and material costs under pressure, the report translates top‑line forecasts into investment timing guidance — where to defer, where to accelerate and where to right‑size capacity.
Cables Market -
Supply‑chain resilience and sourcing strategy: The confluence of commodity volatility and escalating trade measures makes procurement strategy a board‑level priority. This study models scenario outcomes — from tariff shocks to raw material squeezes — and quantifies the cost exposure of different sourcing strategies.
Cables Market -
Go‑to‑market and product prioritization: Energy transition, submarine/offshore projects, EV charging infrastructure, data centers and smart buildings each exert distinct demand profiles. Our research identifies which product architectures and value propositions are likely to deliver margin resilience versus volume play.
-
M&A and partnership playbook: As the sector remains relatively fragmented, disciplined M&A can deliver scale or niche superiority. The report provides screening criteria, precedent transactions and a prioritized list of capability gaps where partnership or acquisition would accelerate access to end markets.
What the report delivers — a practical playbook, not a catalog
PW Consulting’s Cables Market study is explicitly designed for executive action. It combines rigorous market sizing and forecasting with operationally relevant diagnostics and templates that decision‑makers can deploy immediately. Key deliverables include:
-
Top‑down market sizing and a 2026–2032 forecast built on validated demand drivers and scenario analysis; historical performance from 2020–2025 is included to ground assumptions.
-
Demand-driver decomposition across end markets (energy transmission, telecommunications, industrial and building electrification) with sensitivity matrices that help translate macro scenarios into revenue and margin outcomes.
-
Competitive landscape mapping and capability heatmaps to inform where to invest in product development, manufacturing scale or channel expansion.
-
Supply‑chain and raw‑material stress tests, including pass‑through modelling, hedging playbooks and alternative procurement routes to mitigate tariff and commodity shocks.
-
Commercial playbooks — pricing, contracting, and lifecycle services strategies — designed to protect margin under volatile input cost conditions.
-
M&A screening tools and integration planning templates targeted at rapid value capture in consolidation or capability‑access transactions.
Market dynamics shaping 2026 agendas
-
Energy transition and grid modernization: Continued investments in renewable generation, offshore wind, and grid reinforcements are structural demand drivers for high- and medium‑voltage systems. This is a multi‑year spend theme that favors firms with proven HV capabilities and project execution credentials.
-
Digital infrastructure and data centers: Surge in cloud capacity and edge deployments sustains demand for high‑performance telecom and data cabling solutions. Small‑diameter, high‑throughput products and connector ecosystems are becoming de‑facto purchasing criteria.
-
Electrification of transport and buildings: Automotive wiring harnesses, EV charging networks and smart buildings create differentiated niches. Suppliers that can bundle cables with sensors, connectors and lifecycle services capture premium positions.
-
Raw‑material and trade volatility: Copper and aluminum price dynamics, coupled with recent trade measures, have materially altered cost profiles. For example, copper price escalation and new import duties on aluminum and copper derivatives emerged as defining constraints in 2025, making procurement strategy and local content planning essential for 2026 procurement cycles.
Regulatory and trade risks — what to factor into 2026 plans
Regulatory interventions in 2025 reshaped near‑term cost and sourcing calculus. Policymakers implemented higher duties on certain aluminum and copper products and enacted measures affecting imports from key geographies. Companies must therefore model scenarios that include elevated tariffs, phased tariff escalations and the potential for further export restrictions. The PW report offers a modular risk‑adjusted financial model that allows procurement and commercial teams to stress‑test contracts and budgeting decisions under these regimes.
Competitive landscape — strategic positioning and tactical moves
The market remains competitive but not monopolistic: leading global players bring distinct strengths that create opportunities for targeted competitive plays.
-
Prysmian Group (Milan): Scale and breadth across high/medium voltage and optical fibre place Prysmian as a reference operator in large infrastructure projects. Their 2025 investments in industrial cable capacity and fibre innovation can accelerate project delivery timelines for clients seeking integrated HV and fibre solutions.
-
Nexans (Paris): A product innovation and sustainability emphasis positions Nexans well for customers prioritizing lifecycle efficiency and decarbonization. Recent industrial cable launches sharpen their offering for energy‑efficient applications.
-
NKT A/S (Copenhagen): Strong credentials in submarine and offshore wind systems make NKT a preferred partner in marine energy projects; their technical experience reduces execution risk in large subsea deployments.
-
Fujikura (Tokyo) and LS Cable & System (Anyang): Both bring complementary strengths in optical transmission and integrated energy/telecom portfolios — making them natural partners for end‑to‑end deployments in dense urban and industrial zones.
-
Leoni AG (Nuremberg): A leader in automotive wiring and harnesses, Leoni is well positioned to capture gains from vehicle electrification and factory automation, though automotive cyclicality requires different capital allocation discipline than utility projects.
-
Amphenol, TE Connectivity and Belden: These connectivity and interconnect specialists are increasingly adjacent competitors as signal integrity, sensor integration and smart‑building ecosystems become differentiators. Recent product introductions from players in the building connectivity space highlight accelerating innovation and cross‑sector competition.
For strategic buyers and partners, the implication is clear: pursue alliances that plug capability gaps — for example, pairing HV project expertise with small‑form optical specialisms or combining harness know‑how with connector and sensor ecosystems to offer bundled electrification solutions.
Practical moves recommended for 2026
-
Rebalance procurement toward diversified sourcing and index‑linked contracts to mitigate tariff and commodity shocks; where possible, pursue localized content strategies for major projects to reduce tariff exposure and shorten lead times.
-
Prioritize investments that unlock adjacent value — e.g., optical fibre and connectivity solutions that complement power product lines — rather than broad horizontal scale alone.
-
Use portfolio decomposition to identify high‑margin niches (project EPC, lifecycle services, specialist subsea work) and establish differentiated go‑to‑market models for each segment.
-
Design a two‑track M&A approach: tuck‑ins to accelerate product innovation and select platform deals to capture regional scale where execution risk is low and regulatory exposure is manageable.
-
Strengthen commercial contracts with cost‑pass‑through and indexation clauses tied to primary commodities and published tariff schedules; couple this with enhanced customer education on total lifecycle costs.
What we intentionally withhold here — and why
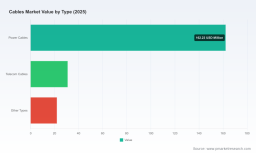
To preserve the integrity of the analysis and adhere to the “trailer” principle, this introduction intentionally avoids disclosing detailed regional or application split figures and granular segment revenue tables. The full report contains the precise segmentation by region, type and application across the historical and forecast periods, accompanied by downloadable datasets and customizable model files. Those datasets are essential for transactional diligence, precise capital budgeting and contract negotiations; they are provided in the full study so that executives can run bespoke scenarios on live numbers.
Next steps for executives
For leadership teams preparing 2026 budgets, supplier negotiations, or strategic reviews, PW Consulting recommends an immediate three‑step action plan:
-
Run the model: Use the report’s scenario templates to stress‑test your revenue and margin plans under alternative commodity and tariff outcomes.
-
Prioritize capability audits: Map your current assets against the capability heatmaps in the study to identify must‑have investments and potential partnership targets.
-
Engage on strategy: Book a briefing with PW Consulting to convert the report’s evidence into a 90‑day plan for procurement, product and M&A actions tailored to your balance sheet and risk appetite.
PW Consulting’s Cables Market study translates a complex, fast‑evolving ecosystem into actionable priorities for 2026 decision‑makers. The full report contains the datasets, segmentation tables, supplier scorecards and executable templates referenced here. For organizations that need to operationalize these insights quickly — whether to defend margins, accelerate growth or secure strategic assets — the complete intelligence package is the next step.
For detailed analysis of this topic, please visit the official page: Cables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com