

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Manual Cleaning Products Market — Strategic Outlook for 2026 Decision‑Makers
As companies plan investments and portfolio shifts for 2026, the Manual Cleaning Products Market presents a blend of steady expansion, margin pressure, and technology-driven disruption. Our PW Consulting market study (base year 2025, historical window 2020–2025, forecast 2026–2032) models this market at USD 141.7 million in 2025, up from roughly USD 110 million in 2020, and projects growth to roughly USD 197.3 million by 2032 at a compound annual growth rate (CAGR) of 4.9%. This paper distills the report’s strategic value for executives, procurement leads, BD teams, and corporate development groups in 2026 — showing where to act quickly, where to prepare, and where to wait for clearer signals.
Manual Cleaning Products Market
Why this research matters for 2026 decisions
- Investment horizon clarity: A 4.9% CAGR across 2026–2032 signals a market delivering stable top‑line expansion but not runaway growth — optimal for targeted capex and selective M&A rather than broad, high‑beta expansion programs.
- Profitability under pressure: Raw material volatility and rising frontline labor costs compress operating margins in manual cleaning operations, making cost containment, product premiumization, and service/consumables monetization immediate priorities.
- Technology and channel inflection: Hybridization of manual and automated cleaning (robotic integration, modular scrubber attachments) creates opportunities to reposition from one‑time equipment sales to recurring revenue models — particularly relevant for companies considering platform plays or subscription services.
- Regulatory and safety risk management: New and tightening rules (e.g., supplier qualification for raw ingredients, and safety advisories on equipment) require faster product compliance cycles and stronger supplier governance to avoid costly recalls or market access delays.
What the full report delivers — practical, transaction‑ready outputs
- Actionable executive summary with investment thesis and 12‑, 24‑, and 36‑month decision matrices.
- Proprietary market sizing and forecasting model (base 2025; historical 2020–2025; forecast 2026–2032) delivered in editable format, with scenario toggles for demand shocks, raw material price swings, and labor cost scenarios.
- Go‑to‑market playbooks for three strategic pathways: premium product leadership, cost‑efficient commodity supply, and recurring‑revenue services (consumables & maintenance contracts).
- Competitive landscape dossiers and strategic profiles of leading and disruptive players — including product roadmaps, distribution footprints, and partnership strategies.
- Supply chain risk register tied to raw material indices, supplier concentration maps, and mitigation options (dual sourcing, vertical integration levers, hedging strategies).
- Regulatory impact assessment and compliance checklist for European and North American market entry, plus recommended testing protocols for chemical inputs and equipment safety.
- M&A target screening criteria, valuation benchmarks, and synergy realization playbooks specific to manual cleaning product businesses and adjacent robotics/equipment firms.
- Appendices: interview transcripts with industry buyers, trade‑show intelligence harvest (Interclean 2026 observations), and sensitivity analysis supporting price and volume elasticities.
Note: this article is a strategic preview. Detailed sub‑segment tables, regional splits, and line‑item revenue figures are intentionally omitted here and are available in the full report.
Manual Cleaning Products Market
Data‑driven macro insights you can act on now
- Steady base‑market growth enables disciplined reinvestment. The market’s trajectory — from the early‑2020 baseline to the 2025 reference point and on to 2032 — supports disciplined investment into product upgrades, selective automation, and channel expansion while maintaining ROI thresholds that typical private and strategic buyers expect.
- Concentration and competitive tension. Market concentration metrics indicate a mid‑range consolidation state: the top three players do not dominate the market, and the top five capture less than half the market — a structure that favors both innovative niche propositions and bolt‑on acquisitions for growth accelerants.
- Cost and regulatory headwinds are real and actionable. Volatility in plastics and specialty polymers used for packaging and tool components directly pressures COGS, while tightened EU supplier qualification and chemical testing raise time‑to‑market for reformulations and new SKUs. These forces make supplier contracts, material substitution strategies, and compliance investments near‑term priorities.
- Labour economics push automation and service models. Frontline wages and operational overhead in many developed markets are high enough to justify upfront investments in semi‑automated or hybrid cleaning solutions when TCO and uptime benefits exceed hurdle rates.
- Trade shows and product launches are signposts for strategy. The 2026 Interclean cycle highlighted aggressive product rollouts and hybridization: leading robotics firms showcased next‑generation autonomous sweepers and heavy‑duty scrubbers, while several OEMs emphasized compact, battery‑powered manual scrubbers and modular attachments — signals that partners and competitors alike are pivoting toward integrated cleaning ecosystems.
Competitive landscape — strategic positioning of core players
The research includes focused profiles of the market’s most influential and disruptive names. Below is a high‑level synthesis of strategic posture and implications (detailed profiles are in the report):
Manual Cleaning Products Market
- FOAMit (US): Niche commercial entry‑point solutions — an example of vertical specialization around a singular hygiene function. Such focused plays can be attractive acquisition targets for equipment integrators seeking differentiated access points into facilities management contracts.
- Tornado Vacuums (Italy): Strong OEM pedigree in cylindrical scrubbers and compact battery manual scrubbers. Their recent product updates indicate an emphasis on small‑footprint applications and modularity — a defensive response to demand for flexible, low‑capex cleaning options.
- IPC Worldwide (US): Broad professional toolset provider — positioned to bundle manual accessories with larger systems, enabling cross‑sell into long‑standing service contracts.
- KUER & Chancee (China): Aggressive trade‑show presence and product breadth. These manufacturers are amplifying exports and competing on value and rapid development cycles; they are logical partners for strategic rollouts in price‑sensitive markets or OEM white‑label programs.
- Gausium (China): Robotics leader driving hybrid models — their 2026 Interclean launches of advanced autonomous scrubbers show the clear direction toward automating routine manual tasks and monetizing autonomy through software and services.
- Multi‑Clean & Seventh Generation (US): One focuses on commercial chemicals and floor care consumables; the other on biobased, eco formulations for home care. Together they illustrate the bifurcation in demand: institutional buyers seek performance and serviceability, while a growing consumer and retail channel demands sustainability claims validated by testing and supply transparency.
Recent market activity with strategic implications
- Gausium’s high‑profile Interclean 2026 showcase (including a Beetle 2.0 robotic sweeper and heavy‑duty autonomous scrubber) underlines the acceleration of autonomy investment and the need for incumbents to evaluate integration or partnership strategies.
- KUER and Chancee’s trade‑show focus on walk‑behind and high‑performance scrubbers signals intensifying competition from Chinese OEMs for global commercial contracts.
- Tornado’s compact cylindrical scrubber product refresh demonstrates continued market demand for efficient, battery‑powered manual solutions that reduce labor burden while preserving mobility and flexibility.
Priority strategic actions for 2026 (what PW Consulting would recommend)
- Immediate (0–6 months): Run a supplier risk audit tied to plastics and specialty polymers; renegotiate supply buffers and build price‑index‑linked contracts. Fast‑track product safety audits to meet latest equipment safety advisories.
- Near‑term (6–18 months): Pilot hybrid solutions that pair manual equipment with low‑cost automation or telematics to prove TCO improvements; introduce service bundles (maintenance, consumables) to stabilize recurring revenue.
- Medium term (18–36 months): Consider tuck‑ins in robotics or consumables depending on strategic intent: robotics for market leaders seeking margin expansion and defensibility; consumables for players focused on stable, high‑margin repeat business.
- Commercial levers: Move to value‑based pricing in professional channels, expand private‑label partnerships in price‑sensitive markets, and deploy digital channels for direct SMB engagement.
Methodology and confidence indicators
The full study uses a blended methodology: bottom‑up revenue aggregation from equipment, consumable, and service channels; top‑down triangulation against macro indicators; primary interviews with OEMs, distributors, and large end users; and trade‑show intelligence gathered at Interclean 2026 and other industry events. The model includes three scenario tracks (base, upside, downside) and sensitivity tests for key variables: raw material price index, frontline labor cost shifts, and adoption velocity of semi‑automated solutions. Revenue units are expressed in USD Million with 2025 as the base year.
How to use this preview
This executive preview is designed to be a decision‑oriented guide. Use it to align leadership on strategic priorities for 2026, inform procurement negotiations, frame M&A screening criteria, and guide product roadmap debates. For transaction diligence, detailed sub‑segment figures, regional revenue splits, company‑level sales estimates, and our full financial model are provided in the complete PW Consulting report. Those datasets and granular breakouts are intentionally reserved to preserve the actionable advantage for report purchasers.
To obtain the full dataset, scenario models, and company dossiers — including the granular segmentation that underpins the recommendations above — please consult the full Manual Cleaning Products Market report on the PW Consulting portal or contact our industry practice for a briefing and license options.
For detailed analysis of this topic, please visit the official page: Manual Cleaning Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electric Screwdriver Market to Hit USD 344.8M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-09
Electric Screwdriver Market 2026 — Strategic Imperatives for Executives
Executive summary
As companies plan investments and product strategies for 2026, the electric screwdriver market presents a measured yet compelling growth story anchored in electrification, ergonomics and digitalization. Our analysis shows the global market expanded from a measured base in 2020 to a base-year size of USD 215.0 Million in 2025, and is expected to grow at a compound annual growth rate (CAGR) of roughly 6.98% over the 2026–2032 forecast window — reaching an estimated USD 344.8 Million by 2032. The numbers point to a market that is large enough to attract scale players but sufficiently fragmented to reward focused strategies, differentiation through product systems and aftermarket services, and bold channel plays.
Electric Screwdriver Market
Why this report matters for 2026 decisions
Business leaders must decide where to allocate limited capital and management bandwidth in a market that combines hardware, batteries, software and services. The decision horizon for 2026 is short: procurement cycles, OEM sourcing windows and new-regulation compliance timelines compress the time to value. This market is characterized by steady volume growth, accelerating feature adoption (e.g., brushless motors, transducerized control, smart feedback), and rising non-recurring engineering (NRE) investments to meet ergonomic and safety regulations. Strategic choices in 2026 — whether to invest in an advanced cordless platform, deepen aftermarket service capabilities, or pursue M&A to consolidate capability gaps — will determine share and margin trajectories for the rest of the decade.
Electric Screwdriver Market
Market trajectory — the numbers you need to anchor decisions
-
Base year and historical context: Base year 2025 (USD 215.0 Million). The market has consistently expanded from 2020 through 2025, reflecting recovery and modernization in industrial and assembly sectors.
Electric Screwdriver Market -
Near- to mid-term outlook: Forecast period 2026–2032. At a projected CAGR of ~6.98%, the market scales to an estimated USD 344.8 Million by 2032 — indicating both volume expansion and incremental ASP (average selling price) uplift driven by tech upgrades and services.
-
Structure and concentration: The market remains relatively unconsolidated: the top-3 players account for under a quarter of the market, and the top-5 only edge above that. This low concentration (CR3 ~24.6%; CR5 ~26.2%) signals opportunity for specialist entrants and M&A for those seeking rapid footprint gains.
Key strategic implications for 2026
-
Prioritize battery and powertrain roadmaps. Cordless variants are the innovation vector: investments in higher-energy-density lithium-ion packs, Nuron-style platforms and battery-integrated services materially increase product stickiness. Expect raw-material price sensitivity (notably lithium and cobalt inputs) to remain a margin pressure point despite supply stabilization efforts.
-
Make ergonomics and vibration control a minimum spec. Regulation and end-user demand — especially in Europe and North America — are pushing vibration exposure limits and ergonomic mandates into procurement criteria. Tools that demonstrably reduce operator fatigue will command pricing power in industrial channels.
-
Move from product features to system solutions. Value migrates to systems that combine hardware, fastening intelligence (transducerized control, current-sense feedback), software telemetry and service contracts. OEMs and contract manufacturers increasingly buy into closed-loop maintenance and calibration services, not just tools.
-
Design the go-to-market for dual channels. Successful players will run differentiated propositions for industrial OEMs and for professional/commercial channels. A single SKU strategy underperforms; channel-tailored bundles and financing/leasing options accelerate adoption in capital-constrained facilities.
-
Factor regulation into product roadmaps. Compliance with EU Machinery Directive, EMC standards and updated harmonized standards is table stakes. Additionally, regional workplace safety rules (e.g., vibration exposure limits) directly impact product acceptance curves.
Competitive landscape — what incumbents are signaling
The competitive set combines legacy power-tool majors, electrification specialists and industrial fastening system providers. Each archetype signals a different playbook for 2026:
-
Bosch Power Tools — industrial ergonomics and broad-market reach: Recent product iterations emphasize dual-activation modes and clutch sophistication for delicate applications, underscoring Bosch’s strategy of packaging ergonomics with mass-market distribution.
-
Milwaukee Tool — modular battery ecosystems and high torque performance: Heavy focus on brushless motors and battery-platform lock-in suggests a path to recurring revenue via accessory ecosystems and platform-exclusive battery economics.
-
DEWALT — professional assembly productivity: DEWALT’s compact kits and multi-stage torque control target assembly applications where throughput and ease-of-use directly influence buyer decisions.
-
Makita — precision and configurability: Advanced clutch settings and auto-stop features appeal to applications where consistent torque control reduces rework and warranty exposure.
-
Ingersoll Rand — intelligent fastening: The IQi Series and transducerized offerings point to a differentiated segment: smart fastening for traceability and closed-loop quality control in manufacturing lines.
-
Hilti — premium systems and platform-driven revenues: Hilti’s high-torque, battery-platformed devices pair with strong field service and replacement-battery models, ideal for customers accepting higher TCO for uptime benefits.
-
Atlas Copco — industrial-grade control and integration: With roots in industrial tooling, their emphasis is on torque accuracy and integration into assembly-line PLCs and MES systems.
Taken together, incumbents are bifurcating into (1) high-performance industrial systems with integrated feedback and services, and (2) broad consumer/professional cordless portfolios optimized for ease-of-use and cost. New entrants should decide which lane to contest — and with what assets (software, battery platform, distribution).
Regulation, materials and channel dynamics — immediate execution risks
-
Regulatory compliance is non-negotiable. Compliance with EU Machinery and EMC directives and with harmonized IEC standards is a gating item for entry into key markets. Recent updates to vibration exposure limits increase the compliance burden and create a feature differentiation axis.
-
Batteries remain the principal commodity risk. Lithium and cobalt pricing dynamics continue to influence both cost and sourcing strategies — vertical integration and long-term offtake agreements are defensible levers for margin protection.
-
Service and calibration supply chain matters. Precision fastening tools require calibrated servicing; building a field-service network or partnering with certified distributors accelerates installations in regulated industrial settings.
Opportunities and white spaces to pursue in 2026
-
Smart fastening as a service: Offer transducerized tools plus analytics subscriptions for manufacturers that demand traceability and reduction in rework costs.
-
Battery-as-a-service and rental models: For cost-sensitive buyers, leasing battery packs or offering tool rental with maintenance increases penetration without upfront capex burdens.
-
Ergonomic differentiation for labor-constrained markets: Target ergonomically optimized products to reduce MSD (musculoskeletal disorders) risk and meet new vibration-exposure rules.
-
Channel engineering and embedded finance: Structure channel incentives and embedded financing to accelerate fleet swaps in SMEs and assembly shops.
What PW Consulting’s full report delivers — the practical toolkit
Our Electric Screwdriver Market research is designed for immediate operationalization in 2026 planning cycles. The full report provides:
-
Granular market sizing and validated 2020–2025 historicals with line-item methodology and primary-source reconciliation.
-
Scenario-based forecasts for 2026–2032 including sensitivity runs on battery-cost trajectories, regulatory shocks and channel-disruption scenarios.
-
Detailed competitive benchmarking covering product roadmaps, go-to-market models, pricing strategies, and service economics for leading incumbents.
-
Commercial playbooks for product launches, B2B sales, distribution redesign and aftermarket monetization with case studies and go/no-go decision trees.
-
Supply-chain risk maps and mitigations, including raw-material exposure heatmaps and sourcing contracting templates.
-
Regulatory and compliance tracker with implementation timelines and verification checklists for major markets.
-
Financial templates: build-your-own LCV/NPV models for platform investments, rental schemes and M&A scenarios.
-
Primary research appendices: interview transcripts, procurement tenders, and channel partner surveys that underpin our qualitative conclusions.
How to use this intelligence in 2026
-
Fast-track product-spec decisions: Use the report’s scenario outputs to prioritize battery platform investments and ergonomic features tied to regulatory timelines.
-
Align commercial metrics to service economics: Re-evaluate sales targets on a units-plus-service basis rather than hardware alone.
-
Prioritize M&A targets where they close capability gaps: Identify tuck-ins that accelerate entry into smart fastening or provide immediate channel access.
-
Negotiate upstream: Use our supply-chain heatmaps to secure long-term material offtake and lock favorable battery pricing structures.
Closing — why PW Consulting
The roadmap to leadership in the electric screwdriver market is a mix of disciplined product investment, channel orchestration and operational muscle on batteries and services. Our report marries quantitative market sizing with executable commercial playbooks and risk mitigations crafted for 2026 decision cycles. We intentionally withhold granular segmentation tables in this brief to preserve the high-value insights that reside in our full dataset and client deliverables; those datasets contain the tactical splits, regional and application-level detail, and the downloadable financial models that procurement, R&D and corporate development teams will use to convert strategy into outcomes.
Next steps
To access the full dataset, segmentation detail and the executable playbooks referenced here, visit the PW Consulting Electric Screwdriver Market overview page or contact our industry practice for a tailored briefing. For leaders who must decide where to invest in 2026, the right intelligence at this stage is not optional — it is a competitive advantage.
For detailed analysis of this topic, please visit the official page: Electric Screwdriver Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Data Center Rack Market: Strategic Readahead for 2026 Decision-Makers
As enterprises, hyperscalers, and edge providers finalize their 2026 capital and operating plans, the decisions made today about rack architecture, power distribution, and integration partners will determine cost structures, deployment speed, and innovation reach for the next decade. PW Consulting’s Data Center Rack Market study — anchored on a 2025 base year and projecting through 2032 — synthesizes market-scale projections, vendor maps, technological inflections, and executable go-to-market playbooks to equip boards and CIOs with the clarity needed for near-term choices that compound into long-term advantage.
Data Center Rack Market
Quick market snapshot (strategic takeaways)
- The market is growing at a compound annual growth rate of 8.83% over the study horizon, reflecting accelerated investment tied to AI workloads, densification, and modularization.
- At the 2025 base point the market value stands in the mid-hundreds (USD, Million unit of account); the study forecasts a clear trajectory through 2032 that reflects both cyclical and structural uplift driven by compute density and retrofit demand.
- Growth through 2032 is neither linear nor uniform: the next 12–18 months mark a tactical window where equipment choices (e.g., liquid-ready vs. air-optimized racks, integrated PDUs, modular pod strategies) materially affect TCO curves and upgrade paths.
Why 2026 is an inflection year
Multiple forces converge to make 2026 a pivotal planning horizon. First, the compute migration toward AI and high-performance workloads has raised per-rack power density expectations, changing thermal management and electrical design requirements. Second, macro energy and construction dynamics are reshaping the economics of new builds and retrofits: construction cost per MW rose sharply in the early 2020s and is expected to pressure capital intensity in 2026 unless developers adopt modular approaches. Third, regulatory scrutiny on data center energy consumption and local grid impacts is increasing at both federal and state levels — in several jurisdictions this is already influencing siting and permitting timelines. Together, these elements compress the window for making foundational decisions about rack standards, vendor partners, and deployment models.
Data Center Rack Market
Strategic imperatives for 2026 planning
- Adopt forward-compatible rack specifications. Design choices that look optimal for today’s server profiles can become bottlenecks for tomorrow’s accelerator-dense platforms. Prioritize liquid-ready mechanical design, strengthened static-load ratings, and serviceability for high-density PDUs.
- Shift from capex-only thinking to integrated capex–opex modelling. Modular pods and prefabricated rack systems often increase initial spend per MW but can compress build timelines, reduce fit-out risk, and lower lifecycle energy costs when paired with optimized cooling strategies.
- Hedge supply-chain and logistics risk. Lead times for critical rack subcomponents and expedited delivery programs are now part of procurement playbooks. Fast-ship and pre-integrated programs materially shorten construction schedules — an operational advantage in markets facing restrictions on new builds.
- Factor in regulatory contingency. Energy-focused regulations and moratoria in certain states create asymmetric risk across sites. Site selection and capacity planning should include scenario stress-tests for increased energy costs, water-use constraints, and incremental compliance capital.
- Prioritize vendor ecosystems over point-product selection. The most resilient deployments will rely on vendors who can deliver mechanical, PDU, cooling, and integration services as a coordinated offering — not just a rack chassis.
Competitive landscape — what leading vendors signal
The current vendor field blends global electrical and enclosure incumbents with IT OEMs and specialized racking manufacturers. There is clear evidence of strategic repositioning: incumbents are bundling enclosures with integrated power and cooling, pursuing acquisitions to accelerate pre-integrated modular offerings, and launching rapid-delivery programs to shorten deployment windows.
Data Center Rack Market
- Schneider Electric SE (France) — Schneider’s EcoStruxure portfolio signals a platform approach: NetShelter racks paired with high-density rack PDUs and prefabricated pod systems increasingly support direct-to-chip liquid cooling and OCP-inspired geometries. Their 2025 product launches underscore a bet on racks engineered for 1MW+ rack densities and tight OEM integration.
- Vertiv Group Corp. (United States) — Vertiv is emphasizing hybrid cooling and energy-management services tailored to AI-focused racks. Their trend analyses highlight regulatory headwinds and the need for energy-optimized rack architectures — messaging that aligns with customers seeking both performance and compliance pathways.
- Eaton Corporation plc (Ireland) — Eaton has doubled down on pre-integrated power enclosures through M&A activity, expanding its addressable footprint in modular power and multi-tenant deployments. For enterprises, Eaton’s strategy reduces integration risk when power delivery is a gating constraint.
- Rittal GmbH & Co. KG (Germany) and Legrand S.A. (France) — Both vendors continue to optimize enclosure and delivery models. Rittal’s focus on modular cooling and Legrand’s rapid-dispatch programs illustrate how logistics and modularity have become differentiators in this market.
- HPE, Dell Technologies, Cisco, IBM, Fujitsu — IT OEMs are emphasizing validated rack-and-chassis solutions that pair compute, networking, and enclosure design. These integrated stacks reduce onsite integration risk and accelerate time-to-compute for hyperscale and enterprise customers.
- nVent Electric plc — With strength in protective enclosures, nVent positions itself as a partner for critical-equipment protection and thermal management in retrofit and greenfield scenarios.
Recent vendor moves (product launches, acquisitions, and rapid-fulfillment programs) emphasize three short-term market realities: (1) vendors that offer pre-integrated, liquid-ready racks command pricing and delivery premiums; (2) consolidation and partnerships accelerate platform availability; and (3) logistics-first offerings can materially alter project schedules.
Operational and financial scenarios you must model in 2026
We recommend stress-testing plans across three scenarios: conservative (retrofit-heavy, slower new-builds), base (balanced greenfield and retrofit), and accelerated (fast hyperscale and AI-driven expansion). Key variables to model include effective rack power density, inflation-adjusted construction cost per MW, delivery lead times, and regulatory-driven curtailments. Our research highlights that increased construction costs and grid constraints materially change IRR math for greenfield projects, making modular pod strategies attractive in many cases.
What the full PW Consulting report delivers (practical highlights)
- Market sizing and demand model (2020–2025 historical base, 2026–2032 forecasts) with scenario analytics and sensitivity to density and energy-cost assumptions.
- Vendor scorecards and capability matrices mapping mechanical design, PDU integration, coolant readiness, delivery speed, and integration services.
- Supply-chain and logistics analysis, including lead-time risk heatmaps and recommendations for procurement cadence and buffer strategies.
- Regulatory and grid-impact playbook outlining siting risk mitigation, water-use alternatives, and compliance-cost estimators for state-level regimes.
- Procurement and specification toolkit: standardized RFP language, rack-spec checklists (serviceability, future-proofing, retrofit-friendliness), and CAPEX/OPEX comparators.
- Strategic growth playbook for vendors and channel partners: market entry frameworks, service-led expansion strategies, and M&A targets (where appropriate).
- Case studies that translate theory into tactical actions — how early adopters captured schedule advantage with rapid-ship rack programs, and how modular pod adopters reduced commissioning risk.
Final counsel for 2026 decision-makers
Decisions taken in 2026 should be framed as platform bets. Opt for specifications and partners that preserve upgrade optionality, compress schedule risk, and monetize service layers (monitoring, maintenance, and lifecycle upgrades). Treat rack selection not as a commodity buy but as a systems decision that connects mechanical, electrical, thermal, and logistical vectors. Given the market’s projected trajectory and the tightening interplay of regulation, construction cost, and densification, organizations that act now to standardize on liquid-ready, modular, and vendor-ecosystem-enabled architectures will gain both defensive resilience and offensive agility.
PW Consulting’s full Data Center Rack Market report contains the granular segmentation, vendor performance metrics, and executable templates you will need to convert these strategic themes into 2026 action plans. For access to the detailed splits, supplier scoring, and downloadable procurement tools, visit the report page linked from our firm’s research portal.
For detailed analysis of this topic, please visit the official page: Data Center Rack Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dry Mouth Relief Market to reach USD 1,940M by 2032 at a 6.5% CAGR
By pmarketresearch, 2026-07-09
Dry Mouth Relief Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As PW Consulting’s Senior Strategy Advisor, I present a focused preview of our comprehensive Dry Mouth Relief Market research (base year: 2025; historical window: 2020–2025; forecast: 2026–2032). The market we track—measured in USD Million—has expanded from USD 980 million in 2020 to USD 1,265 million in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 6.5% through 2032, reaching roughly USD 1,940 million by the end of the projection horizon. This preview is written to signal the report’s strategic value to boards, commercial leaders and R&D chiefs preparing decisions in 2026, while reserving the granular segmentation tables and proprietary scenario models for the full report.
Dry Mouth Relief Market
Why this market matters to corporate strategy in 2026
Dry mouth (xerostomia) is often viewed by generic oral-care planners as a niche symptomatic category. Our analysis reframes it as a cross-disciplinary growth vector that intersects consumer OTC channels, professional dental care, specialty pharmaceuticals and emerging biologics. Growth is being driven by demographic trends, polypharmacy in aging populations, heightened clinical recognition, and a step-change in regulatory and innovation dynamics that introduce both near-term market expansion and medium-term disruption.
Dry Mouth Relief Market
- Durable volume growth. At a 6.5% CAGR from the 2025 base, the market offers steady, predictable topline expansion suitable for sustaining investment in differentiated SKUs and incremental channel experiments.
- Cross-channel monetization. Opportunities span retail OTC, dental professional recommendation channels, and prescription-adjacent specialty products—each with different margin, regulation and data requirements.
- Disruption risk horizon. Gene and cell therapies and novel in-market pharmacotherapies now carry regulatory designations that can materially change the competitive landscape within a multi-year horizon.
What the PW Consulting report delivers — practical, decision‑grade outputs
Our full study is organized to convert market intelligence into immediate action. Highlights include:
Dry Mouth Relief Market
- Actionable market sizing and demand drivers: annualized market figures (2020–2032) with scenario-based forecasts calibrated to alternative clinical and regulatory outcomes.
- Go-to-market playbooks: tailored recommendations for consumer-packaged-goods (CPG) firms, dental device manufacturers, specialty pharma and biotech entrants, mapped to channel economics and reimbursement contours.
- Product and portfolio prioritization matrices: frameworks to evaluate R&D allocation between saliva substitutes, stimulants, lozenges, sprays, gels and combination offerings—ranked by commercial potential and implementation complexity.
- Pricing and margin stress-tests: sensitivity analyses showing breakeven and IRR thresholds for new product introductions under different competitive intensity and adoption speed scenarios.
- M&A and partnership scorecards: go/no-go criteria and valuation heuristics for tuck-ins, licensing deals and strategic alliances with dental networks and specialty clinics.
- Regulatory and reimbursement playbook: a concise map of current approvals, designations and certification pathways that influence time-to-market and commercialization strategy.
Note: the full report includes downloadable exhibits, granular regional and segmental datasets, and prioritized contact lists for potential partners—reserved for subscribers and corporate clients. This preview intentionally omits detailed regional or application-level percentages to focus on strategic implications; please consult the source page for the full data pack.
Competitive landscape — what incumbents and challengers are doing
The Dry Mouth Relief market sits at the intersection of large oral-care multinationals, nimble specialty firms and an active biotech frontier. Market concentration is moderate: the top three players command roughly a mid‑30% share of sales, while the top five account for close to mid‑40%—a structure that leaves room for category specialists and innovative entrants to win meaningful niches.
- Large oral-care multinationals (e.g., Colgate‑Palmolive, Procter & Gamble, Haleon): These firms leverage scale in retail distribution, brand equity and formulation platforms. Their strategic playbook focuses on line extensions, co-marketing with dental professionals, and bundling dry-mouth SKUs with broader oral-health ranges to capture incremental retail shelf space and consumer loyalty.
- Established healthcare brands (e.g., GlaxoSmithKline/Biotene, Johnson & Johnson): With recognized clinical positioning, these brands emphasize efficacy messaging, ADA or professional endorsements, and differentiated vehicles (rinses, gels, lozenges). Their strength lies in clinician acceptance and trust—critical when converting patients from symptomatic relief to repeat purchase.
- Specialists and device innovators (e.g., Parnell Pharmaceuticals, Saliwell Ltd., Saliwell’s recent SaliVance launch): These firms pursue product innovation—oral sprays, moisture support devices and targeted symptomatic technologies—that can command premium pricing in professional or specialty retail channels. Saliwell’s April 2026 SaliVance introduction underscores a trend of device hybridization and consumer-facing clinical claims.
- Oral-care niche brands and supplement players (e.g., Church & Dwight/TheraBreath, Nature’s Way, ACT Brands): These challengers pursue category consolidation via targeted innovation in lozenges, rinses and supplement formulations that appeal to consumer wellness trends.
Regulatory and scientific dynamics altering the strategic calculus
Two regulatory trends are particularly consequential for 2026 strategic planning:
- Approved systemic sialagogues and new clinical standards: The FDA’s approval of oral sialagogues (pilot approved formulations and generics) sets a predictable baseline for prescription options and creates a two-tier market where symptomatic OTC products compete with medically indicated therapies for patient mindshare and clinician recommendations.
- Breakthrough biologics and cell therapy designations: Fast Track and Breakthrough Therapy designations for novel cell and gene therapies (including a May 2025 Fast Track for a radiation‑induced xerostomia cell therapy and a March 2026 Breakthrough designation for an AAV‑based gene therapy) introduce a medium‑term disruption vector. While commercialization timelines remain multi‑year and capital‑intensive, the scientific spotlight increases investor interest and could shift premium pricing dynamics toward durable, clinic‑delivered solutions.
Additionally, the American Dental Association’s creation of a Seal of Acceptance category for products delivering temporary dry‑mouth relief elevates the importance of evidence-based claims and will influence purchasing behavior in the professional channel.
Strategic implications and recommended moves for 2026
The following strategic priorities are designed to be implementable in 2026 without requiring disclosure of our proprietary segment data (full implementation guides are in the paid report):
- Reassess portfolio balance sheets. CPG leaders should stress-test SKUs for channel profitability and consider delisting low-velocity SKUs to free up trade-space and development budgets for clinically differentiated offerings.
- Double down on professional endorsements. Earned trust (ADA seal, clinician trials) is a multiplier for conversion in the dental channel—allocate budget to short, rigorous clinical studies that meet ADA acceptance pathways.
- Build a two‑track R&D roadmap. Near-term tactics: optimize formulations and delivery vehicles (sprays, gels, lozenges) for convenience and sensory acceptance. Medium-term tactics: enter into clinical partnerships or licensing deals with biotech firms developing disease-modifying therapies to secure downstream participation in potential high‑value clinical markets.
- Prioritize channel partnerships over pure advertising. Given the professionalization of the category, partnerships with dental chains, oncology centers and specialty clinics will deliver higher-quality patient referrals than mass retail promotions alone.
- Establish M&A guardrails. Target acquisitions should either (a) add clinical credibility (device or clinical-stage asset), (b) unlock proprietary manufacturing or formulation IP, or (c) provide gateway access to specialty clinical channels. Our report includes valuation multipliers and integration checklists tailored to each case.
Near-term watchlist — triggers that should prompt strategy reassessment
Monitor these indicators closely in 2026; their evolution should force immediate strategic reassessment:
- Clinical readouts from late‑stage trials for gene or cell therapies addressing xerostomia.
- FDA actions shifting prescribing guidance for systemic sialagogues or new labeling for OTC products.
- Rapid uptake of clinically validated device offerings in dental networks (e.g., adoption rates post‑launch for products like SaliVance).
- ADA endorsement activity and expansion of the Seal of Acceptance category into complementary product claims.
Conclusion — how to use this preview
For executives planning 2026 resource allocation, the Dry Mouth Relief market represents a stable growth opportunity with nontrivial upside and strategic inflection points driven by clinical innovation and regulatory recognition. Use this preview to align cross‑functional teams around a dual agenda: defend near‑term retail and professional channels with evidence-backed SKUs; and selectively pursue strategic options—partnerships, licensing, or targeted M&A—that position the company to participate in higher-value clinical outcomes should the biotech pipeline deliver successful therapies.
For the full dataset, granular regional and segmental breakdowns, scenario models, and the operational playbooks referenced here, consult the PW Consulting report page and client portal where we publish the complete intelligence pack and Excel exhibits. The full suite contains the subsegment tables and valuation models that underpin the recommendations summarized above.
For detailed analysis of this topic, please visit the official page: Dry Mouth Relief Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Magnetic Field Sensors Market to reach USD 10,050M by 2032 at 7.5% CAGR
By pmarketresearch, 2026-07-09
Magnetic Field Sensors Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
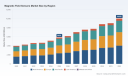
As companies set budgets and roadmaps for 2026, magnetic field sensors will continue to be a focal technology across automotive electrification and ADAS, industrial automation, consumer IoT, medical devices and specialty aerospace applications. PW Consulting’s latest market synthesis (base year: 2025; historical window: 2020–2025; forecast horizon: 2026–2032) shows the market expanding from roughly USD 4,000 Million in 2020 to USD 5,850 Million in 2025, and projected to exceed USD 10,000 Million by 2032. The underlying compound annual growth rate for the forecast period is 7.5% — a rate that reflects steady demand growth compounded with episodic supply-side and regulatory shocks.
Magnetic Field Sensors Market
Why this study matters for 2026 planning
- Data-driven prioritization: The report translates top-line momentum into actionable choices for product investment, capacity planning and procurement commitments for 2026–2028.
- Risk-aware sourcing: It juxtaposes demand drivers with supply vulnerabilities — notably magnet material and rare-earth dependence — enabling procurement teams to quantify cost and lead-time exposure before formal contract cycles.
- Competitive calibration: The analysis helps product and corporate development teams benchmark technology roadmaps (Hall, MR, TMR/GMR, AMR, MEMS and specialty SQUID solutions) against incumbent supplier strategies and emergent entrants.
Market dynamics and structural drivers
Growth in magnetic field sensing is structured by three, partly overlapping dynamics. First, the electrification and sensing requirements of modern vehicles (including current sensing, wheel/shaft angle, and redundant position sensing for safety systems) are accelerating demand for automotive-grade, high-reliability sensors. Second, pervasive automation in factories and logistics is driving industrial adoption where robustness, long-term stability and electromagnetic immunity are required. Third, the proliferation of low-power IoT endpoints and portable medical devices is creating a parallel market for ultra-low-power, high-resolution magnetometers.
Magnetic Field Sensors Market
Technology evolution is not neutral to commercial outcomes. Hall-effect devices retain a strong base owing to cost and integration, while magnetoresistive variants (AMR, GMR, TMR) are moving up the value chain where sensitivity and angular resolution matter. MEMS-based and 3D magnetometer solutions are displacing legacy architectures in specific consumer and safety-critical contexts. At the same time, specialized SQUID and fluxgate devices maintain footholds where absolute sensitivity is paramount.
Magnetic Field Sensors Market
Supply-side constraints and regulatory backdrop
A salient development requiring immediate attention is the policy-driven rebalancing of rare-earth material flows. Regulatory actions announced in 2025 changed export dynamics for certain rare-earth materials used in high-performance permanent magnets. Practically, several manufacturers experienced extended lead times and higher procurement costs in the subsequent quarters. For 2026 planning this means higher input-price volatility and an elevated probability of supply interruptions for sensor programs that rely on NdFeB or samarium-cobalt magnets.
The net operational implication for procurement and product management teams is clear: incorporate longer lead-time assumptions into NPI schedules, qualify magnet alternatives where possible, and pursue contractual instruments (e.g., price collars, committed volumes, multi-sourcing) to reduce program risk.
Competitive landscape — what to watch
The competitive field is anchored by established semiconductor and sensor specialists whose strategic plays differ by technology focus and go-to-market orientation:
- Infineon Technologies (Neubiberg, Germany): Positions its XENSIV™ family across Hall, AMR, GMR and TMR technologies with an emphasis on automotive ADAS/EV and industrial use cases that require ultra-low power and high accuracy.
- NXP Semiconductors (Eindhoven, Netherlands): Offers a broad magnetoresistive portfolio for speed/angle sensing and e-compass applications; recently launched ultra-low-power Hall solutions for IoT and medical endpoints, signaling deeper penetration into battery-operated device segments.
- Honeywell International (Charlotte, United States): Retains strength in precision AMR analog sensors for magnetometry, compassing and aerospace-grade applications — a differentiated play centered on precision and environmental tolerance.
- Allegro MicroSystems (Manchester, New Hampshire, United States): Competes on automotive-grade Hall and TMR technologies with a strong emphasis on current sensing and motion control for harsh environments.
- Texas Instruments (Dallas, United States): Focuses on integrated Hall and current-sensor TMAG series solutions, including smart concentrator designs for easier system integration.
- STMicroelectronics, Analog Devices, TDK, ams‑OSRAM and Melexis: Each pursues complementary niches — MEMS e‑compass solutions, integrated AMR angle ICs, high‑precision TMR/GMR modules, stray‑field immune position sensors and robust automotive 3D magnetometers respectively.
Collectively, top-tier suppliers represent a material concentration of industry capacity and technological leadership. Scale continues to confer advantages in R&D, qualification capability (particularly for automotive AEC‑Q and industrial standards), and the ability to invest through cyclical headwinds.
Recent signal — product innovation and its strategic implications
Product announcements through early 2026 reinforce several themes: aggressive power reduction, system-level integration, and the move toward sampled, calibrated 3D magnetometers suitable for low-energy applications. For example, new ultra‑low‑power monolithic Hall-effect devices introduced in early 2026 target battery‑powered IoT and medical devices. For corporate planners this signals a near-term bifurcation: commoditized, price‑sensitive components on one side, and higher-margin, performance-differentiated sensor ICs that demand deeper integration and stronger IP protection on the other.
What the PW Consulting report delivers (practical contents)
- Top-line market model (USD Million) from 2020–2032 with base-year granularity (2025) and scenario toggles for supply shocks and demand acceleration.
- End‑market demand modelling by application class and type, including growth vectors and adoption curves (presented at a level that enables program-level decision-making without exposing proprietary segment tables in this preview).
- Detailed supplier scorecards covering product portfolios, technology roadmaps, qualification strength, manufacturing footprint and channel reach.
- Supply‑chain map and sourcing risk assessment, highlighting critical raw material exposure and alternate sourcing routes.
- Patent and IP landscape, including white-space opportunities for differentiated sensor fusion and calibration techniques.
- Commercial playbooks: recommended go‑to-market structures, licensing vs. manufacturing decision frameworks, and three investment cases (fast follower, differentiated technology play, vertical integration).
- Downloadable Excel model and dashboard for sensitivity analysis, as well as a prioritized list of M&A and partnership targets assessed for strategic fit.
Actionable strategic recommendations for 2026
- Prioritize robustness over cost for safety‑critical automotive programs: accelerate qualification cycles now to avoid late-stage redesigns if material availability tightens.
- Diversify magnet and component supply: establish validated second- and third-sourcing options and consider long‑lead inventory agreements where justifiable by program margins.
- Invest selectively in higher‑value sensor technologies (TMR/GMR and calibrated 3D MEMS magnetometers) where differentiation drives margin and system stickiness.
- Build modular sensor platforms to shorten time-to-market across adjacent applications (industrial ↔ automotive ↔ consumer) and to facilitate cross-selling.
- Negotiate contract terms that include escalation mechanisms and supply guarantees; use hedging or forward purchasing for critical magnet materials where possible.
- Use targeted M&A or strategic partnerships to gain rapid access to niche competencies (e.g., high‑precision AMR, SQUID calibration, or low-power monolithic Hall designs).
Scenario planning — three near-term cases
- Supply Shock: Prolonged constraints on high-performance magnets drive price inflation and push customers toward magnet‑less or magnet‑light architectures. Response: accelerate qualification of alternative architectures and hedge critical inputs.
- Technology Disruption: Rapid cost declines in MEMS 3D magnetometers reduce demand for some legacy solutions. Response: pivot to higher-margin integrated sensor systems and services (calibration, fusion algorithms).
- Demand Surge: Faster-than-expected EV and industrial automation adoption increases demand for automotive-grade sensors. Response: prioritize capacity, secure long-term contracts and accelerate ramp plans with foundry/fab partners.
Concluding perspective
For executives setting strategy in 2026, magnetic field sensing is a market that rewards technical clarity, supply-chain resilience and timely commercial execution. PW Consulting’s full report converts the top-line expansion narrative into operational levers — risk-adjusted demand forecasts, supplier scoring, a materials risk register and investment-ready recommendations. This preview intentionally emphasizes trends, strategic consequences and playbooks while withholding granular segment tables and proprietary company-level metrics that are included in the full study.
To obtain the complete dataset (including the segmented forecasts, company profiles with scorecards, the downloadable financial model and the prioritized action plan for 2026–2028), please visit the PW Consulting report page for the Magnetic Field Sensors Market.
For detailed analysis of this topic, please visit the official page: Magnetic Field Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dental Loupe Market to Reach USD 400M by 2032 at 7.5% CAGR
By pmarketresearch, 2026-07-09
Dental Loupe Market: Strategic Insights for 2026 Decision‑Makers
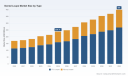
The dental loupe market has transitioned from a niche ergonomic accessory into a strategically important medical‑device category. Between 2020 and 2025 the market expanded materially, and our model — grounded in primary interviews, device adoption curves, and supply‑side cost trajectories — shows a compounded annual growth rate (CAGR) of 7.5% across the forecast horizon. Based on our baseline scenario, the market grows from the low‑hundreds of millions in 2025 toward roughly four hundred million USD by 2032. For corporate leaders making allocation, product, or M&A decisions in 2026, this research transforms anecdote and vendor pitch into quantified choices with operationally actionable next steps.
Dental Loupe Market
Why this study matters for 2026 decisions
-
Risk‑adjusted investment prioritization: The 7.5% CAGR and modeled sensitivity to regulatory and materials shocks let CFOs compare incremental R&D and manufacturing investments against alternative uses of capital within a validated medical device growth trajectory.
Dental Loupe Market -
Commercial playbook calibration: With adoption accelerating among ergonomics‑conscious clinicians and clinics with supportive reimbursement regimes, commercial leaders can tailor channel strategies (direct, distributor, clinical partnerships) to maximize uptake in high‑velocity segments.
Dental Loupe Market -
Regulatory and product roadmapping: Stricter device standards and differentiated 3D/optical classifications mean product roadmaps must balance compliance, differentiation, and time‑to‑market; our analysis translates those constraints into prioritised product scenarios for 2026 R&D calendars.
-
M&A and partnership screening: The market concentration profile and vendor archetypes help corporate development teams shortlist targets whose capabilities — e.g., optics, LED illumination, or digital imaging — unlock immediate accretive revenue or cost synergies.
What the full report delivers (practical takeaways)
-
Proprietary forecast engine: A scenario‑based model (base, upside, downside) with drivers you can toggle — adoption, replacement cycles, unit price declines, and regulatory timing — to test your investment cases through 2032.
-
Commercial segmentation framework: Buyer personas, purchase triggers, lifetime value estimates, and channel economics that convert clinical benefits (ergonomics, magnification) into sales plays and promotional ROI benchmarks.
-
Regulatory and reimbursement playbook: Practical checklists and timeframes for compliance under evolving jurisdictions, plus guidance on labelling, clinical evidence, and documentation that materially shorten approval timelines.
-
Supplier and cost analysis: Inputs‑level review of optics, LED modules, frames, and assembly costs, and a mapped view of where material price volatility creates margin pressure versus where scale generates leverage.
-
Competitive profiles and strategic options: Deep profiles of incumbent and digital‑native players, partnership fit matrices, and three validated go‑to‑market strategies tailored to different balance‑sheet positions.
Market dynamics shaping 2026 and beyond
-
Regulatory tightening: The recent Medical Devices Regulation adopted by the European Union (Feb 2025) raises the quality and documentation bar for loupes marketed in Europe; firms that rework quality systems now will realize faster approvals and reduced recall risk.
-
Technology divergence: The market is bifurcating between high‑precision optical systems and digitally enabled stereoscopic devices. The latter class, exemplified by continuous magnification and integrated imaging, benefits from favorable classification in some jurisdictions — decreasing regulatory friction for certain designs — accelerating clinical trials around workflow integration.
-
Cost and inputs pressure: High‑end optics, LED modules, and lightweight frame materials mean initial unit costs remain elevated. Manufacturers who secure differentiated suppliers or move to modular designs can protect margin while offering tiered price points to broaden adoption.
-
Occupational health as demand engine: Rising recognition of musculoskeletal disorders among clinicians is converting ergonomic benefit claims into procurement criteria for clinics and hospitals, creating a recurring replacement and upgrade dynamic rather than one‑time purchases.
-
Concentration and competitive tension: The market exhibits meaningful concentration among a handful of established players but leaves spaces for innovators and regional specialists — a structure that encourages selective M&A and strategic distribution partnerships.
Competitive landscape — how leading vendors are shaping choices
-
Designs for Vision (Bohemia, NY): Known for custom‑crafted telescopes and LED headlights, their strength lies in bespoke optical engineering and an industrialised custom‑manufacturing capability. Their recent factory transparency moves indicate a strategy to turn manufacturing quality into a commercial argument — useful for buyers who prioritize traceability and post‑sales service.
-
Orascoptic (United States): A long‑standing proponent of ergonomics, Orascoptic’s positioning emphasizes productivity and clinician performance. Their active trade show presence and professional education programs make them a benchmark for channel‑led adoption tactics oriented toward continuing education networks.
-
SurgiTel (United States): With a focus on ergonomics and user‑friendly flip‑up designs, SurgiTel appeals to clinicians seeking injury mitigation with minimal workflow disruption. Their design choices reduce the friction of clinical adoption and are a playbook for designing clinically compatible products.
-
Univet Loupes (Italy): Italian craftsmanship and premium materials define their offering. Their value proposition centers on finish, anti‑fog technology, and durability; they serve as a reminder that premiumisation remains a viable strategy where procurement is less price‑sensitive.
-
NuEyes (United States): A disruptive entrant with live 3D stereoscopic systems and continuous magnification, NuEyes represents the “digital pivot” in the category. Their product archetype highlights how imaging and ergonomics converge; regulatory classification advantages for some devices lower barriers for early commercialisation.
-
LumaDent (United States) and Admetec (United States): Both focus on ergonomics and a range of optical technologies, from Galilean to prismatic systems. Their breadth across frames, lighting, and optics shows how bundled hardware and service plays can differentiate in mature channels.
Recent events that change the landscape
-
European regulatory approval (Feb 2025) — raises the compliance bar and favours firms that invest early in documentation and quality systems.
-
Designs for Vision factory disclosures (Aug 2025) — an indicator that manufacturing transparency can be used as a commercial differentiator in tender processes and institutional sales.
-
Orascoptic’s planned AGD showcase (May 2026) — industry events remain the primary vehicle for clinician education and product trial; presence and demonstration strategy materially influence adoption curves.
Actionable strategic moves for 2026
-
Regulatory first: Prioritise MDR and equivalent filings now; lagging compliance will meaningfully extend time to revenue in regulated markets.
-
Product tiering: Move to a modular architecture that supports a low‑entry price point and premium optical/lighting modules to protect margins as commoditisation pressures expand.
-
Service and training bundle: Convert ergonomics and clinical performance claims into measurable outcomes through training programs and post‑sales analytics to increase retention and recurring revenues.
-
M&A and partnerships: Target bolt‑on optics, LED suppliers, or imaging software houses that unlock either cost reduction or differentiation. Prioritise targets that accelerate access to clinical networks or that offer scale in manufacturing.
-
Channel play: Invest in continuing education partnerships and demonstration programs in clinical societies; physical trials and peer endorsements remain higher‑impact than digital marketing alone.
-
Supply resilience: Hedge material exposures and qualify alternative suppliers for optics and LED modules to protect margin and lead times against input cost volatility.
How to use the full PW Consulting report
-
Validate your investment case by downloading the forecast model and running company‑specific scenarios.
-
Use the competitive profiles and go‑to‑market playbooks to sharpen RFP responses and distributor negotiation points.
-
Access the regulatory checklists and sample clinical evidence templates to shorten approval timelines and reduce checklist rework.
We intentionally keep certain granular splits and segment‑level revenue tables outside of this preview to preserve the commercial value of the underlying data. The full report contains region‑ and application‑level forecasts, device‑type adoption curves, and unit economics that convert the macro picture above into executable 12‑ to 36‑month plans. For teams that must make capital allocation, product roadmap, or M&A decisions in 2026, that level of resolution is the difference between a strategic leading position and reactive catch‑up.
PW Consulting’s Dental Loupe Market study is built to be directly operational: models you can run, checklists you can apply, and vendor strategies you can act on. If your 2026 plan depends on prioritised growth, regulatory certainty, and defensible commercial differentiation, the intelligence in the full report will accelerate decision quality and time to impact.
For detailed analysis of this topic, please visit the official page: Dental Loupe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wave Windsurf Sails Market to grow at 6.65% CAGR to USD 244.9M by 2032
By pmarketresearch, 2026-07-09
Wave Windsurf Sails Market: Strategic Intelligence for 2026 Decision-Making
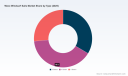
As the wave windsurfing category enters a phase of material-led performance gains and selective premiumisation, senior leaders must convert technical innovation into defensible commercial advantage. PW Consulting’s Wave Windsurf Sails Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes market-scale dynamics, product-technology vectors and competitor behaviours into a single decision-grade playbook. The global market—measured in USD million—has shown consistent expansion through the mid-2020s and is projected to grow at a compound annual growth rate of approximately 6.65% across our forecast horizon. That trajectory translates into measurable upside for market participants that align R&D, sourcing and channel strategy in 2026.
Wave Windsurf Sails Market
Why 2026 is a Pivotal Year
-
Material inflection. The mainstreaming of high-performance laminates (X‑Ply), carbon reinforcements and Dyneema/Dyneema-like Aramid fibres is lowering weight while uplifting load-bearing capacity and crash tolerance. Manufacturers who convert material gains into lighter, more durable product families will capture both rider trust and price premium.
Wave Windsurf Sails Market -
Product differentiation beyond sail shape. Leading brands are deploying different construction philosophies—continuous radial panel layouts, molded 3Di technologies, gradient panels and targeted load-distribution systems—to chase trade-offs between responsiveness, durability and ease-of-use. These technical choices have downstream implications for manufacturing complexity and serviceability.
Wave Windsurf Sails Market -
Regulatory and quality thresholds. Compliance with standards such as ISO tensile and washability protocols, together with adherence to PWA technical rules for rig components, is now table stakes for global distribution and competition at elite events. Early alignment reduces time-to-market risk in key competitive segments.
-
Channel and customer behavior shifts. Consumers explicitly demand crash-resistant constructions suitable for repeated impact — a behavior that shapes material mixes and aftermarket services (repairs, trade-in programs and protective accessories).
What the PW Consulting Report Actually Delivers (Pragmatic, Executable)
-
Robust market sizing and forecasting models: downloadable financial models (2020–2032) that translate macro growth into scenario-based unit and revenue projections by price tiers and product archetypes.
-
Commercial segmentation framework: a repeatable taxonomy that separates premium competition-grade sails from robust entry-level and hybrid freewave products, together with buyer personas and value maps used to prioritize SKUs without exposing our proprietary split tables in this preview.
-
Materials and supplier playbook: a supplier matrix that profiles laminate and fibre specialists, manufacturing dependencies, single‑sourced risk and alternative raw material pathways for cost and sustainability sensitivity testing.
-
Product and technology benchmarking: head-to-head technical matrices mapping construction methods (e.g., molded 3Di vs. radial-laminated vs. multi-batten designs), weight, claimed durability features and fit-for-purpose recommendations for diverse wave conditions.
-
Route-to-market and channel optimization: actionable steps to rebalance direct-to-consumer, specialty retail and OEM partnerships, with margin simulations and inventory cadence recommendations to reduce working capital while supporting seasonality.
-
Go/no-go investment templates: configurable decision trees for new model launches, factory upgrades (composite layup vs. thermoforming), and incremental capex with ROIC and payback sensitivity.
-
M&A targets and partnership signals: a shortlist of adjacent businesses and niche innovators whose assets (materials IP, proprietary moulds, athlete networks) accelerate market entry or defend margins.
-
Playbook for commercialization: launch calendars, field-testing protocols, athlete endorsement models and a recommended three-year product roadmap aligned to production lead times and material procurement cycles.
Competitive Landscape: Who’s Signalling What in 2026
The market reflects an active, innovation-led competitive set where category incumbents iterate rapidly and a few purpose-built specialists push technical boundaries. The following firms exemplify the distinct strategic postures found across the landscape:
-
Duotone Sports (Austria) — premium wave and freestyle focus, leveraging SLS and D/LAB constructions to deliver agility and control. Their iterative light-weighting programs indicate a continued push on weight-to-strength optimization.
-
Goya Windsurfing (United States) — performance-oriented power profiles (Banzai family) with carbon constructions aimed at bump & jump and onshore wave conditions. Recent material updates prioritize torque and range for aggressive riding styles.
-
North Sails (United States) — pioneering molded 3Di and Dyneema-infused layups for ultra-light, high-performance wave sails. Their approach signals a premium, low-volume/high-margin strategic posture.
-
GA Sails (Netherlands) — Continuous Radial Panel architectures tuned for control and responsiveness, signalling an intent to balance elite performance with broader usability.
-
Severne (New Zealand) — manoeuvre-oriented designs with layered laminate technologies (EM4) and gradient panels, emphasizing lightweight flexibility for high-turn performance.
-
NeilPryde (Hong Kong) — radial load-distribution panels in Combat and Apex lines; consistent refresh cadence indicates focus on durability under competitive stress.
-
Ezzy Sails, Point-7, Naish, Hot Sails Maui, S2Maui, Gun Sails, Maui Sails, Simmer Style, RRD — each represents a niche or complementary approach: from island-tested durability to race-derived materials and artistically positioned lifestyle products. Collectively they shape consumer expectations and pricing dynamics.
Recent market moves (late 2025 and early 2026) — product launches and range updates across several of the brands above — are more than marketing noise. They are directional indicators of where R&D budgets are being allocated, which materials are being prioritized, and how firms are segmenting their portfolios for both pros and amateurs.
Key Strategic Imperatives for 2026
-
Prioritize modular product platforms. Design modular sails and interchangeable components to reduce SKU proliferation while addressing diverse rider needs—this reduces inventory drag and accelerates product refresh cycles.
-
Lock material supply with flexible contracting. Secure primary supplies of X‑Ply, carbon tapes and Aramid yarns under indexed contracts with volume flexibility to absorb seasonality and price volatility.
-
R&D focus: damage tolerance vs. outright lightness. Decide which attribute aligns with your brand — repeated crash resistance for the enthusiast market or minimal weight for pro-level performance — and direct testing protocols accordingly.
-
Embed compliance early. Integrate PWA and ISO test benchmarks into design validation to streamline approvals for competitive channels and global retail partners.
-
Monetize services. Build repair, trade-in and certification services as margin-accretive extensions of the core product, improving lifetime value of customers.
-
Use athlete programmes strategically. Allocate athlete partnerships to accelerate adoption of new constructions, but measure ROI against conversion and product feedback velocity.
-
Assess consolidation and alliances. With the competitive field remaining neither atomized nor monopolistic, selective acquisition or technology licensing can accelerate differentiation without bearing full R&D costs.
How to Operationalize This Intelligence
-
For product teams: adopt the report’s prototype testing protocol and compare your constructions against the included benchmarking matrix to identify quick wins in weight, durability and cost.
-
For procurement: apply the supplier matrix to create a two-tier sourcing strategy (primary/secondary), and run stress-tests on lead times and pricing under the provided scenario models.
-
For commercial and finance leaders: use our financial templates to simulate three pricing strategies (premium, mid-market, value), and quantify the impact of trade-in and repair services on customer lifetime value.
Closing — The Strategic Value Proposition
The Wave Windsurf Sails market is entering a maturation step where material science, manufacturing technique and go-to-market execution determine winners. PW Consulting’s study delivers the structured foresight, repeatable models and tactical playbooks necessary to convert the market’s ~6.65% CAGR into strategic advantage in 2026. We deliberately present directional insights here while keeping proprietary segmentations, granular regional splits and the full company scorecards in the full report — the elements that operational teams need to execute with conviction.
For access to the complete datasets, interactive financial models, and the confidential company scorecards that underpin our recommendations, please consult the full Wave Windsurf Sails Market report on the PW Consulting portal.
For detailed analysis of this topic, please visit the official page: Wave Windsurf Sails Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Expanded Polypropylene Market Poised for 6.3% CAGR Through 2032
By pmarketresearch, 2026-07-09
Expanded Polypropylene (EPP) Market 2026: Strategic Imperatives for Decision Makers
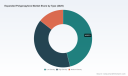
As companies plan capital allocation and portfolio moves for 2026, the expanded polypropylene (EPP) market is shifting from niche engineering-material dynamics toward mainstream industrial strategy. Our latest PW Consulting Expanded Polypropylene Market study—anchored on historical analysis (2020–2025) and a forward-looking forecast window (2026–2032)—synthesizes market sizing, demand drivers, supply-side stressors, and competitor positioning into a decision-ready playbook for executives. The report uses 2025 as the base year and models the market along a 6.3% compound annual growth rate (CAGR) through 2032.
Expanded Polypropylene Market
Why EPP deserves board-level attention in 2026
-
Macro growth trajectory. After a period of modest volatility through 2020–2025, the market is projected to resume durable expansion through the 2026–2032 forecast. The total market—measured in revenue terms—reflects a clear expansion path from the 2025 base year toward near-term and medium-term targets consistent with the stated CAGR. This growth trajectory signals substantive demand opportunity for manufacturers, OEMs, and investors seeking exposure to lightweighting and sustainable packaging plays.
Expanded Polypropylene Market -
Structural demand drivers. Three structural trends are converging to lift EPP demand: automotive lightweighting and interior redesign, an acceleration of protective and high-performance packaging needs across e-commerce and electronics, and more stringent building-insulation and circularity requirements. These drivers are not transient; they respond to regulatory, cost, and product-performance imperatives that persist into the next decade.
Expanded Polypropylene Market -
Risk-reward asymmetry. Supply-side stressors—ranging from polymer supply disruptions to evolving trade and carbon-adjustment mechanisms—are raising short-term volatility while improving long-term margins for geographically agile and vertically integrated players. For strategic planners, 2026 will be a timing decision: invest now to capture share as the market reaccelerates, or wait for clarity at the cost of higher entry barriers.
What the PW Consulting study delivers (practical content summary)
-
Top-down market sizing and a granular forecasting engine that models demand across the 2026–2032 horizon, integrating scenario-based elasticity for price, raw-material shocks, and regulation impacts. (Note: detailed regional and application splits are reserved for the full report.)
-
Value-chain heat maps and margin waterfalls that reveal where value accrues—from bead production to molding, fabrication, and aftermarket services—together with unit-cost curves and breakeven analyses for greenfield lines versus retrofit projects.
-
Regulatory and sustainability playbooks, including certification pathways for recycled polypropylene grades, compliance cost vectors, and a roadmap to monetize eco-credentials in B2B contracting.
-
Commercial go-to-market tools: supplier selection scorecards, customer-segmentation matrices for prioritization, and channel strategies for molded parts versus bead sales.
-
M&A & partnership diagnostics: target screening filters, synergy assessment templates, and integration checklists tailored to EPP businesses.
Market dynamics to factor into 2026 planning
-
Raw-material volatility and supply interruptions. Polymer feedstock availability and pricing dynamics have moved to the top of the risk register for EPP players. Recent supply constraints and outages elevated cost and delivery risk for finished beads and molded components. Any procurement strategy in 2026 must be paired with scenario modeling for prolonged supply tightness and rapid-price cycles.
-
Regulatory cost pass-throughs. Emerging trade and carbon-related mechanisms continue to change the landed cost calculus for imported materials. Companies that fail to model carbon-related border costs and the timing of compliance will misprice tenders and investments.
-
Sustainability and circularity as commercial differentiators. Tighter recycling and circularity regulations in major markets are increasing demand for certified recycled polypropylene grades—but they are also raising qualification and compliance costs. Firms that invest early in recycled-grade qualification (and can demonstrate life-cycle benefits) will capture premium customer mandates and long-term contracts.
-
Concentration and the competitive squeeze. The market demonstrates meaningful concentration at the top—three- and five-firm concentration metrics indicate that leading players control the majority of the market. This shapes pricing power, capacity planning, and partnership dynamics; smaller players must choose between niche specialization, regional defense, or integration with larger platforms.
Competitive landscape — who matters and why
The EPP competitive field includes global incumbents with integrated bead and molding platforms, regional specialists that command local OEM relationships, and emerging entrants focused on sustainable materials. The Pw Consulting report profiles the key players and recent strategic moves that have changed the competitive map.
-
JSP Corporation (Tokyo, Japan) — a global leader known for proprietary bead technology and broad application coverage across automotive and construction. Recent European capacity expansion underscores the company's play for construction-sector demand.
-
Knauf Industries (Iphofen, Germany) — a specialist with strong molded-component capabilities, particularly in protective packaging and automotive interiors.
-
Schaumaplast Group (Reilingen, Germany) — German-engineering excellence in custom molded blocks and industrial packaging solutions, with deep OEM integration.
-
Engineered Foam Products Ltd (UK) — regional strength in fabrication and application-specific engineering for packaging and construction systems.
-
Hanwha Advanced Materials (South Korea) — an upstream supplier focusing on automotive lightweighting and high-performance interior components.
-
Regional players in India and North America — including K. Nag Private Limited, Polypropylene Chemicals & Engineering, Bradford Company, and The Foam Factory — provide custom fabrication and localized service models that appeal to cost-sensitive or time-to-market–driven buyers.
Notable recent developments captured in our intelligence set: capacity additions by global suppliers in Europe and North America, strategic partnerships targeting automotive interior innovation, and new product introductions aimed at biodegradable or lower-carbon EPP grades. These moves should be treated as directional signals for market consolidation and product premiumization.
Strategic imperatives for 2026
-
Reassess procurement and hedging. Build multi-tiered supplier contracts that combine volume commitments with flex options and regional backstops. Consider long-term off-take with upstream resin producers or blended recycled-resin agreements to stabilize input cost and availability.
-
Prioritize certification and circularity. Allocate targeted investment to qualify recycled polypropylene grades, and develop product passports and LCA documentation that will be required by major customers and regulatory authorities.
-
Calibrate capacity and location decisions to demand micro-clusters. Use our region- and application-aware demand engine to optimize footprint choices: greenfield capacity should be justified against flexible molding capacity, contract manufacturing, or local partnerships.
-
Adopt modular product architectures. Focus R&D and commercial efforts on modular EPP designs that reduce tooling cycles, enable rapid customization, and increase reuse in returnable packaging programs.
-
Scan M&A pockets for capability—especially in recycling, specialty molding, and software-enabled supply-chain traceability. Small bolt-ons with strong OEM access or recycled-material know-how are high ROI targets in the current cycle.
Decision-support tools included in the full study
-
Scenario financial models that estimate NPV, IRR, and payback across conservative, base, and aggressive adoption scenarios tied to the 6.3% CAGR baseline.
-
Supplier and technology scorecards with weighted criteria for cost, lead time, sustainability readiness, and integration risk.
-
Commercial tender templates and cost-plus pricing frameworks that account for carbon adjustments and input cost pass-through mechanisms.
-
Deal diligence checklists for platform, tuck-in, and cross-border acquisitions—designed to accelerate execution while preserving value.
Conclusion — the 2026 strategic choice
For executives shaping strategy in 2026, EPP represents a convergent opportunity: technology-led performance benefits intersect with regulatory and commercial drivers that reward scale, sustainability, and supply-chain agility. Our analysis shows a market on an upward trajectory from the 2025 base—supported by robust demand fundamentals and a forecast path consistent with a mid-single-digit CAGR through 2032. However, near-term supply shocks, evolving trade and carbon regimes, and concentration among leading suppliers mean that careful timing and execution of investments will determine winners.
PW Consulting's full Expanded Polypropylene Market report provides the granular segmentation, regional and application-level forecasts, supplier matrices, and actionable tools required to make those timing and investment decisions with confidence. For access to the detailed tables, scenario outputs, and custom advisory packages, please consult the full report on the PW Consulting portal.
For detailed analysis of this topic, please visit the official page: Expanded Polypropylene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com