

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dry Mouth Relief Market to reach USD 1,940M by 2032 at a 6.5% CAGR

Dry Mouth Relief Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
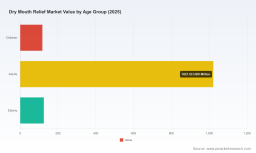
As PW Consulting’s Senior Strategy Advisor, I present a focused preview of our comprehensive Dry Mouth Relief Market research (base year: 2025; historical window: 2020–2025; forecast: 2026–2032). The market we track—measured in USD Million—has expanded from USD 980 million in 2020 to USD 1,265 million in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 6.5% through 2032, reaching roughly USD 1,940 million by the end of the projection horizon. This preview is written to signal the report’s strategic value to boards, commercial leaders and R&D chiefs preparing decisions in 2026, while reserving the granular segmentation tables and proprietary scenario models for the full report.
Dry Mouth Relief Market
Why this market matters to corporate strategy in 2026
Dry mouth (xerostomia) is often viewed by generic oral-care planners as a niche symptomatic category. Our analysis reframes it as a cross-disciplinary growth vector that intersects consumer OTC channels, professional dental care, specialty pharmaceuticals and emerging biologics. Growth is being driven by demographic trends, polypharmacy in aging populations, heightened clinical recognition, and a step-change in regulatory and innovation dynamics that introduce both near-term market expansion and medium-term disruption.
Dry Mouth Relief Market
- Durable volume growth. At a 6.5% CAGR from the 2025 base, the market offers steady, predictable topline expansion suitable for sustaining investment in differentiated SKUs and incremental channel experiments.
- Cross-channel monetization. Opportunities span retail OTC, dental professional recommendation channels, and prescription-adjacent specialty products—each with different margin, regulation and data requirements.
- Disruption risk horizon. Gene and cell therapies and novel in-market pharmacotherapies now carry regulatory designations that can materially change the competitive landscape within a multi-year horizon.
What the PW Consulting report delivers — practical, decision‑grade outputs
Our full study is organized to convert market intelligence into immediate action. Highlights include:
Dry Mouth Relief Market
- Actionable market sizing and demand drivers: annualized market figures (2020–2032) with scenario-based forecasts calibrated to alternative clinical and regulatory outcomes.
- Go-to-market playbooks: tailored recommendations for consumer-packaged-goods (CPG) firms, dental device manufacturers, specialty pharma and biotech entrants, mapped to channel economics and reimbursement contours.
- Product and portfolio prioritization matrices: frameworks to evaluate R&D allocation between saliva substitutes, stimulants, lozenges, sprays, gels and combination offerings—ranked by commercial potential and implementation complexity.
- Pricing and margin stress-tests: sensitivity analyses showing breakeven and IRR thresholds for new product introductions under different competitive intensity and adoption speed scenarios.
- M&A and partnership scorecards: go/no-go criteria and valuation heuristics for tuck-ins, licensing deals and strategic alliances with dental networks and specialty clinics.
- Regulatory and reimbursement playbook: a concise map of current approvals, designations and certification pathways that influence time-to-market and commercialization strategy.
Note: the full report includes downloadable exhibits, granular regional and segmental datasets, and prioritized contact lists for potential partners—reserved for subscribers and corporate clients. This preview intentionally omits detailed regional or application-level percentages to focus on strategic implications; please consult the source page for the full data pack.
Competitive landscape — what incumbents and challengers are doing
The Dry Mouth Relief market sits at the intersection of large oral-care multinationals, nimble specialty firms and an active biotech frontier. Market concentration is moderate: the top three players command roughly a mid‑30% share of sales, while the top five account for close to mid‑40%—a structure that leaves room for category specialists and innovative entrants to win meaningful niches.
- Large oral-care multinationals (e.g., Colgate‑Palmolive, Procter & Gamble, Haleon): These firms leverage scale in retail distribution, brand equity and formulation platforms. Their strategic playbook focuses on line extensions, co-marketing with dental professionals, and bundling dry-mouth SKUs with broader oral-health ranges to capture incremental retail shelf space and consumer loyalty.
- Established healthcare brands (e.g., GlaxoSmithKline/Biotene, Johnson & Johnson): With recognized clinical positioning, these brands emphasize efficacy messaging, ADA or professional endorsements, and differentiated vehicles (rinses, gels, lozenges). Their strength lies in clinician acceptance and trust—critical when converting patients from symptomatic relief to repeat purchase.
- Specialists and device innovators (e.g., Parnell Pharmaceuticals, Saliwell Ltd., Saliwell’s recent SaliVance launch): These firms pursue product innovation—oral sprays, moisture support devices and targeted symptomatic technologies—that can command premium pricing in professional or specialty retail channels. Saliwell’s April 2026 SaliVance introduction underscores a trend of device hybridization and consumer-facing clinical claims.
- Oral-care niche brands and supplement players (e.g., Church & Dwight/TheraBreath, Nature’s Way, ACT Brands): These challengers pursue category consolidation via targeted innovation in lozenges, rinses and supplement formulations that appeal to consumer wellness trends.
Regulatory and scientific dynamics altering the strategic calculus
Two regulatory trends are particularly consequential for 2026 strategic planning:
- Approved systemic sialagogues and new clinical standards: The FDA’s approval of oral sialagogues (pilot approved formulations and generics) sets a predictable baseline for prescription options and creates a two-tier market where symptomatic OTC products compete with medically indicated therapies for patient mindshare and clinician recommendations.
- Breakthrough biologics and cell therapy designations: Fast Track and Breakthrough Therapy designations for novel cell and gene therapies (including a May 2025 Fast Track for a radiation‑induced xerostomia cell therapy and a March 2026 Breakthrough designation for an AAV‑based gene therapy) introduce a medium‑term disruption vector. While commercialization timelines remain multi‑year and capital‑intensive, the scientific spotlight increases investor interest and could shift premium pricing dynamics toward durable, clinic‑delivered solutions.
Additionally, the American Dental Association’s creation of a Seal of Acceptance category for products delivering temporary dry‑mouth relief elevates the importance of evidence-based claims and will influence purchasing behavior in the professional channel.
Strategic implications and recommended moves for 2026
The following strategic priorities are designed to be implementable in 2026 without requiring disclosure of our proprietary segment data (full implementation guides are in the paid report):
- Reassess portfolio balance sheets. CPG leaders should stress-test SKUs for channel profitability and consider delisting low-velocity SKUs to free up trade-space and development budgets for clinically differentiated offerings.
- Double down on professional endorsements. Earned trust (ADA seal, clinician trials) is a multiplier for conversion in the dental channel—allocate budget to short, rigorous clinical studies that meet ADA acceptance pathways.
- Build a two‑track R&D roadmap. Near-term tactics: optimize formulations and delivery vehicles (sprays, gels, lozenges) for convenience and sensory acceptance. Medium-term tactics: enter into clinical partnerships or licensing deals with biotech firms developing disease-modifying therapies to secure downstream participation in potential high‑value clinical markets.
- Prioritize channel partnerships over pure advertising. Given the professionalization of the category, partnerships with dental chains, oncology centers and specialty clinics will deliver higher-quality patient referrals than mass retail promotions alone.
- Establish M&A guardrails. Target acquisitions should either (a) add clinical credibility (device or clinical-stage asset), (b) unlock proprietary manufacturing or formulation IP, or (c) provide gateway access to specialty clinical channels. Our report includes valuation multipliers and integration checklists tailored to each case.
Near-term watchlist — triggers that should prompt strategy reassessment
Monitor these indicators closely in 2026; their evolution should force immediate strategic reassessment:
- Clinical readouts from late‑stage trials for gene or cell therapies addressing xerostomia.
- FDA actions shifting prescribing guidance for systemic sialagogues or new labeling for OTC products.
- Rapid uptake of clinically validated device offerings in dental networks (e.g., adoption rates post‑launch for products like SaliVance).
- ADA endorsement activity and expansion of the Seal of Acceptance category into complementary product claims.
Conclusion — how to use this preview
For executives planning 2026 resource allocation, the Dry Mouth Relief market represents a stable growth opportunity with nontrivial upside and strategic inflection points driven by clinical innovation and regulatory recognition. Use this preview to align cross‑functional teams around a dual agenda: defend near‑term retail and professional channels with evidence-backed SKUs; and selectively pursue strategic options—partnerships, licensing, or targeted M&A—that position the company to participate in higher-value clinical outcomes should the biotech pipeline deliver successful therapies.
For the full dataset, granular regional and segmental breakdowns, scenario models, and the operational playbooks referenced here, consult the PW Consulting report page and client portal where we publish the complete intelligence pack and Excel exhibits. The full suite contains the subsegment tables and valuation models that underpin the recommendations summarized above.
For detailed analysis of this topic, please visit the official page: Dry Mouth Relief Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com