

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Magnetic Field Sensors Market to reach USD 10,050M by 2032 at 7.5% CAGR

Magnetic Field Sensors Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
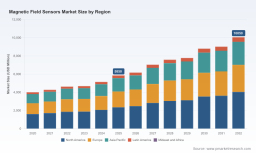
As companies set budgets and roadmaps for 2026, magnetic field sensors will continue to be a focal technology across automotive electrification and ADAS, industrial automation, consumer IoT, medical devices and specialty aerospace applications. PW Consulting’s latest market synthesis (base year: 2025; historical window: 2020–2025; forecast horizon: 2026–2032) shows the market expanding from roughly USD 4,000 Million in 2020 to USD 5,850 Million in 2025, and projected to exceed USD 10,000 Million by 2032. The underlying compound annual growth rate for the forecast period is 7.5% — a rate that reflects steady demand growth compounded with episodic supply-side and regulatory shocks.
Magnetic Field Sensors Market
Why this study matters for 2026 planning
- Data-driven prioritization: The report translates top-line momentum into actionable choices for product investment, capacity planning and procurement commitments for 2026–2028.
- Risk-aware sourcing: It juxtaposes demand drivers with supply vulnerabilities — notably magnet material and rare-earth dependence — enabling procurement teams to quantify cost and lead-time exposure before formal contract cycles.
- Competitive calibration: The analysis helps product and corporate development teams benchmark technology roadmaps (Hall, MR, TMR/GMR, AMR, MEMS and specialty SQUID solutions) against incumbent supplier strategies and emergent entrants.
Market dynamics and structural drivers
Growth in magnetic field sensing is structured by three, partly overlapping dynamics. First, the electrification and sensing requirements of modern vehicles (including current sensing, wheel/shaft angle, and redundant position sensing for safety systems) are accelerating demand for automotive-grade, high-reliability sensors. Second, pervasive automation in factories and logistics is driving industrial adoption where robustness, long-term stability and electromagnetic immunity are required. Third, the proliferation of low-power IoT endpoints and portable medical devices is creating a parallel market for ultra-low-power, high-resolution magnetometers.
Magnetic Field Sensors Market
Technology evolution is not neutral to commercial outcomes. Hall-effect devices retain a strong base owing to cost and integration, while magnetoresistive variants (AMR, GMR, TMR) are moving up the value chain where sensitivity and angular resolution matter. MEMS-based and 3D magnetometer solutions are displacing legacy architectures in specific consumer and safety-critical contexts. At the same time, specialized SQUID and fluxgate devices maintain footholds where absolute sensitivity is paramount.
Magnetic Field Sensors Market
Supply-side constraints and regulatory backdrop
A salient development requiring immediate attention is the policy-driven rebalancing of rare-earth material flows. Regulatory actions announced in 2025 changed export dynamics for certain rare-earth materials used in high-performance permanent magnets. Practically, several manufacturers experienced extended lead times and higher procurement costs in the subsequent quarters. For 2026 planning this means higher input-price volatility and an elevated probability of supply interruptions for sensor programs that rely on NdFeB or samarium-cobalt magnets.
The net operational implication for procurement and product management teams is clear: incorporate longer lead-time assumptions into NPI schedules, qualify magnet alternatives where possible, and pursue contractual instruments (e.g., price collars, committed volumes, multi-sourcing) to reduce program risk.
Competitive landscape — what to watch
The competitive field is anchored by established semiconductor and sensor specialists whose strategic plays differ by technology focus and go-to-market orientation:
- Infineon Technologies (Neubiberg, Germany): Positions its XENSIV™ family across Hall, AMR, GMR and TMR technologies with an emphasis on automotive ADAS/EV and industrial use cases that require ultra-low power and high accuracy.
- NXP Semiconductors (Eindhoven, Netherlands): Offers a broad magnetoresistive portfolio for speed/angle sensing and e-compass applications; recently launched ultra-low-power Hall solutions for IoT and medical endpoints, signaling deeper penetration into battery-operated device segments.
- Honeywell International (Charlotte, United States): Retains strength in precision AMR analog sensors for magnetometry, compassing and aerospace-grade applications — a differentiated play centered on precision and environmental tolerance.
- Allegro MicroSystems (Manchester, New Hampshire, United States): Competes on automotive-grade Hall and TMR technologies with a strong emphasis on current sensing and motion control for harsh environments.
- Texas Instruments (Dallas, United States): Focuses on integrated Hall and current-sensor TMAG series solutions, including smart concentrator designs for easier system integration.
- STMicroelectronics, Analog Devices, TDK, ams‑OSRAM and Melexis: Each pursues complementary niches — MEMS e‑compass solutions, integrated AMR angle ICs, high‑precision TMR/GMR modules, stray‑field immune position sensors and robust automotive 3D magnetometers respectively.
Collectively, top-tier suppliers represent a material concentration of industry capacity and technological leadership. Scale continues to confer advantages in R&D, qualification capability (particularly for automotive AEC‑Q and industrial standards), and the ability to invest through cyclical headwinds.
Recent signal — product innovation and its strategic implications
Product announcements through early 2026 reinforce several themes: aggressive power reduction, system-level integration, and the move toward sampled, calibrated 3D magnetometers suitable for low-energy applications. For example, new ultra‑low‑power monolithic Hall-effect devices introduced in early 2026 target battery‑powered IoT and medical devices. For corporate planners this signals a near-term bifurcation: commoditized, price‑sensitive components on one side, and higher-margin, performance-differentiated sensor ICs that demand deeper integration and stronger IP protection on the other.
What the PW Consulting report delivers (practical contents)
- Top-line market model (USD Million) from 2020–2032 with base-year granularity (2025) and scenario toggles for supply shocks and demand acceleration.
- End‑market demand modelling by application class and type, including growth vectors and adoption curves (presented at a level that enables program-level decision-making without exposing proprietary segment tables in this preview).
- Detailed supplier scorecards covering product portfolios, technology roadmaps, qualification strength, manufacturing footprint and channel reach.
- Supply‑chain map and sourcing risk assessment, highlighting critical raw material exposure and alternate sourcing routes.
- Patent and IP landscape, including white-space opportunities for differentiated sensor fusion and calibration techniques.
- Commercial playbooks: recommended go‑to-market structures, licensing vs. manufacturing decision frameworks, and three investment cases (fast follower, differentiated technology play, vertical integration).
- Downloadable Excel model and dashboard for sensitivity analysis, as well as a prioritized list of M&A and partnership targets assessed for strategic fit.
Actionable strategic recommendations for 2026
- Prioritize robustness over cost for safety‑critical automotive programs: accelerate qualification cycles now to avoid late-stage redesigns if material availability tightens.
- Diversify magnet and component supply: establish validated second- and third-sourcing options and consider long‑lead inventory agreements where justifiable by program margins.
- Invest selectively in higher‑value sensor technologies (TMR/GMR and calibrated 3D MEMS magnetometers) where differentiation drives margin and system stickiness.
- Build modular sensor platforms to shorten time-to-market across adjacent applications (industrial ↔ automotive ↔ consumer) and to facilitate cross-selling.
- Negotiate contract terms that include escalation mechanisms and supply guarantees; use hedging or forward purchasing for critical magnet materials where possible.
- Use targeted M&A or strategic partnerships to gain rapid access to niche competencies (e.g., high‑precision AMR, SQUID calibration, or low-power monolithic Hall designs).
Scenario planning — three near-term cases
- Supply Shock: Prolonged constraints on high-performance magnets drive price inflation and push customers toward magnet‑less or magnet‑light architectures. Response: accelerate qualification of alternative architectures and hedge critical inputs.
- Technology Disruption: Rapid cost declines in MEMS 3D magnetometers reduce demand for some legacy solutions. Response: pivot to higher-margin integrated sensor systems and services (calibration, fusion algorithms).
- Demand Surge: Faster-than-expected EV and industrial automation adoption increases demand for automotive-grade sensors. Response: prioritize capacity, secure long-term contracts and accelerate ramp plans with foundry/fab partners.
Concluding perspective
For executives setting strategy in 2026, magnetic field sensing is a market that rewards technical clarity, supply-chain resilience and timely commercial execution. PW Consulting’s full report converts the top-line expansion narrative into operational levers — risk-adjusted demand forecasts, supplier scoring, a materials risk register and investment-ready recommendations. This preview intentionally emphasizes trends, strategic consequences and playbooks while withholding granular segment tables and proprietary company-level metrics that are included in the full study.
To obtain the complete dataset (including the segmented forecasts, company profiles with scorecards, the downloadable financial model and the prioritized action plan for 2026–2028), please visit the PW Consulting report page for the Magnetic Field Sensors Market.
For detailed analysis of this topic, please visit the official page: Magnetic Field Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com