

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dental Loupe Market to Reach USD 400M by 2032 at 7.5% CAGR

Dental Loupe Market: Strategic Insights for 2026 Decision‑Makers
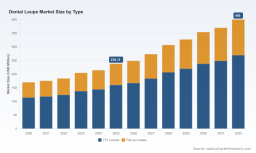
The dental loupe market has transitioned from a niche ergonomic accessory into a strategically important medical‑device category. Between 2020 and 2025 the market expanded materially, and our model — grounded in primary interviews, device adoption curves, and supply‑side cost trajectories — shows a compounded annual growth rate (CAGR) of 7.5% across the forecast horizon. Based on our baseline scenario, the market grows from the low‑hundreds of millions in 2025 toward roughly four hundred million USD by 2032. For corporate leaders making allocation, product, or M&A decisions in 2026, this research transforms anecdote and vendor pitch into quantified choices with operationally actionable next steps.
Dental Loupe Market
Why this study matters for 2026 decisions
-
Risk‑adjusted investment prioritization: The 7.5% CAGR and modeled sensitivity to regulatory and materials shocks let CFOs compare incremental R&D and manufacturing investments against alternative uses of capital within a validated medical device growth trajectory.
Dental Loupe Market -
Commercial playbook calibration: With adoption accelerating among ergonomics‑conscious clinicians and clinics with supportive reimbursement regimes, commercial leaders can tailor channel strategies (direct, distributor, clinical partnerships) to maximize uptake in high‑velocity segments.
Dental Loupe Market -
Regulatory and product roadmapping: Stricter device standards and differentiated 3D/optical classifications mean product roadmaps must balance compliance, differentiation, and time‑to‑market; our analysis translates those constraints into prioritised product scenarios for 2026 R&D calendars.
-
M&A and partnership screening: The market concentration profile and vendor archetypes help corporate development teams shortlist targets whose capabilities — e.g., optics, LED illumination, or digital imaging — unlock immediate accretive revenue or cost synergies.
What the full report delivers (practical takeaways)
-
Proprietary forecast engine: A scenario‑based model (base, upside, downside) with drivers you can toggle — adoption, replacement cycles, unit price declines, and regulatory timing — to test your investment cases through 2032.
-
Commercial segmentation framework: Buyer personas, purchase triggers, lifetime value estimates, and channel economics that convert clinical benefits (ergonomics, magnification) into sales plays and promotional ROI benchmarks.
-
Regulatory and reimbursement playbook: Practical checklists and timeframes for compliance under evolving jurisdictions, plus guidance on labelling, clinical evidence, and documentation that materially shorten approval timelines.
-
Supplier and cost analysis: Inputs‑level review of optics, LED modules, frames, and assembly costs, and a mapped view of where material price volatility creates margin pressure versus where scale generates leverage.
-
Competitive profiles and strategic options: Deep profiles of incumbent and digital‑native players, partnership fit matrices, and three validated go‑to‑market strategies tailored to different balance‑sheet positions.
Market dynamics shaping 2026 and beyond
-
Regulatory tightening: The recent Medical Devices Regulation adopted by the European Union (Feb 2025) raises the quality and documentation bar for loupes marketed in Europe; firms that rework quality systems now will realize faster approvals and reduced recall risk.
-
Technology divergence: The market is bifurcating between high‑precision optical systems and digitally enabled stereoscopic devices. The latter class, exemplified by continuous magnification and integrated imaging, benefits from favorable classification in some jurisdictions — decreasing regulatory friction for certain designs — accelerating clinical trials around workflow integration.
-
Cost and inputs pressure: High‑end optics, LED modules, and lightweight frame materials mean initial unit costs remain elevated. Manufacturers who secure differentiated suppliers or move to modular designs can protect margin while offering tiered price points to broaden adoption.
-
Occupational health as demand engine: Rising recognition of musculoskeletal disorders among clinicians is converting ergonomic benefit claims into procurement criteria for clinics and hospitals, creating a recurring replacement and upgrade dynamic rather than one‑time purchases.
-
Concentration and competitive tension: The market exhibits meaningful concentration among a handful of established players but leaves spaces for innovators and regional specialists — a structure that encourages selective M&A and strategic distribution partnerships.
Competitive landscape — how leading vendors are shaping choices
-
Designs for Vision (Bohemia, NY): Known for custom‑crafted telescopes and LED headlights, their strength lies in bespoke optical engineering and an industrialised custom‑manufacturing capability. Their recent factory transparency moves indicate a strategy to turn manufacturing quality into a commercial argument — useful for buyers who prioritize traceability and post‑sales service.
-
Orascoptic (United States): A long‑standing proponent of ergonomics, Orascoptic’s positioning emphasizes productivity and clinician performance. Their active trade show presence and professional education programs make them a benchmark for channel‑led adoption tactics oriented toward continuing education networks.
-
SurgiTel (United States): With a focus on ergonomics and user‑friendly flip‑up designs, SurgiTel appeals to clinicians seeking injury mitigation with minimal workflow disruption. Their design choices reduce the friction of clinical adoption and are a playbook for designing clinically compatible products.
-
Univet Loupes (Italy): Italian craftsmanship and premium materials define their offering. Their value proposition centers on finish, anti‑fog technology, and durability; they serve as a reminder that premiumisation remains a viable strategy where procurement is less price‑sensitive.
-
NuEyes (United States): A disruptive entrant with live 3D stereoscopic systems and continuous magnification, NuEyes represents the “digital pivot” in the category. Their product archetype highlights how imaging and ergonomics converge; regulatory classification advantages for some devices lower barriers for early commercialisation.
-
LumaDent (United States) and Admetec (United States): Both focus on ergonomics and a range of optical technologies, from Galilean to prismatic systems. Their breadth across frames, lighting, and optics shows how bundled hardware and service plays can differentiate in mature channels.
Recent events that change the landscape
-
European regulatory approval (Feb 2025) — raises the compliance bar and favours firms that invest early in documentation and quality systems.
-
Designs for Vision factory disclosures (Aug 2025) — an indicator that manufacturing transparency can be used as a commercial differentiator in tender processes and institutional sales.
-
Orascoptic’s planned AGD showcase (May 2026) — industry events remain the primary vehicle for clinician education and product trial; presence and demonstration strategy materially influence adoption curves.
Actionable strategic moves for 2026
-
Regulatory first: Prioritise MDR and equivalent filings now; lagging compliance will meaningfully extend time to revenue in regulated markets.
-
Product tiering: Move to a modular architecture that supports a low‑entry price point and premium optical/lighting modules to protect margins as commoditisation pressures expand.
-
Service and training bundle: Convert ergonomics and clinical performance claims into measurable outcomes through training programs and post‑sales analytics to increase retention and recurring revenues.
-
M&A and partnerships: Target bolt‑on optics, LED suppliers, or imaging software houses that unlock either cost reduction or differentiation. Prioritise targets that accelerate access to clinical networks or that offer scale in manufacturing.
-
Channel play: Invest in continuing education partnerships and demonstration programs in clinical societies; physical trials and peer endorsements remain higher‑impact than digital marketing alone.
-
Supply resilience: Hedge material exposures and qualify alternative suppliers for optics and LED modules to protect margin and lead times against input cost volatility.
How to use the full PW Consulting report
-
Validate your investment case by downloading the forecast model and running company‑specific scenarios.
-
Use the competitive profiles and go‑to‑market playbooks to sharpen RFP responses and distributor negotiation points.
-
Access the regulatory checklists and sample clinical evidence templates to shorten approval timelines and reduce checklist rework.
We intentionally keep certain granular splits and segment‑level revenue tables outside of this preview to preserve the commercial value of the underlying data. The full report contains region‑ and application‑level forecasts, device‑type adoption curves, and unit economics that convert the macro picture above into executable 12‑ to 36‑month plans. For teams that must make capital allocation, product roadmap, or M&A decisions in 2026, that level of resolution is the difference between a strategic leading position and reactive catch‑up.
PW Consulting’s Dental Loupe Market study is built to be directly operational: models you can run, checklists you can apply, and vendor strategies you can act on. If your 2026 plan depends on prioritised growth, regulatory certainty, and defensible commercial differentiation, the intelligence in the full report will accelerate decision quality and time to impact.
For detailed analysis of this topic, please visit the official page: Dental Loupe Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com