

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Blood Bank Refrigerators Market to Reach USD 2,611.6M by 2032 at 5.45% CAGR
By pmarketresearch, 2026-07-13
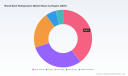
Blood Bank Refrigerators Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
PW Consulting’s latest market research on Blood Bank Refrigerators synthesizes five years of historical performance (2020–2025) and delivers a forward-looking forecast through 2032, with 2025 established as the base year. The market is on a steady expansion path: total industry revenues rose from approximately USD 1,445 Million in 2020 to about USD 1,829 Million in 2025 and are projected to accelerate to roughly USD 1,986 Million in 2026, reaching an estimated USD 2,612 Million by 2032. The compound annual growth rate (CAGR) across the forecast window reflects a mid-single-digit expansion of 5.45%—a rate that supports both conservative planning and selective growth plays.
Blood Bank Refrigerators Market
Why this research matters in 2026
As healthcare systems recalibrate after a prolonged period of capital discipline and supply-chain reconfiguration, blood management remains a non-discretionary priority. The refrigerator segment sits at the intersection of clinical risk mitigation, regulatory compliance, and hospital operational efficiency. For manufacturers, hospital procurement leads, laboratory networks, and private equity investors evaluating healthcare infrastructure plays, this study provides the analytical substrate required to prioritize investments, refine go-to-market strategies, and quantify near-term service and aftermarket opportunities.
Blood Bank Refrigerators Market
Key market dynamics shaping 2026 strategy
-
Regulatory and standards pressure — Blood bank refrigerators are regulated as medical devices under multiple frameworks (including classification and quality systems requirements). Compliance with FDA device rules and European medical device regulations remains table stakes, while third-party standards programs (notably AABB’s SCoPE program) have become a de facto reassurance mechanism for clinical buyers. Expect procurement cycles to increasingly favor suppliers that can demonstrate robust conformity and certified performance under these regimes.
Blood Bank Refrigerators Market -
Clinical performance and cold-chain integrity — The clinical imperative to maintain a constant +4°C environment for whole blood and many blood components constrains product innovation to incremental advances that preserve reliability while improving monitoring and alarm systems. Remote telemetry, secure data logging, and third-party verification features are rising from desirable to required in many institutional tenders.
-
Operational efficiency and TCO focus — With constrained capital budgets, health systems emphasize total cost of ownership. Features such as energy efficiency, uptime guarantees, modular serviceability, and extended compressor warranties materially influence purchasing decisions. Energy-star or equivalent efficiency labeling and low-noise designs are increasingly influential in hospital and laboratory RFPs.
-
Regional demand patterns and procurement sophistication — While demand is global, adoption curves differ by end-user sophistication and regulatory expectations. Hospitals and blood banks remain the core end markets, with research laboratories and other clinical institutions forming a smaller but innovation-forward segment.
Competitive landscape — who matters and why
The vendor field combines global conglomerates with specialized medical refrigeration manufacturers. Competition is product- and compliance-driven; vendors that align product engineering with third-party certifications and strong local service footprints enjoy preferential access to large institutional contracts. Below are concise profiles of the market’s noteworthy participants, selected for their demonstrated product capabilities and recent market activity.
-
Thermo Fisher Scientific (Waltham, MA, USA) — A life-science heavyweight whose blood bank refrigerator portfolio (including AABB SCoPE-certified TSX Revco and TSX Blood Bank models) emphasizes regulatory alignment and enterprise procurement compatibility. Thermo Fisher’s scale supports integrated procurement offers combining refrigerators with broader laboratory cold-chain solutions.
-
Helmer Scientific (Waukesha, WI, USA) — Known for ENERGY STAR–compliant upright blood bank ranges (GX Solutions and Horizon Series) that balance AABB certification with energy efficiency and quiet operation. Helmer’s November 2025 recognition under a standards-compliance program reinforces its positioning among health systems prioritizing certified performance.
-
B Medical Systems (Luxembourg) — Focused on certified, scalable offerings for blood management with devices that meet EU regulatory classifications and FDA device rules while providing remote monitoring capabilities. Recent clinical user testimonials (collected in 2025 from major hospital users) underscore their field performance narrative, which is a persuasive asset in emerging market tenders.
-
Biomedical Solutions, Inc. (Waltham, MA, USA) — Marketed as purpose-built units for whole blood and components at clinically relevant temperatures. The company’s product claims stress compliance and operational fit for hospital and laboratory settings.
-
Kirsch Medical (Germany) — A Europe-based supplier emphasizing ISO 13485–aligned manufacturing and compliance, appealing to buyers with high regulatory scrutiny and those requiring clear audit trails for device selection.
-
Migal Scientific (USA) — Product differentiation centers on high-capacity upright models, advanced thermal technologies (e.g., expansion-valve systems), and extended compressor warranties—features that speak directly to uptime, reliability and lifecycle cost reduction.
-
Lab Repco (USA) — Focused on clinical refrigerators for standard hospital and lab use-cases, positioning for competitive pricing and practical serviceability.
-
PHCbi (Panasonic Healthcare) (Japan) — Offers Class IIa–certified medical devices for blood component storage. PHCbi’s product compliance lineage appeals to large hospital systems and purchasers seeking tried-and-tested global suppliers.
Notable recent developments and what they imply
-
Standards recognition for specific models (late 2025) increases vendor stickiness in institutional procurement—buyers will favor models with third-party program endorsements.
-
Multiple user testimonials published in 2025 highlight the market’s growing emphasis on real-world performance data. Manufacturers should invest in clinical validation programs and post-deployment case studies to accelerate tender wins.
-
Regulatory clarifications across jurisdictions continue to influence product design lifecycles. Vendors that proactively align R&D roadmaps with device classification changes will shorten time-to-market and reduce compliance rework costs.
Report contents — what PW Consulting delivers
This research is intentionally practical. It includes:
-
A quantitative market model (historical 2020–2025; forecast 2026–2032) expressed in USD Million, enabling scenario planning and revenue-at-risk computations for different investment horizons.
-
Regulatory and standards mapping that translates device classification, quality system obligations, and third-party testing programs into procurement risk matrices for manufacturers and buyers.
-
Vendor benchmarking—assessing product portfolios, certification status, field evidence and aftermarket strengths—to support supplier shortlists and sourcing strategies.
-
Go-to-market playbooks focused on eight actionable initiatives: channel optimization, service-part strategies, product feature prioritization (e.g., telemetry, energy efficiency), pricing levers, clinical evidence generation, regulatory roadmaps, and M&A screening criteria.
-
Scenario-based forecasts that help CFOs and strategy teams stress-test budgets under competing capital allocation and adoption pace assumptions.
Actionable recommendations for 2026
-
For manufacturers: prioritize investments in certified device portfolios and remote-monitoring capabilities. Partner with clinical sites to build performance dossiers that substantiate uptime and temperature-control claims—these are decisive in tender evaluations.
-
For hospital procurement teams: request documented third-party compliance evidence and demand lifecycle cost projections (energy, service, parts). Shortlist suppliers that can demonstrate both certification and local service coverage.
-
For investors and private equity: focus on firms with differentiated service models and recurring aftermarket revenue. The mid-single-digit CAGR creates space for consolidation, but value will accrue to players who can scale service operations and compliance capabilities quickly.
How to use this briefing in your 2026 planning
Use the headline market trajectory and the regulatory roadmap provided here to align product roadmaps, sales compensation, and inventory policies. Translate forecast ranges into procurement batch sizes and phase capital spend to capture both baseline replacement demand and incremental demand driven by efficiency upgrades. Leverage vendor benchmarking to reduce RFP friction and accelerate sourcing cycles.
Closing — the value of full access
This briefing demonstrates the strategic lines of action supported by PW Consulting’s data and expert analysis. The full report contains the granular segmentation, regional and application breakdowns, price and margin analysis, and an expanded competitive matrix that are intentionally withheld here to preserve the losing/winning tradecraft of competitive positioning. For procurement templates, segmented demand curves, and a downloadable vendor dossier with model-level specification comparisons, please consult the full report.
PW Consulting is prepared to brief executive teams, run supplier-selection workshops, and build bespoke financial scenarios that operationalize these insights for 2026 capital and commercial planning.
For detailed analysis of this topic, please visit the official page: Blood Bank Refrigerators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydration Bottle Market to Grow at 6.5% CAGR Through 2032
By pmarketresearch, 2026-07-13
Hydration Bottle Market — 2026 Strategic Preview
PW Consulting’s Hydration Bottle Market study (base year 2025; historical 2020–2025; forecast 2026–2032) frames the sector at a defining inflection point. The report synthesizes high-frequency market data, supplier intelligence and regulatory mapping into an executive-grade playbook for decision-makers planning product, channel and M&A moves in 2026. This preview outlines why the study matters to corporate leaders and what actionable direction it provides — while reserving the granular segmentation tables and region/application splits for the full report.
Hydration Bottle Market
Why executives should care in 2026
-
Steady expansion with opportunity windows: The market trajectory through the forecast period is underpinned by multi-year compounding growth (CAGR 6.5%). That expansion is not uniform: pockets of premiumization, sustainability-driven premium demand and digital-enabled products are materially outpacing mature commodity segments. Knowing where to allocate growth investments is now a first-order strategic decision.
Hydration Bottle Market -
Concentration creates leverage: Market concentration is high — the top-three players capture a dominant share and the top-five an even larger proportion of value. That concentration intensifies competitive dynamics around brand, distribution and innovation, but it also creates M&A arbitrage opportunities for challengers and private capital seeking consolidation plays.
Hydration Bottle Market -
Regulatory and material regimes are reshaping cost and claims: Standards for BPA-free plastics, ISO-driven quality certification for stainless steel production and labeling obligations for any added electrolytes are all active constraints that need to be integrated into sourcing and R&D roadmaps if companies are to avoid compliance-driven product rework or market access delays.
What the research delivers — practical, decision-ready outputs
The PW Consulting study is structured to move beyond descriptive market graphs and into implementable strategy. Key deliverables include:
-
Rigorous market sizing and a transparent forecast engine: full time-series (2020–2032) with scenario layers (baseline, downside and upside) and sensitivity to material cost and channel mix shifts.
-
Competitive benchmarking and capability heatmaps: product portfolios, pricing ladders, channel footprints, manufacturing capabilities and patent/activity indicators for the leading manufacturers and notable challengers.
-
Go-to-market playbooks by archetype: tactical templates for premium D2C brands, mass-market retail players, private-label manufacturers and OEM channel partners including launch checklists, sample SKU portfolios and promotional calendar suggestions aligned to seasonal demand.
-
Supply chain and raw-material stress tests: scenario analysis that quantifies exposure to stainless-steel and high-performance plastics (e.g., Tritan) supply disruptions, lead-time risk, and pricing pass-through mechanics.
-
Regulatory compliance matrix: mapped obligations across major jurisdictions for material safety claims, manufacturing certifications and labeling requirements for value-added hydration products.
-
M&A and partnership target shortlists: prioritized sets of bolt-on targets and collaboration candidates, with preliminary valuation heuristics and integration risk ratings.
-
KPIs and monitoring dashboards: recommended metrics to track week-on-week and month-on-month (inventory days, SKU-level gross margin, channel CAC, consumer repeat rate), plus a data-sourcing guide for live monitoring.
Competitive landscape — what the leaders are doing
The market’s competitive architecture is shaped by a mix of outdoor-heritage brands, design-driven premium players and mass-market innovators. The report includes deep profiles and strategic analysis of core firms that shape the category:
-
CamelBak Products, LLC (Petaluma, CA): a leader in durability and outdoor-focused design; recent launches emphasize recycled-material collections that both meet consumer sustainability preferences and adjust supplier relationships toward circular material streams.
-
Hydro Flask (Boulder, CO): continues to dominate premium insulated stainless-steel demand; its 2024 launch of lightweight eco-focused lines signals a push to reconcile performance with portability and lower carbon footprint claims.
-
Nalgene (Rochester, NY): remains the reference brand for durable, BPA-free Tritan plastic bottles; product expansions and refreshes are being used to protect mass-market shelf presence and to defend against price-based private-label incursions.
-
Klean Kanteen (Boulder, CO): emphasizes food-grade, vacuum-insulated stainless steel and positions toward health-conscious consumers and institutional buyers who prioritize compliance and workplace sustainability programs.
-
Contigo (Chicago, IL): increasingly mixes convenience-driven design with tech-enabled offerings — its smart hydration bottle launched in 2024 points to an adjacent playbook where IoT features and digital services (hydration tracking) open recurring revenue and data-capture opportunities.
These public moves — from recycled-material launches to smart products — inform the report’s recommended strategic options for incumbents and challengers alike.
Materials, regulation and consumer dynamics — the operating environment
-
Materials regime: Stainless steel and Tritan plastics remain the dominant production substrates due to durability and scale economies. The report models cost curves and supplier concentration for each material class, allowing procurement teams to hedge exposure and design dual-sourcing strategies.
-
Regulatory overlay: Mandatory BPA-free and phthalate-free labeling in major markets, ISO 9001:2015 expectations for reusable stainless steel production facilities and nutrition/ingredient disclosure standards for electrolyte-enhanced hydration products require clear compliance pathways — not optional checkboxes.
-
Consumer preference vectors: Sustainability and reuse are persistent megatrends driving premium elevation; at the same time, digital convenience and health personalization (hydration tracking, added electrolytes) are emerging demand drivers that change price elasticity and lifetime value calculations.
Strategic implications for 2026 planning
-
Portfolio prioritization: We recommend a two-track product portfolio — defend core commodity SKUs while selectively investing in premium insulated and smart-enabled lines that deliver higher margin and stronger brand loyalty metrics.
-
Sourcing and certification: Short-term investments in dual-sourcing stainless-steel capacity and securing ISO quality certification reduce supply shock risk and shorten time-to-market for premium launches; include compliance timelines in 2026 CAPEX planning.
-
Channel mix and pricing: Expand D2C initiatives for premium launches to capture richer margin and data; preserve retail scale via tailored assortment and private-label partnerships in non-core channels. Use dynamic pricing pilots to measure elasticity across heritage and new product lines.
-
Digital + services playbook: For firms considering smart bottles, pilot programs should prioritize data privacy, recurring subscription models (hydration coaching or replacement caps) and integration with wellness platforms to accelerate payback.
-
M&A and portfolio optimization: Given the high CR3/CR5 concentration, there are defensible consolidation plays in niche insulation tech, material recycling capabilities and digital services — each target type has distinct integration risk and synergies quantified in the full study.
What to expect from the full report
The complete PW Consulting Hydration Bottle Market report provides chapter-level depth that supports boardroom decisions and 90-day execution plans. Highlights include:
-
Full forecast models with scenario toggles and download-ready spreadsheets for CFO stress-testing.
-
SKU-level margin templates and promotional elasticity matrices for CPG and retail teams.
-
Regulatory playbooks by jurisdiction and a supplier vetting toolkit for procurement teams.
-
Executive briefing slides and a one-day strategy workshop framework customized to your company’s profile.
Recommended next steps (90-day playbook)
-
Buy the full report and schedule a tailored executive briefing with PW Consulting to map the findings to your organization’s priorities.
-
Run a rapid internal audit of material and certification exposure; prioritize ISO alignment and dual sourcing within your Q3 procurement roadmap.
-
Initiate two product pilots in parallel — one premium insulated SKU sold via D2C and one smart-enabled cap as a limited release — using the report’s go-to-market templates to measure CAC and early repeat rates.
-
Identify consolidation targets in adjacent niches (recycling, IoT caps, insulation tech) and start preliminary outreach backed by the report’s M&A shortlists and valuation heuristics.
Closing
The hydration bottle category is no longer just a mass-market commodity. Underneath steady overall growth (historical to 2025 and projected across our forecast window) there are distinct, investable accelerants: sustainability, premium insulated performance and digital services. PW Consulting’s study translates those accelerants into executable playbooks — balancing defensible near-term actions with strategic capability investments that will determine winners in 2026 and beyond. For access to the full dataset, regional and application splits, and the downloadable forecasting model, refer to the full report and our accompanying executive workshop.
For detailed analysis of this topic, please visit the official page: Hydration Bottle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Density Core Materials to Reach USD 814.9M by 2032 at 5.4% CAGR
By pmarketresearch, 2026-07-13
High Density Core Materials Market: Strategic Preview for 2026 Decision-Makers
Executive teaser
As boards and corporate development teams prepare 2026 investment cycles, the strategic choices companies make in core materials for high-performance composites will determine competitiveness across aerospace, marine, wind energy, and advanced industrial segments. PW Consulting’s forthcoming High Density Core Materials Market study synthesizes a decade of trend signals into an actionable foresight framework: it shows where demand and margin pools are enlarging, which supply-chain risks require immediate mitigation, and which certification and sustainability vectors will unlock differentiated access to premium projects. This article summarizes the study’s strategic value without disclosing the granular segment allocations—our trailer for decision-makers who need depth, direction, and the full dataset available on the report landing page.
High Density Core Materials Market
Why this matters in 2026
High density core materials are no longer a niche engineering choice; they are a system-level enabler for lightweighting, structural performance, and service-life economics. Between 2020 and 2025 the global market expanded materially, reflecting resilient end-market investments and a steady uptick in substitution away from traditional solutions. With a defined base year of 2025, the market is projected to continue growing at a compound annual growth rate (CAGR) of approximately 5.4% through the 2026–2032 forecast window. By 2032 the market is expected to be meaningfully larger than in 2025—an indicator that near-term strategic moves (supplier selection, certification investments, and product roadmaps) made in 2026 will compound value across the decade.
High Density Core Materials Market
Market trajectory and strategic implications
-
Growth profile: The market’s steady expansion from the early 2020s into 2025 demonstrates both cyclical resilience and secular drivers—lightweighting mandates, offshore wind scale-up, and more demanding subsea and aerospace specifications. The forecast horizon through 2032 implies a multi-year runway for new product introductions and capacity investments, but with differentiated returns by application and material class.
High Density Core Materials Market -
Concentration and competition: Market concentration is moderate; the leading three and five suppliers capture a non-trivial share of the market, indicating healthy competition but also the persistence of premium suppliers with technical moats. For strategic planners this means both procurement leverage opportunities and the necessity of relationship-driven sourcing for specialist high-density grades.
-
Margin dynamics: Higher-performance, certification-ready core materials command pricing premiums; however, raw-material volatility and logistics can compress margins quickly. Companies that secure technical approvals and demonstrate sustainability credentials will be better positioned to capture and sustain those premiums.
Supply-chain and raw-material risk
Two practical facts drive supply-side risk decisions. First, certain natural core sources remain geographically concentrated—more than 90% of some natural supplies originate from a very small set of countries. That concentration has already translated into sharp price movements (recent industry data suggests upward pressure nearing 28% in specific natural-core inputs), which in turn affects total cost of ownership for finished composite structures. Second, synthetic foam families depend on petrochemical feedstocks and specialty polymer supply chains that face their own constraints and lead-time variability. The report provides procurement playbooks and stress-tested scenario models that allow procurement and supply-chain teams to evaluate: (a) dual-sourcing strategies, (b) hedging and contract structures, and (c) nearshoring vs. centralized sourcing trade-offs tailored to different CAPEX and OPEX profiles.
Regulatory, certification and sustainability inflection points
-
Certification as market access: New or clarified rules—such as those governing materials used in underwater technology—mean that Type Approvals and equivalent certifications become gating factors for participation in subsea buoyancy and similar projects. The presence of Type Approval pathways materially changes supplier selection, contracting cadence, and time-to-project for operators. Companies that front-load certification investments in 2026 will shorten bid cycles and reduce proposal risk in 2027–2028 projects.
-
Sustainability differentiation: Mass-balanced bio-circular raw material sourcing, Environmental Product Declarations (EPDs) showing reduced global warming potential (GWP), and recognized supplier sustainability ratings (e.g., EcoVadis distinctions) are increasingly demanded in RFPs from large OEMs and system integrators. The study maps how sustainability credentials map to win-rate uplifts in public tenders and private procurement processes, and prescribes a certification sequencing playbook for commercial teams.
Competitive landscape — what to watch
The market features established global suppliers with differentiated technical portfolios and nimble regional players targeting local projects. The study includes a detailed competitive analysis of key firms, their strategic positioning, and recent capability moves that should influence 2026 strategic choices.
-
Gurit (Wattwil, Switzerland) — A technology-led provider of structural foam cores with product lines serving marine, subsea, and aerospace. Recent operational expansion plans in the U.S. speak to an intentional push to support growing subsea demand, while certification wins for specific structural foam grades materially expand addressable applications in underwater technology.
-
Diab Group (Sweden) — Known for engineered foam cores and system-level offerings. Recent industry recognition for innovation in boatbuilding methods highlights R&D leadership and commercial readiness for modular, high-value applications. Diab’s sustainability initiatives and published EPDs represent a clearer decarbonization roadmap—important when bidding into sustainability-conscious programs.
-
3A Composites (Switzerland) — Supplies high-performance core materials and alternatives to traditional natural cores. Their emphasis on performance parity and supply chain reliability is a competitive lever for customers prioritizing consistency over novelty.
-
General Plastics, Evonik, Armacell, CoreLite, Nomaco, Polyumac — These firms range from specialists in high-density PU/PMI foams to producers of PET foam cores and rigid polyurethane solutions. Each brings specific certifications, material science strengths, and vertical-market relationships that buyers should audition against project specs and lifecycle cost models.
Recent developments that shape 2026 strategies
-
Operational scaling by established suppliers in North America to support subsea demand suggests a near-term tightening of localized supply and a potential shift in logistics and lead-times. Firms planning projects in 2027–2028 should consider supplier capacity commitments or strategic inventory buffering in 2026.
-
Certification milestones achieved by suppliers open previously inaccessible project classes. When a supplier obtains Type Approval for underwater applications, procurement teams should revisit approved vendor lists and re-evaluate technical risk premiums.
-
Innovation awards and publicized EPDs are not merely PR—these events are correlated with increased OEM consideration in design-review gates. Companies with active R&D and credible environmental declarations are winning earlier-stage engagement.
What the PW Consulting report delivers (practical modules)
The full study is engineered for commercial, procurement, product and M&A teams. It contains:
-
Market sizing and growth scenarios (base year 2025, historical 2020–2025, forecast 2026–2032) with demand sensitivity to key macro variables.
-
Supplier capability matrices and a technical-readiness index that tie materials to certification pathways and application suitability.
-
Procurement playbooks: contracting templates, inventory strategies, and stress-tested sourcing scenarios for raw-material price shocks and geopolitical disruptions.
-
Sustainability roadmap: pathway-to-EPD and mass-balance certification templates and supplier engagement sequences to improve tender win rates.
-
Competitive benchmarking: qualitative and quantitative assessments of leading firms, plus a shortlist of potential targets and partners for bolt-on M&A or co-development agreements.
-
Commercial impact tools: pricing elasticity models, TCO calculators for sandwich structures, and decision matrices to evaluate in-house production versus outsourced supply.
-
Executive-ready scenario narratives and action plans keyed to 90-, 180-, and 360-day decision cycles for 2026 budgeting and strategic milestones.
Concrete actions for CEOs and functional leaders in 2026
-
Procurement: Initiate dual-sourcing pilots for concentrated natural inputs and lock in conditional capacity agreements with certification-capable suppliers to avoid late-stage substitution risk.
-
Product & Engineering: Prioritize certification pathways for materials that open high-margin subsea and aerospace use-cases; accelerate lab-to-cert timelines with supplier co-investment where economics justify.
-
Corporate Development: Use the study’s competitive heatmaps to screen acquisition targets that provide either geographical manufacturing footholds or unique certification/IP assets.
-
Sustainability & Compliance: Map procurement tenders to EPD and circularity requirements and establish a three-step certification plan to avoid bid disqualification.
Closing: what to expect from the full study
Consider this article a strategic trailer: it outlines the market trend, the risk landscape, and the supplier dynamics that should shape 2026 decisions. PW Consulting’s full High Density Core Materials Market study provides the underlying data, granular segment analyses, and executable toolkits that procurement, product, and corporate leaders need to act with confidence. If your 2026 capital allocation or supplier strategy depends on reliable, application-specific intelligence, the complete report will deliver the datasets and implementation playbooks required to move from insight to impact.
For teams preparing 2026 budgets and strategic roadmaps, the time to model scenarios and secure technical partnerships is now—both because of growing demand and because certification and capacity moves by leading suppliers are already reshaping access to premium projects. Access the full report through our website to obtain the detailed segmentation, supplier scorecards, and the decision-support templates that are deliberately withheld here to preserve the study’s actionable core.
For detailed analysis of this topic, please visit the official page: High Density Core Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Mushrooms Market 2026: Strategic Imperatives for Executive Decision‑Makers
Between 2020 and 2025 the global mushrooms market moved from a sizeable base to a materially larger and more complex ecosystem. Our research shows the market expanded from roughly USD 41.8 billion in 2020 to about USD 62.2 billion in 2025. Using 2025 as the base year, PW Consulting projects the market will continue on a robust trajectory through our forecast window (2026–2032), with compound annual growth of 9.6% and an expected market size that approaches USD 118.2 billion by 2032. For executives making resource allocation, M&A, or new‑product decisions in 2026, these headline dynamics are not just background noise — they reframe strategic priorities.
Mushrooms Market
Why this study matters in 2026
-
Acceleration and scale: A near‑double market projection by 2032 implies that scale economies, capital intensity, and capacity timing will be decisive. Decisions on facility investments, automation, and distribution partnerships taken in 2026 will determine competitiveness throughout the next cycle.
Mushrooms Market -
Sustainability as a price of admission: Innovations such as peat‑free cultivation are no longer niche R&D headlines. Leading growers are embedding sustainable substrates and certification into their production roadmaps — a practical requirement for access to premium retail and institutional customers.
Mushrooms Market -
Supply‑side signal clarity: Industry reporting and grower surveys indicate modest year‑on‑year changes in crop volume and organic production trends. These operational signals should inform procurement strategies, contract length, and buffer stocking decisions rather than being treated as incidental.
-
Innovation hubs and networking: The calendar of trade events (European and Asian Mushroom Days, and emergent national expos) continues to concentrate new cultivation technologies, substrate innovation, and distribution models. Executives who prioritize participation will unlock partnership and licensing opportunities earlier.
What the report delivers — practical outputs for 2026 action
-
Transparent market sizing and forecast models: Base‑year 2025 calibration, historical analysis (2020–2025), and scenario‑based forecasts for 2026–2032 that combine price‑volume modeling with sensitivity analysis across key drivers.
-
Demand archetypes and product playbooks: Segmented demand profiles (fresh, value‑added, functional/ingredient, cosmetics, pharmaceutical R&D channels), with go‑to‑market templates for retailers, CPG incumbents, and ingredient suppliers.
-
Supply‑chain economics and cost curves: Benchmarks for cultivation CapEx/Opex, substrate sourcing options, energy and labor intensity by cultivation system, and automation break‑even calculations designed for boardroom decision packs.
-
M&A and partnership scorecards: A practical methodology for target prioritization, synergy sizing, and integration risk assessment tailored to both horizontal consolidation and vertical integration plays.
-
Regulatory and sustainability roadmaps: Actionable compliance checklists, certification pathways, and commercial levers associated with peat‑free and organic production that affect shelf access and pricing power.
-
Commercial deployment tools: Negotiation playbooks for long‑term offtake, supplier risk matrices, SKU rationalization templates, and channel margin models to accelerate commercialization.
Competition and market structure — where advantage will come from
The reported concentration metrics point to a moderately consolidated market: the three largest participants account for just over one‑third of market share, and the five largest just over forty percent. This structure creates dual strategic spaces: scale advantages for large integrated players and pockets of high margin opportunity for specialized operators who can command premium positioning or proprietary capabilities.
-
Integrated scale operators (examples): Major North American and European producers have focused on high‑throughput cultivation, cold‑chain logistics, and retail distribution relationships. Their playbooks emphasize capacity utilization, retail category management, and shelf presence.
-
Specialists and niche innovators (examples): Family‑run and boutique growers concentrating on specialty, organic, or exotic varieties are leveraging product differentiation, premium pricing, and e‑commerce channels. These firms are also the primary testbeds for substrate and cultivation innovation.
-
Contract manufacturers and substrate suppliers: Integrated groups that control both cultivation and substrate supply are extracting margin through vertical control and innovation in growing media (including peat alternatives), presenting attractive targets for strategic buyers wanting secure inputs.
PW Consulting’s competitive dossiers include concise strategic summaries for core industry players — their positioning, core capabilities, and plausible next moves — to support rapid competitor benchmarking and M&A screening.
Recent industry signals that should inform 2026 strategy
-
Trade‑show cadence: Europe and China remain focal points for product, equipment, and substrate innovation; newly emergent national expos are expanding industry connectivity in Asia and South Asia. These forums are primary channels for commercialization of cultivation and processing innovations.
-
Operational trends: National statistics indicate modest shifts in crop volumes year‑on‑year and a mixed trajectory for certified organic production. These operational data points should be used to stress‑test inventory and procurement assumptions rather than treated as static baselines.
-
Sustainability initiatives: The adoption of peat‑free production practices by leading producers is a structural change in European operations with cascading implications for substrate suppliers, input suppliers, and certification bodies.
-
Data transparency: Increasing public reporting by growers and national agricultural services is improving market visibility — enabling higher‑fidelity forecasting but also raising the bar for competitive response times.
How the C‑suite should use this intelligence in 2026
-
Prioritize capacity timing: Use our scenario models to decide whether to defer, accelerate, or scale facility investments given probable demand paths and cost inflation in inputs and energy.
-
Embed sustainability into product roadmaps: Convert sustainability commitments (e.g., peat‑free practices) into concrete product launches and procurement contracts to protect shelf access and price premiums.
-
Refine M&A filters: Apply our M&A scorecards to shortlist targets that deliver immediate synergies in distribution, substrate sourcing, or value‑added product lines; focus on bolt‑on deals that shorten time‑to‑market.
-
Operationalize risk: Incorporate crop volume and organic production trends into procurement and inventory policies; stress‑test counterparty concentration and logistics disruptions with scenario planning.
-
Commercial experiments: Run two‑quarter pilot programs for differentiated SKUs (functional ingredients, premium fresh, or shelf‑stable innovations) with pre‑tested margin levers and marketing playbooks from our templates.
Data & methodology — what’s in the black box
The study is anchored on a 2025 base year and a historical series spanning 2020–2025. Forecasts cover 2026–2032 and are presented under a dual approach: a primary deterministic forecast (price × volume by product family) and an overlay of three risk scenarios that stress test demand shocks, input cost inflation, and regulatory shifts. Research inputs include primary interviews with growers and processors, published national agricultural statistics, participation in industry trade forums, supply‑chain cost surveys, and audited company disclosures. To preserve commercial value for subscribers, the full report contains the granular segmentation tables, regional breakdowns, and channel mixes that informed the headline forecast.
Chapter preview (trailer)
- Executive summary and headline forecast
- Market sizing methodology and model mechanics
- Demand segmentation and buyer archetypes
- Supply‑side economics: cultivation, substrate, and processing
- Distribution and retail economics
- Regulation, certification, and sustainability scenarios
- Competitive landscape and company dossiers
- M&A playbook and valuation templates
- Commercial deployment toolkits and KPI dashboards
PW Consulting’s Mushrooms Market study is designed as a decision‑support instrument for strategy teams, corporate development, procurement, and operations groups. The headline market trajectory, material sustainability inflection points, and evolving supply‑chain economics together create a narrow window in 2026 to secure advantaged positions. For the tables, datasets, and executable templates that underpin our model — including the full segmentation and regional breakdowns omitted here — please consult the full PW Consulting report and data pack.
For detailed analysis of this topic, please visit the official page: Mushrooms Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Construction Management Software Market: Strategic Outlook for Enterprise Decision-making in 2026
As organizations plan capital programs, technology procurements, and M&A strategies for 2026, the Construction Management Software market presents both a clear growth trajectory and a set of structural shifts that will determine winners and losers. This briefing, prepared by PW Consulting’s industry practice, synthesizes market sizing, competitive dynamics, regulatory drivers, and practical decision frameworks that senior executives and procurement leads need to act with confidence. The full report contains granular segment tables, regional splits, and vendor scorecards — this introduction previews the strategic implications while deliberately withholding detailed segment-level figures to encourage targeted access to the underlying data package.
Construction Management Software Market
Market trajectory and what it means for 2026 planning
Using 2025 as the base year, our top-line market sizing traces a clear, compounding growth pattern across the last half-decade and into the coming planning horizon. The market expanded steadily from the start of the historical window (2020) through 2025 and is forecast to continue doing so across 2026–2032 at an industry compound annual growth rate of approximately 8.99%. Under PW Consulting’s baseline forecast the market reaches a materially larger scale by the end of the forecast window, reflecting sustained digitalization, cloud adoption, and the materialization of AI-enabled workflow automation.
Construction Management Software Market
For enterprise decision-makers, three immediate takeaways follow from this profile. First, procurement windows in 2026 should account for accelerating feature development — particularly around AI and BIM integration — meaning multiyear contracts should include explicit upgrade, integration, and exit clauses. Second, investment cases for deployment (cloud-first vs hybrid/on-premise) must incorporate regulatory and data-residency constraints that are now non-negotiable in several jurisdictions. Third, the expanding market creates more attractive M&A and partnership opportunities, but only to the extent buyers can operationalize integrations quickly and capture network effects across projects.
Construction Management Software Market
Competitive structure and strategic positioning
- Market concentration and competitive behavior. The market exhibits moderate concentration: a small set of global platform vendors lead with broad enterprise suites while numerous specialist vendors continue to capture niche demand. This structure drives a dual strategy for incumbents — deepen platform hooks through integrations and AI, and protect core revenue by building partner ecosystems.
- Vendor archetypes and what they signal to buyers. From enterprise-grade suites offering project portfolio and resource optimization to focused solutions for residential builders and field-level execution, vendor capabilities cluster into: (a) enterprise scheduling/portfolio platforms, (b) BIM and design-construction integrators, (c) field execution and safety tooling, and (d) horizontal ERP modules for construction finance. Understanding which archetype aligns to your company’s operating model is a first-order decision for 2026.
- Notable vendor dynamics observed in early 2026. Leading vendors have accelerated both product integrations and AI investments. Several platform providers announced integrations and acquisitions in Q1–Q2 2026 that underscore a race to embed automation, risk detection, and document intelligence directly into construction workflows. Partnerships between document specialists and platform vendors are reducing friction in AEC collaboration, while enterprise vendors continue to prioritize scalability and portfolio-level analytics.
Who we track (selected profiles)
- Procore Technologies — a cloud-native platform focused on end-to-end project coordination, document control, and increasingly AI-enabled automation to improve field-to-office workflows.
- Autodesk — integrating design-to-construction workflows with BIM-first platforms that unify design and construction execution, increasingly positioning Forma and Construction Cloud as a single continuum.
- Oracle — enterprise-grade scheduling and portfolio management capabilities, integrating Primavera heritage with cloud-scale analytics for large capital programs.
- Trimble — a systems integrator approach combining scheduling, financials, and on-site risk-management tools, with recent moves to enhance AI-powered document and compliance capabilities.
- Bentley Systems — infrastructure-focused BIM and simulation capabilities that prioritize complex engineering workflows and lifecycle analytics.
- Buildertrend and CMiC — representative examples of specialist-to-enterprise players addressing residential/light commercial and integrated ERP needs respectively.
The full report contains vendor scorecards, go-to-market maps, and a timeline of strategic product releases that explain how each supplier’s roadmap maps to buyer pain points. This summary intentionally omits the detailed rank ordering and numeric scorecards to preserve the value of the complete dataset.
Regulatory and industry forces that will shape procurement in 2026
- Data residency and privacy: GDPR-era requirements, particularly in the EU, have forced cloud vendors to rearchitect multi-tenant delivery and deploy regionally isolated data centers. Procurement teams must now evaluate not only functional fit and TCO but also contractual commitments around data localization, breach notification SLAs, and auditability.
- Sustainability mandates: Whole-life carbon assessments embedded in building performance directives are creating demand for BIM-integrated modules that can capture embodied carbon and material lifecycle metrics. Expect sustainability reporting to be a requirement in public tenders and a buyer differentiator for private owners.
- Professional standards and digital competency: Industry bodies are codifying expectations for digital capabilities on capital projects, meaning vendors that embed compliance workflows and auditable decision trails will command a premium in regulated or high-accountability projects.
- Digital adoption acceleration: Professional institutions in several markets are actively promoting digital transformation. Procurement strategies should anticipate faster adoption curves among teams that receive formal institutional backing and training subsidies.
Practical, action-oriented deliverables in the full report
PW Consulting’s full study is designed to be operational from day one. Key deliverables include:
- A transparent market-sizing methodology, with historicals (2020–2025) and base-year assumptions (2025) feeding the 2026–2032 forecast scenario suite.
- Scenario analyses (baseline, accelerated digital adoption, and recession stress) to stress-test vendor selection and capex timing.
- Vendor scorecards and migration pathways that translate product capabilities into implementation roadmaps for enterprise buyers.
- TCO and ROI templates that integrate licensing, integration, training, and change management costs across short- and multi-year horizons.
- Regulatory and data-residency mapping by jurisdiction to support contract terms and hosting decisions.
- AI readiness frameworks and a prioritization matrix that identifies which workflows yield the highest near-term automation ROI.
- M&A and partnership screening criteria targeted at both strategic acquirers and private equity sponsors seeking bolt-on targets.
- Procurement artifacts: RFP/RFI templates, scoring rubrics, and negotiation playbooks tailored to construction technology purchases.
- Case studies and implementation checklists that surface common failure modes and mitigation approaches for first 90–180 days post-go-live.
How to use this research to make better 2026 decisions
- Design procurement for optionality: Given rapid feature evolution, structure contracts to preserve strategic flexibility — modular scopes, performance milestones tied to capability delivery, and clear exit clauses to prevent lock-in.
- Prioritize data strategy: Align hosting choices with regulatory exposure and future M&A plans. Where cross-border project execution is critical, require vendors to demonstrate multi-jurisdictional data controls and audit trails.
- Adopt a capability-first sourcing approach: Rather than buying point solutions for isolated pain points, prioritize platforms that can demonstrate end-to-end value for your dominant workflows (e.g., design-construction handover, site safety capture, or cost-accounting continuity).
- Prepare for AI as an operational lever: Shortlist vendors by demonstrable automation outcomes (reduction in rework, time saved in submittal processing, predictive risk signals) and require proof-of-value pilots before enterprise roll-out.
- Make sustainability and compliance non-negotiables: Embed carbon-assessment capabilities and traceable audit trails into procurement criteria for projects subject to whole-life assessment or public-sector requirements.
- Factor implementation capacity into selection: The difference between a tool and a transformation is adoption. Insist on clear change-management plans, training accelerators, and local implementation partners in vendor proposals.
Why this matters now
The market’s steady growth and the acceleration of feature-level innovation mean 2026 is a pivot year: organizations that establish robust integration architectures, strong data governance, and AI-forward pilot programs will capture outsized benefits as platforms institutionalize across project portfolios. Conversely, entities that treat construction software as a commodity risk repeated re-procurement cycles, fractured data, and missed productivity gains.
PW Consulting’s full report converts the macro trajectory — historical validation through 2025 and an 8.99% CAGR outlook through 2032 — into executable steps: vendor shortlists, negotiation levers, technical due diligence checklists, and deployment timelines. For teams building capital planning proposals, technology roadmaps, or acquisition theses for 2026, these instruments are designed to shorten decision cycles and reduce execution risk.
Next steps
This briefing is a strategic preview. The complete report includes the full segmentation, regional and application-level forecasts, downloadable vendor scorecards, and ready-to-use procurement templates. To access the detailed datasets, segmentation tables, and the evidence base behind the projections, please visit the PW Consulting research page or contact our industry practice for a tailored briefing and live walk-through of the models.
For detailed analysis of this topic, please visit the official page: Construction Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: MRI Metal Detector Market to reach USD 301.5M by 2032 at 4.5% CAGR
By pmarketresearch, 2026-07-09
MRI Metal Detector Market 2026: Strategic Imperatives for Procurement, Product, and M&A Leaders
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise strategic preview of our comprehensive MRI Metal Detector Market study. This briefing synthesizes the macro trajectory, competitive dynamics, technology inflection points, and the practical decision levers that will determine winners and losers during 2026 — the pivotal year when many healthcare systems and vendors will translate cautious experimentation into scaled deployment.
MRI Metal Detector Market
Why this study matters for 2026 decisions
-
Predictable growth with tactical complexity: The MRI metal detector market has matured into a steady-growth segment. Using 2025 as the analytical base year, our market model shows a consistent expansion through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of approximately 4.5%. By 2032 the market approach(es) the low hundreds of millions (USD), reflecting broad but measured adoption across health systems, imaging centers, and specialist facilities.
MRI Metal Detector Market -
Concentration and opportunity: Market concentration is meaningful — the top three vendors control roughly two-thirds of market revenues, and the top five capture over three-quarters. That profile creates both barriers for new entrants and clear M&A/partnership opportunities for mid-sized players seeking scale or complementary capabilities.
MRI Metal Detector Market -
Decision timing matters: 2026 will be a year of shifting priorities — from pilot installations and regulatory alignment to procurement cycles for retrofit and new-build MRI suites. Organizations that align procurement timing, validation protocols, and vendor selection criteria to this market rhythm will minimize risk while securing favorable commercial terms.
Market dynamics: drivers, frictions, and inflection points
-
Safety and risk management are the primary demand drivers. Incidents involving ferromagnetic objects in MRI environments remain a reputational and liability concern for hospitals and imaging providers. The straightforward value proposition — reducing patient and staff exposure to ferromagnetic hazards — keeps capital allocation for detection systems on the agenda.
-
Technology differentiation is increasingly decisive. Vendors that combine high sensitivity with low false-alarm rates and ease-of-use (including validated workflows for Zone II–Zone IV screening) command premium positioning. Recent product advances — from trajectory-aware threat qualification to ultra-sensitive sensor arrays — raise the performance bar and create migration paths for facilities currently relying on manual screening or legacy devices.
-
Integration with facility design and workflow matters. Buyers prefer systems that align with MRI room layouts, do not impede throughput, and integrate with access control or digital incident-logging systems. Portability, wall-mounted units, and portal solutions each respond to distinct operational needs — and the optimal configuration often combines multiple device classes.
-
Aftermarket and service economics tilt procurement decisions. Given the critical safety role of these systems, total cost of ownership (TCO), calibration schedules, on-site service capabilities, and validation documentation are as influential as headline price.
Competitive landscape: profiles and positioning
-
CEIA USA — an established manufacturer with validated portable models for Zone 4 screening. CEIA’s emphasis on certified, portable detectors positions it strongly with institutions prioritizing validated workflows and field-proven reliability.
-
Kopp Development — offers the SAFESCAN® FerrAlert™ family, spanning wall-mounted, mobile and portal options. Kopp’s product breadth allows tailored deployments across varied clinical footprints, appealing to customers that prefer single-vendor standardization for MRI safety.
-
Fujidenolo — Japan-based developer of the MAGGUARD® series with high-sensitivity iMus sensors across handheld and wall-mounted formats. Fujidenolo’s sensor-level innovation is a differentiator in environments where very low-threshold ferrous detection is required.
-
ITEL Telecomunicazioni — integrates ferromagnetic detection into broader MRI facility installations. Their system-level approach resonates with parties undertaking new-builds or full-suite retrofits.
-
Metrasens — UK leader for advanced ferromagnetic screening with solutions tailored for Zone II patient screening through to Zone IV control. Metrasens’ portfolio and technical depth have made it a reference vendor in higher-acuity imaging centers and research hospitals.
-
Biodex Medical Systems — provides handheld SuperWand® devices with 360° detection and pinpoint accuracy. Biodex’s emphasis on ergonomics and detection fidelity makes it a choice for high-throughput screening workflows.
-
IRadimed — pioneers threat qualification via motion and trajectory prediction (TruSense™), optimizing detection specificity to reduce false alarms. This class of intelligence-driven detection is increasingly sought after where alarm fatigue and throughput are critical.
-
Groupe BIOMEDIQA and Nanjing Cloud Magnet — represent regionally strong suppliers with competitive offerings in ferromagnetic and metallic detection tailored to local cost and service dynamics. Their presence underscores the geographic fragmentation and local-service advantage that buyers must weigh.
What the PW Consulting report contains (practical components)
-
Market sizing and trajectory — a year-by-year view (2020–2025 historical base; 2026–2032 forecast) and scenario analyses that stress-test adoption under different hospital-capex and safety-regulation scenarios.
-
Segmentation by device type, application setting, and region — with qualitative implications for procurement and deployment (note: granular region/application share tables are reserved for the full report to preserve proprietary model integrity).
-
Vendor scorecards — independent evaluation across technology, service footprint, regulatory validation, price position, and aftermarket economics.
-
Technology deep-dive — sensitivity trade-offs, false-alarm mitigation strategies, sensor architectures, and integration patterns for portal, wall-mounted, mobile, and handheld classes.
-
Buyers’ playbook — a step-by-step procurement framework covering RFP language, validation protocols, pilot designs, installation checklists, and training/maintenance schedules to shorten time-to-value.
-
M&A and partnership heat map — targets and capabilities alignment for supplier consolidation, software upgrades, and geographic expansion.
-
Risk matrix and mitigation — regulatory, supply-chain, and clinical-adoption risks with prioritized mitigation steps for 2026 planning cycles.
Strategic implications and recommended actions for 2026
-
For hospital procurement leaders: convert risk-avoidance rhetoric into procurement-grade specifications. Require vendor evidence of false-alarm rates under representative patient traffic and insist on documented Zone-based validation. Bundle service contracts and consider multi-year calibration agreements to reduce TCO variability.
-
For vendor product teams: prioritize sensor-intelligence and interoperability. Investments in trajectory-aware algorithms or machine-learning filters that reduce nuisance alarms will have disproportionate commercial payoff. Equally important: modular hardware designs that allow field upgrades to sensing firmware can extend device lifecycles and customer lock-in.
-
For mid-sized vendors: pursue selective partnerships or acquisitions that expand service footprints and after-sales capabilities. Given the market concentration among top vendors, scale in service and distribution is a defensive necessity to compete on larger institutional contracts.
-
For private equity and corporate development: identify bolt-on targets that supply complementary sensing tech, access to regulated markets, or validated clinical workflows. Targets should improve either recurring revenue (service/certification) or accelerate entry into underpenetrated facility categories.
-
For integrators and facility planners: embed detection selection into MRI room design from day one. Retrofitting often creates suboptimal traffic flows and increases total installation cost; early alignment yields better procurement leverage and safer operational processes.
Key risks and leading indicators to monitor
-
Regulatory change — any tightening of MRI safety standards or mandatory screening protocols would accelerate replacement cycles; conversely, softer regulatory regimes slow adoption. Track proposed guidance from healthcare authorities and imaging societies closely.
-
False alarm economics — if alarm reduction technologies do not deliver in-field performance, buyers will delay procurement. Monitor independent field validation studies and real-world uptime/false-alarm metrics.
-
Service network availability — warranty claims and calibration lead times materially affect adoption. Keep a close watch on vendor service footprints and third-party calibration ecosystems.
-
Commoditization pressure — as lower-cost regional offerings scale, price pressure may compress margins. Vendors with strong differentiation (validated performance, service economics, or system-level integration) will be insulated.
How to use the full report to sharpen 2026 execution
-
Use the vendor scorecards to run a short-listing exercise for RFPs — replace marketing claims with objective, PW-validated criteria.
-
Run a 90-day pilot plan using our recommended measurement framework to validate vendor performance against your specific patient mix and room layouts.
-
Leverage the M&A heat map to identify consolidation opportunities that can immediately expand service reach or sensor IP without diluting product roadmaps.
-
Adopt the buyers’ playbook to reduce procurement cycles and ensure installations meet both clinical and compliance requirements the first time.
Our full MRI Metal Detector Market report contains the granular regional splits, device-class shares, and vendor financial benchmarks that underpin the strategic recommendations above. These elements are intentionally withheld from this preview to preserve the actionable value of the complete study. For procurement teams, vendor strategists, and investors preparing for 2026, the full analysis converts market-level conviction into executable plans.
To obtain the complete report — including year-by-year market figures, detailed segmentation, vendor financials, and our proprietary vendor scoring matrix — visit the PW Consulting market page or contact our advisory desk for a briefing tailored to your operational context.
For detailed analysis of this topic, please visit the official page: MRI Metal Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Infrared Heaters Market to Reach USD 3,740 Million in 2025 with 5.6% CAGR
By pmarketresearch, 2026-07-09
Infrared Heaters Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused, decision-oriented preview of our Infrared Heaters Market study (base year: 2025; historical window: 2020–2025; forecast horizon: 2026–2032). This briefing explains why C-suite teams, corporate strategy groups, and investors should prioritize the study’s insights when setting 2026 initiatives — from product roadmaps and manufacturing footprints to M&A screens and regulatory compliance programs. The goal here is to demonstrate the depth and actionable orientation of the research while preserving the discrete, segment-level intelligence that makes the full report a must-read for executable strategy.
Infrared Heaters Market
Market pulse: growth trajectory you can build plans around
-
Momentum: After a period of steady expansion through the early 2020s, the global infrared heaters market reached a material inflection point by 2025. Our model benchmarks the market at USD 3,740 Million in 2025 and projects continued growth into the forecast window (USD 3,941.04 Million in 2026 and reaching approximately USD 5,476.69 Million by 2032).
Infrared Heaters Market -
Underlying rate: The forecasted compound annual growth rate (CAGR) for 2026–2032 is 5.6% — a baseline that supports mid-single-digit organic growth planning, while leaving room for upside from product innovation, regional expansion, and strategic M&A.
Infrared Heaters Market -
Market structure: Concentration metrics indicate a moderately concentrated competitive set (CR3 ~45%, CR5 ~50%), signaling a marketplace where a handful of established players exert meaningful influence, but where targeted differentiation and channel strategies can still unlock outsized returns.
Why this study matters for 2026 strategic choices
-
Decision relevance: The analysis directly maps quantitative forecasts to discrete strategic levers companies must decide in 2026 — pricing, product investments, distribution shifts, and capital allocation sequences — enabling boards to convert market trends into prioritized initiatives.
-
Timing advantage: The immediate 2026 planning cycle sits at the transition from post-pandemic demand normalization to a new phase of energy-conscious retrofit and outdoor-living adoption. Our timing-sensitive scenario planning helps executives choose between “fast follow” and “first mover” postures aligned with finite engineering and sourcing windows.
-
Risk calibration: The study includes sensitivity analyses for raw material cost shocks, regulatory tightening, and incentive regime changes — critical inputs for 2026 capex approvals and multi-year supplier contracts.
What the report delivers — practical, executable modules
-
Revenue and demand model: A live financial model (USD Million) covering 2020–2032 with top-down and bottom-up validation, plus configurable scenario toggles to test price, share, and adoption assumptions.
-
Technology and product map: Comparative analysis of quartz, ceramic, carbon and halogen architectures, with an applied maturity / cost curve and implementation timelines that inform R&D prioritization and SKU rationalization.
-
Go-to-market playbooks: Tailored recommendations for OEMs, branded consumer players, HVAC integrators, and industrial suppliers including channel segmentation logic, pricing bands, and promotional mixes that align with 2026 budget cycles.
-
Supply-chain stress tests: Supplier tiering, critical-bill-of-material exposure, and cost-pass-through models that quantify margin impact under commodity and logistics shocks.
-
Regulatory and compliance roadmap: Actionable checklists and timelines for compliance with emerging environmental product declarations (EPDs) and energy-efficiency mandates active in 2026, plus certification strategies to minimize go-to-market delays.
-
M&A and partnership scorecards: A bespoke screening tool to prioritize targets and partners by strategic fit, integration complexity, and value-creation horizon — ideal for private equity and corporate development teams.
-
Commercial pilots and ROI templates: Plug-and-play templates for rapid local market pilots (outdoor hospitality, light industrial, retrofit) and an ROI calculator that models payback under real-world operating profiles.
Competitive landscape — how to interpret the field
-
TPI Corporation (Danvers, MA, USA) — Known for industrial infrared process equipment and the Fostoria line of electric infrared systems, TPI is a go-to for manufacturing and commercial process heat solutions. Their strength lies in engineered systems and aftermarket support.
-
Infratech (Gardena, CA, USA) — A premium U.S.-manufactured supplier focused on residential and commercial outdoor electric infrared heaters. Their product updates and catalog refreshes in 2026 underscore continued demand in outdoor hospitality and premium residential segments.
-
Solaronics, Inc. (Omaha, NE, USA) — Specializes in gas-fired and electric infrared radiant heaters for industrial space heating. Their active presence at trade shows signals a push into specification channels.
-
Tansun (Birmingham, UK) — A British manufacturer with a diversified product set across domestic, industrial, and commercial markets. Tansun’s value proposition emphasizes localized manufacturing and specification-grade products.
-
Reznor (O’Fallon, MO, USA) — A recognized name in gas-fired and electric radiant unit heaters for industrial/commercial buildings; their 2026 VZ series launch targets cost-sensitive commercial buyers seeking economy-class solutions.
-
Dr. Infrared Heater (Chicago, IL, USA) — Focused on energy-efficient portable and outdoor electric units for consumer markets; their product breadth supports channel penetration in big-box retail and e-commerce.
-
Havells (New Delhi, India) — A major electrical manufacturer offering electric infrared heaters for residential and commercial use, with a distribution footprint that supports rapid national scale in high-growth markets.
-
Stiebel Eltron (Allendale, NJ, USA) — Known for energy-efficient electric heating solutions and a credible brand for commercial applications; active trade-show engagement in 2026 signals a push for specification-level wins.
-
Comfort Zone (USA) — Consumer-oriented supplier with a focus on electric infrared products for the home; plays primarily in mid-market priced channels.
-
Honeywell (Charlotte, NC, USA) — Offers integrated infrared heating solutions across commercial and industrial use cases; leverages systems integration, controls, and cross-selling into broader building automation suites.
Strategic implication: with CR3 around 45% and CR5 close to 50%, incumbents hold strong positionings but there is meaningful room for challengers who combine product differentiation, channel specialization, or regional manufacturing to shave time-to-market and margin.
Emerging dynamics (2025–2026) that should shape 2026 playbooks
-
Raw material shocks: Ceramic emitter materials saw price jumps (approx. +14% in 2025) and carbon-fiber elements rose by roughly +21% due to supply disruptions. These cost moves materially affect relative unit economics across product types and should inform sourcing strategies and hedging tactics for 2026 procurement cycles.
-
Regulatory tightening: Federal and state activity in 2026 around environmental product declarations and energy-efficiency mandates is already influencing product design and certification pathways. Early alignment with EPD and efficiency testing shortens commercialization timelines and reduces rework risk.
-
Incentive landscape: Infrared heaters are not eligible for federal tax credits or rebates under the 2026 iteration of the Inflation Reduction Act, which means manufacturers and channel partners must avoid relying on end-user subsidy assumptions when building value propositions or payback models.
-
Market signaling from competitors: Product launches and trade-show activity in early 2026 (including Reznor’s VZ series, Solaronics’ AHR Expo presence, Infratech’s catalog refresh, and Stiebel Eltron’s ASPE showcase) indicate a move toward both economy and specification-tier segmentation — a bifurcation that smart players can exploit.
Strategic scenarios and recommended moves for 2026
-
Base-case (aligned with 5.6% CAGR): Prioritize margin protection. Actions: lock multi-year contracts with key emitter suppliers, accelerate certification for the most profitable SKUs, and deploy a targeted marketing fund to protect channel share in core markets.
-
Upside case (innovation-led): Invest in differentiated emitter technology and connected controls; pilot premium outdoor hospitality packages; pursue one bolt-on acquisition to accelerate channel access. Use the report’s M&A scorecard to prioritize targets that provide near-term revenue synergies.
-
Downside case (demand or cost shock): Implement a triage program to defer low-return SKUs, renegotiate logistics terms, and shift promotional focus to retrofit and commercial specification channels that deliver steadier order books. Activate contingency sourcing from alternate supplier geographies.
Next steps — how PW Consulting turns this preview into your 90-day plan
-
Commission a tailored executive briefing: We translate the market model into a 90-day decision pack with prioritized initiatives, estimated investment, and expected ROI.
-
Run a supplier stress-test workshop: Map your bill-of-material exposures against the raw material scenarios in the study and produce an actionable mitigation plan for procurement and engineering.
-
Deploy an M&A diligence sprint: Use our M&A screening tool and target shortlist to run rapid commercial and integration diligence for up to three targets within 60 days.
-
Implement go-to-market pilots: We design two commercial pilots (one outdoor hospitality, one industrial retrofit) that include a P&L, channel commitments, and measurable outcomes to validate scaling decisions in 2026.
For strategy teams preparing budgets and capital allocations in 2026, the difference between a reactive posture and a proactive, value-capturing plan will hinge on timely access to the granular, segment-level intelligence our full report provides — segmented adoption curves, regional demand matrices, SKU-level cost-breakdowns, and downloadable financial models. Access the complete Infrared Heaters Market report on PW Consulting’s site to obtain the detailed tables, dashboards, and executable templates that power board-level decisions.
For detailed analysis of this topic, please visit the official page: Infrared Heaters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrogenated MDI Market Poised for 5.22% CAGR Through 2032
By pmarketresearch, 2026-07-09
Hydrogenated MDI (H12MDI/HMDI) Market — Strategic Prelude for 2026 Decision-Makers
Executive snapshot
As PW Consulting’s Chief Industry Analyst, I present a concise strategic preview of our comprehensive Hydrogenated MDI Market study (base year: 2025; historical: 2020–2025; forecast: 2026–2032). The market’s steady expansion — underpinned by a compound annual growth rate (CAGR) of approximately 5.22% — is reshaping supplier strategies, downstream formulations, and capital allocation choices across polyurethane value chains. Measured in USD (Million), the market has grown from roughly USD 359 million in 2020 to about USD 491 million in 2025 and is projected to approach roughly USD 696 million by 2032. This trajectory signals meaningful, sustained opportunity for suppliers, converters, and end-users who can navigate supply, regulatory, and technology inflection points.
Hydrogenated MDI Market
Why this preview matters for 2026 planning
-
Investment timing: With mid-decade capacity additions and targeted product roadmaps by key producers, 2026 is a pivotal year to decide whether to secure long-term offtake, invest in backward/forward integration, or prioritize alternative chemistries.
Hydrogenated MDI Market -
Commercial positioning: The market’s structure — notably its high top-tier concentration — rewards scale, integrated feedstock strategies, and differentiated technical support. Our report quantifies concentration metrics and maps how these translate into pricing leverage, logistics resilience, and customer lock-in.
Hydrogenated MDI Market -
Regulatory and safety governance: Diisocyanate classification continues to tighten global handling standards; companies that preemptively invest in compliant processes and training will reduce operational risk and gain access to premium industrial and coatings segments.
Market dynamics: what is actually driving growth
The demand profile for hydrogenated MDI stems from a convergence of technical performance requirements and sustainability pressures. H12MDI/HMDI’s cycloaliphatic character offers improved light stability, lower yellowing, and enhanced mechanical performance relative to many aromatic alternatives — making it the material of choice for durable coatings, premium foams, elastomers, and specialty adhesives. Simultaneously, downstream trends — waterborne systems, low-VOC regulations, and electrification-driven automotive interiors — are expanding use cases for hydrogenated diisocyanates.
-
End-market pull: Automotive, architectural and industrial coatings, and high-performance polyurethane systems are key demand engines. Shifts to waterborne and low-VOC formulations increase the technical premium commanded by hydrogenated variants.
-
Supply-side adjustments: Recent capacity initiatives and producer-led vertical integration are reducing structural supply risk in some regions while concentrating market power. These moves will influence contract terms, spot availability, and grade diversity through 2032.
-
Regulatory overlay: Global diisocyanate regulations (notably in Europe and reflected in industry associations’ guidance) create elevated compliance costs and handling requirements. Firms with advanced safety systems and training protocols can convert regulatory compliance into commercial advantage.
Competitive landscape — players and strategic posture
The hydrogenated MDI market exhibits significant concentration at the top, and strategic intent among incumbents is clear. Leading manufacturers combine product portfolios, branded grades, and technical services to defend premium segments and extend applications into coatings, dispersions, and specialty foams.
-
Covestro AG (Leverkusen, Germany) — a recognized provider of hydrogenated MDI grades (Desmodur W family). Covestro competes on grade breadth and application know-how, targeting polyurethane elastomers, adhesives, and coating systems where weathering and aesthetic longevity are mission-critical.
-
Evonik Industries AG (Essen, Germany) — markets high-performance crosslinkers (e.g., VESTANAT H12MDI) and emphasizes light-stable, dispersion-friendly chemistries for premium coatings and advanced polyurethane systems. Evonik’s strength lies in coupling specialty chemistries with formulation science.
-
Wanhua Chemical Group Co., Ltd. (Yantai, China) — notable for operational scale and integration. Wanhua is an industrial-scale HMDI producer with strategic capacity in China and an active program to expand hydrogenated isocyanate output. Recent public filings and presentations demonstrate a concerted move to capture growing demand in coatings and automotive applications.
These incumbents are not merely competing on tonnage; they are optimizing feedstock integration, grade differentiation (viscosity, functionality, and impurity profiles), and downstream partnerships. The result is a market where the top three players control a majority share, and the top five capture a substantial supermajority — a configuration that shapes contract terms and innovation pathways.
Recent developments and their strategic implications
-
Capacity expansions: Announcements around increasing hydrogenated MDI output are material. Expansions on the order of tens of thousands of tonnes annually — when executed — change regional supply balances and open opportunities for new formulations that had previously been constrained by availability.
-
Technical outreach: Industry presentations highlighting hydrogenated MDI as an enabler for waterborne dispersions and low-VOC coatings suggest a proactive commercial pivot toward environmentally driven formulations. This is an early signal that producers view coatings and dispersions as growth vectors, not just niche specialties.
-
Integration and feedstock security: Firms operating integrated MDA hydrogenation technology and broad isocyanate capacity are better positioned to manage margin volatility. Integration reduces feedstock exposure and supports premium grade development for advanced applications.
-
Compliance and safety: Regulatory pressures on diisocyanates are increasing compliance costs and creating entry barriers for smaller converters. Those that proactively implement robust handling and training systems will gain preferential access to customers prioritizing supply-chain resilience.
Core takeaways for 2026 corporate action
-
Sourcing strategy: Negotiate flexibility into offtake agreements — blends of firm volumes and indexed spot exposure protect against both shortage-driven price spikes and margin compression from new capacity.
-
Product roadmap prioritization: Invest in formulations that exploit hydrogenated MDI’s light stability and low-VOC compatibility. Winning formulations will command premium pricing in segments where performance and aesthetics matter.
-
CapEx and partnership evaluation: For chemical producers, evaluate selective capacity additions in light of forecast demand growth and competitor expansions. For converters, consider strategic alliances or equity partnerships to secure feedstock access.
-
Regulatory readiness: Allocate resources to safety, worker training, and compliance documentation now; delay risks lost contracts and costly retrofits later.
-
Distribution and logistics: Optimize warehousing and transport for specialized grades (low-viscosity, stabilized products) to avoid formulation disruptions and support just-in-time manufacturing for coatings and adhesives customers.
What the full PW Consulting report delivers (practical, executable content)
Our complete Hydrogenated MDI Market study is designed as an operational playbook for 2026 and beyond. It contains:
-
Validated top-line market sizing and a transparent forecast model (2026–2032) benchmarked to historical performance (2020–2025) — all figures presented in USD (Million) with scenario sensitivities for low-, base-, and high-demand pathways.
-
Competitive scorecards that assess production footprints, branded grades, technical service capabilities, and strategic initiatives for the leading suppliers.
-
Commercial templates: negotiation levers for offtake contracts, risk-adjusted pricing models, and inventory optimization frameworks adapted to hydrogenated MDI’s supply characteristics.
-
Regulatory and safety playbooks: compliance cost estimates, certification checklists, and workforce training roadmaps tailored to diisocyanate handling requirements.
-
Go-to-market matrices mapping technical features (e.g., light stability, reactivity profiles) to prioritized end-markets and advisory recommendations for product development sequencing.
-
Investment diligence annexes: capex sizing, break-even analysis, and sensitivity testing for greenfield and brownfield expansions.
Because this preview follows a deliberate “trailer” approach, we have withheld granular subsegment tables and region/application percentage breakdowns from this summary. Those detailed matrices, supplier-by-supplier volumes, and pricing bands are included in the full report to support procurement, R&D prioritization, and M&A diligence.
How to use this analysis in boardroom decisions
-
Frame 2026 budget cycles around three scenarios (conservative, baseline, accelerated) using the report’s forecast outputs and trade-off analytics to justify capital and R&D spend.
-
Use the supplier scorecards to benchmark current partners and identify gaps in feedstock security or technical support; consider dual-sourcing or strategic inventory buffers where exposure is unacceptable.
-
Leverage regulatory playbooks to lower insurance and compliance costs—quantified readiness reduces both near-term operating risk and long-term liability.
Concluding perspective
The hydrogenated MDI market is maturing from a technically niche specialty into a structurally important segment of the polyurethane value chain. With a steady CAGR of roughly 5.22% and clear supply-side moves, 2026 is the year to translate strategic intent into procurement terms, product roadmaps, and capital commitments. PW Consulting’s full study equips decision-makers with the granular data, contract tools, and regulatory blueprints needed to act confidently. For companies that move early — securing feedstock, aligning formulations to low-VOC trends, and hardening compliance systems — the next six years offer both defensible growth and the chance to command a premium in high-value applications.
To access the detailed regional and application breakdowns, supplier volumes, and the actionable annexes referenced above, please visit our report page or contact the PW Consulting research team. The preview establishes the strategic horizon — the full report provides the tactical map.
For detailed analysis of this topic, please visit the official page: Hydrogenated MDI Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com