

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: MRI Metal Detector Market to reach USD 301.5M by 2032 at 4.5% CAGR

MRI Metal Detector Market 2026: Strategic Imperatives for Procurement, Product, and M&A Leaders
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise strategic preview of our comprehensive MRI Metal Detector Market study. This briefing synthesizes the macro trajectory, competitive dynamics, technology inflection points, and the practical decision levers that will determine winners and losers during 2026 — the pivotal year when many healthcare systems and vendors will translate cautious experimentation into scaled deployment.
MRI Metal Detector Market
Why this study matters for 2026 decisions
-
Predictable growth with tactical complexity: The MRI metal detector market has matured into a steady-growth segment. Using 2025 as the analytical base year, our market model shows a consistent expansion through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of approximately 4.5%. By 2032 the market approach(es) the low hundreds of millions (USD), reflecting broad but measured adoption across health systems, imaging centers, and specialist facilities.
MRI Metal Detector Market -
Concentration and opportunity: Market concentration is meaningful — the top three vendors control roughly two-thirds of market revenues, and the top five capture over three-quarters. That profile creates both barriers for new entrants and clear M&A/partnership opportunities for mid-sized players seeking scale or complementary capabilities.
MRI Metal Detector Market -
Decision timing matters: 2026 will be a year of shifting priorities — from pilot installations and regulatory alignment to procurement cycles for retrofit and new-build MRI suites. Organizations that align procurement timing, validation protocols, and vendor selection criteria to this market rhythm will minimize risk while securing favorable commercial terms.
Market dynamics: drivers, frictions, and inflection points
-
Safety and risk management are the primary demand drivers. Incidents involving ferromagnetic objects in MRI environments remain a reputational and liability concern for hospitals and imaging providers. The straightforward value proposition — reducing patient and staff exposure to ferromagnetic hazards — keeps capital allocation for detection systems on the agenda.
-
Technology differentiation is increasingly decisive. Vendors that combine high sensitivity with low false-alarm rates and ease-of-use (including validated workflows for Zone II–Zone IV screening) command premium positioning. Recent product advances — from trajectory-aware threat qualification to ultra-sensitive sensor arrays — raise the performance bar and create migration paths for facilities currently relying on manual screening or legacy devices.
-
Integration with facility design and workflow matters. Buyers prefer systems that align with MRI room layouts, do not impede throughput, and integrate with access control or digital incident-logging systems. Portability, wall-mounted units, and portal solutions each respond to distinct operational needs — and the optimal configuration often combines multiple device classes.
-
Aftermarket and service economics tilt procurement decisions. Given the critical safety role of these systems, total cost of ownership (TCO), calibration schedules, on-site service capabilities, and validation documentation are as influential as headline price.
Competitive landscape: profiles and positioning
-
CEIA USA — an established manufacturer with validated portable models for Zone 4 screening. CEIA’s emphasis on certified, portable detectors positions it strongly with institutions prioritizing validated workflows and field-proven reliability.
-
Kopp Development — offers the SAFESCAN® FerrAlert™ family, spanning wall-mounted, mobile and portal options. Kopp’s product breadth allows tailored deployments across varied clinical footprints, appealing to customers that prefer single-vendor standardization for MRI safety.
-
Fujidenolo — Japan-based developer of the MAGGUARD® series with high-sensitivity iMus sensors across handheld and wall-mounted formats. Fujidenolo’s sensor-level innovation is a differentiator in environments where very low-threshold ferrous detection is required.
-
ITEL Telecomunicazioni — integrates ferromagnetic detection into broader MRI facility installations. Their system-level approach resonates with parties undertaking new-builds or full-suite retrofits.
-
Metrasens — UK leader for advanced ferromagnetic screening with solutions tailored for Zone II patient screening through to Zone IV control. Metrasens’ portfolio and technical depth have made it a reference vendor in higher-acuity imaging centers and research hospitals.
-
Biodex Medical Systems — provides handheld SuperWand® devices with 360° detection and pinpoint accuracy. Biodex’s emphasis on ergonomics and detection fidelity makes it a choice for high-throughput screening workflows.
-
IRadimed — pioneers threat qualification via motion and trajectory prediction (TruSense™), optimizing detection specificity to reduce false alarms. This class of intelligence-driven detection is increasingly sought after where alarm fatigue and throughput are critical.
-
Groupe BIOMEDIQA and Nanjing Cloud Magnet — represent regionally strong suppliers with competitive offerings in ferromagnetic and metallic detection tailored to local cost and service dynamics. Their presence underscores the geographic fragmentation and local-service advantage that buyers must weigh.
What the PW Consulting report contains (practical components)
-
Market sizing and trajectory — a year-by-year view (2020–2025 historical base; 2026–2032 forecast) and scenario analyses that stress-test adoption under different hospital-capex and safety-regulation scenarios.
-
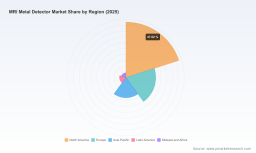
Segmentation by device type, application setting, and region — with qualitative implications for procurement and deployment (note: granular region/application share tables are reserved for the full report to preserve proprietary model integrity).
-
Vendor scorecards — independent evaluation across technology, service footprint, regulatory validation, price position, and aftermarket economics.
-
Technology deep-dive — sensitivity trade-offs, false-alarm mitigation strategies, sensor architectures, and integration patterns for portal, wall-mounted, mobile, and handheld classes.
-
Buyers’ playbook — a step-by-step procurement framework covering RFP language, validation protocols, pilot designs, installation checklists, and training/maintenance schedules to shorten time-to-value.
-
M&A and partnership heat map — targets and capabilities alignment for supplier consolidation, software upgrades, and geographic expansion.
-
Risk matrix and mitigation — regulatory, supply-chain, and clinical-adoption risks with prioritized mitigation steps for 2026 planning cycles.
Strategic implications and recommended actions for 2026
-
For hospital procurement leaders: convert risk-avoidance rhetoric into procurement-grade specifications. Require vendor evidence of false-alarm rates under representative patient traffic and insist on documented Zone-based validation. Bundle service contracts and consider multi-year calibration agreements to reduce TCO variability.
-
For vendor product teams: prioritize sensor-intelligence and interoperability. Investments in trajectory-aware algorithms or machine-learning filters that reduce nuisance alarms will have disproportionate commercial payoff. Equally important: modular hardware designs that allow field upgrades to sensing firmware can extend device lifecycles and customer lock-in.
-
For mid-sized vendors: pursue selective partnerships or acquisitions that expand service footprints and after-sales capabilities. Given the market concentration among top vendors, scale in service and distribution is a defensive necessity to compete on larger institutional contracts.
-
For private equity and corporate development: identify bolt-on targets that supply complementary sensing tech, access to regulated markets, or validated clinical workflows. Targets should improve either recurring revenue (service/certification) or accelerate entry into underpenetrated facility categories.
-
For integrators and facility planners: embed detection selection into MRI room design from day one. Retrofitting often creates suboptimal traffic flows and increases total installation cost; early alignment yields better procurement leverage and safer operational processes.
Key risks and leading indicators to monitor
-
Regulatory change — any tightening of MRI safety standards or mandatory screening protocols would accelerate replacement cycles; conversely, softer regulatory regimes slow adoption. Track proposed guidance from healthcare authorities and imaging societies closely.
-
False alarm economics — if alarm reduction technologies do not deliver in-field performance, buyers will delay procurement. Monitor independent field validation studies and real-world uptime/false-alarm metrics.
-
Service network availability — warranty claims and calibration lead times materially affect adoption. Keep a close watch on vendor service footprints and third-party calibration ecosystems.
-
Commoditization pressure — as lower-cost regional offerings scale, price pressure may compress margins. Vendors with strong differentiation (validated performance, service economics, or system-level integration) will be insulated.
How to use the full report to sharpen 2026 execution
-
Use the vendor scorecards to run a short-listing exercise for RFPs — replace marketing claims with objective, PW-validated criteria.
-
Run a 90-day pilot plan using our recommended measurement framework to validate vendor performance against your specific patient mix and room layouts.
-
Leverage the M&A heat map to identify consolidation opportunities that can immediately expand service reach or sensor IP without diluting product roadmaps.
-
Adopt the buyers’ playbook to reduce procurement cycles and ensure installations meet both clinical and compliance requirements the first time.
Our full MRI Metal Detector Market report contains the granular regional splits, device-class shares, and vendor financial benchmarks that underpin the strategic recommendations above. These elements are intentionally withheld from this preview to preserve the actionable value of the complete study. For procurement teams, vendor strategists, and investors preparing for 2026, the full analysis converts market-level conviction into executable plans.
To obtain the complete report — including year-by-year market figures, detailed segmentation, vendor financials, and our proprietary vendor scoring matrix — visit the PW Consulting market page or contact our advisory desk for a briefing tailored to your operational context.
For detailed analysis of this topic, please visit the official page: MRI Metal Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com