

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Blood Bank Refrigerators Market to Reach USD 2,611.6M by 2032 at 5.45% CAGR

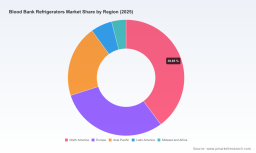
Blood Bank Refrigerators Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
PW Consulting’s latest market research on Blood Bank Refrigerators synthesizes five years of historical performance (2020–2025) and delivers a forward-looking forecast through 2032, with 2025 established as the base year. The market is on a steady expansion path: total industry revenues rose from approximately USD 1,445 Million in 2020 to about USD 1,829 Million in 2025 and are projected to accelerate to roughly USD 1,986 Million in 2026, reaching an estimated USD 2,612 Million by 2032. The compound annual growth rate (CAGR) across the forecast window reflects a mid-single-digit expansion of 5.45%—a rate that supports both conservative planning and selective growth plays.
Blood Bank Refrigerators Market
Why this research matters in 2026
As healthcare systems recalibrate after a prolonged period of capital discipline and supply-chain reconfiguration, blood management remains a non-discretionary priority. The refrigerator segment sits at the intersection of clinical risk mitigation, regulatory compliance, and hospital operational efficiency. For manufacturers, hospital procurement leads, laboratory networks, and private equity investors evaluating healthcare infrastructure plays, this study provides the analytical substrate required to prioritize investments, refine go-to-market strategies, and quantify near-term service and aftermarket opportunities.
Blood Bank Refrigerators Market
Key market dynamics shaping 2026 strategy
-
Regulatory and standards pressure — Blood bank refrigerators are regulated as medical devices under multiple frameworks (including classification and quality systems requirements). Compliance with FDA device rules and European medical device regulations remains table stakes, while third-party standards programs (notably AABB’s SCoPE program) have become a de facto reassurance mechanism for clinical buyers. Expect procurement cycles to increasingly favor suppliers that can demonstrate robust conformity and certified performance under these regimes.
Blood Bank Refrigerators Market -
Clinical performance and cold-chain integrity — The clinical imperative to maintain a constant +4°C environment for whole blood and many blood components constrains product innovation to incremental advances that preserve reliability while improving monitoring and alarm systems. Remote telemetry, secure data logging, and third-party verification features are rising from desirable to required in many institutional tenders.
-
Operational efficiency and TCO focus — With constrained capital budgets, health systems emphasize total cost of ownership. Features such as energy efficiency, uptime guarantees, modular serviceability, and extended compressor warranties materially influence purchasing decisions. Energy-star or equivalent efficiency labeling and low-noise designs are increasingly influential in hospital and laboratory RFPs.
-
Regional demand patterns and procurement sophistication — While demand is global, adoption curves differ by end-user sophistication and regulatory expectations. Hospitals and blood banks remain the core end markets, with research laboratories and other clinical institutions forming a smaller but innovation-forward segment.
Competitive landscape — who matters and why
The vendor field combines global conglomerates with specialized medical refrigeration manufacturers. Competition is product- and compliance-driven; vendors that align product engineering with third-party certifications and strong local service footprints enjoy preferential access to large institutional contracts. Below are concise profiles of the market’s noteworthy participants, selected for their demonstrated product capabilities and recent market activity.
-
Thermo Fisher Scientific (Waltham, MA, USA) — A life-science heavyweight whose blood bank refrigerator portfolio (including AABB SCoPE-certified TSX Revco and TSX Blood Bank models) emphasizes regulatory alignment and enterprise procurement compatibility. Thermo Fisher’s scale supports integrated procurement offers combining refrigerators with broader laboratory cold-chain solutions.
-
Helmer Scientific (Waukesha, WI, USA) — Known for ENERGY STAR–compliant upright blood bank ranges (GX Solutions and Horizon Series) that balance AABB certification with energy efficiency and quiet operation. Helmer’s November 2025 recognition under a standards-compliance program reinforces its positioning among health systems prioritizing certified performance.
-
B Medical Systems (Luxembourg) — Focused on certified, scalable offerings for blood management with devices that meet EU regulatory classifications and FDA device rules while providing remote monitoring capabilities. Recent clinical user testimonials (collected in 2025 from major hospital users) underscore their field performance narrative, which is a persuasive asset in emerging market tenders.
-
Biomedical Solutions, Inc. (Waltham, MA, USA) — Marketed as purpose-built units for whole blood and components at clinically relevant temperatures. The company’s product claims stress compliance and operational fit for hospital and laboratory settings.
-
Kirsch Medical (Germany) — A Europe-based supplier emphasizing ISO 13485–aligned manufacturing and compliance, appealing to buyers with high regulatory scrutiny and those requiring clear audit trails for device selection.
-
Migal Scientific (USA) — Product differentiation centers on high-capacity upright models, advanced thermal technologies (e.g., expansion-valve systems), and extended compressor warranties—features that speak directly to uptime, reliability and lifecycle cost reduction.
-
Lab Repco (USA) — Focused on clinical refrigerators for standard hospital and lab use-cases, positioning for competitive pricing and practical serviceability.
-
PHCbi (Panasonic Healthcare) (Japan) — Offers Class IIa–certified medical devices for blood component storage. PHCbi’s product compliance lineage appeals to large hospital systems and purchasers seeking tried-and-tested global suppliers.
Notable recent developments and what they imply
-
Standards recognition for specific models (late 2025) increases vendor stickiness in institutional procurement—buyers will favor models with third-party program endorsements.
-
Multiple user testimonials published in 2025 highlight the market’s growing emphasis on real-world performance data. Manufacturers should invest in clinical validation programs and post-deployment case studies to accelerate tender wins.
-
Regulatory clarifications across jurisdictions continue to influence product design lifecycles. Vendors that proactively align R&D roadmaps with device classification changes will shorten time-to-market and reduce compliance rework costs.
Report contents — what PW Consulting delivers
This research is intentionally practical. It includes:
-
A quantitative market model (historical 2020–2025; forecast 2026–2032) expressed in USD Million, enabling scenario planning and revenue-at-risk computations for different investment horizons.
-
Regulatory and standards mapping that translates device classification, quality system obligations, and third-party testing programs into procurement risk matrices for manufacturers and buyers.
-
Vendor benchmarking—assessing product portfolios, certification status, field evidence and aftermarket strengths—to support supplier shortlists and sourcing strategies.
-
Go-to-market playbooks focused on eight actionable initiatives: channel optimization, service-part strategies, product feature prioritization (e.g., telemetry, energy efficiency), pricing levers, clinical evidence generation, regulatory roadmaps, and M&A screening criteria.
-
Scenario-based forecasts that help CFOs and strategy teams stress-test budgets under competing capital allocation and adoption pace assumptions.
Actionable recommendations for 2026
-
For manufacturers: prioritize investments in certified device portfolios and remote-monitoring capabilities. Partner with clinical sites to build performance dossiers that substantiate uptime and temperature-control claims—these are decisive in tender evaluations.
-
For hospital procurement teams: request documented third-party compliance evidence and demand lifecycle cost projections (energy, service, parts). Shortlist suppliers that can demonstrate both certification and local service coverage.
-
For investors and private equity: focus on firms with differentiated service models and recurring aftermarket revenue. The mid-single-digit CAGR creates space for consolidation, but value will accrue to players who can scale service operations and compliance capabilities quickly.
How to use this briefing in your 2026 planning
Use the headline market trajectory and the regulatory roadmap provided here to align product roadmaps, sales compensation, and inventory policies. Translate forecast ranges into procurement batch sizes and phase capital spend to capture both baseline replacement demand and incremental demand driven by efficiency upgrades. Leverage vendor benchmarking to reduce RFP friction and accelerate sourcing cycles.
Closing — the value of full access
This briefing demonstrates the strategic lines of action supported by PW Consulting’s data and expert analysis. The full report contains the granular segmentation, regional and application breakdowns, price and margin analysis, and an expanded competitive matrix that are intentionally withheld here to preserve the losing/winning tradecraft of competitive positioning. For procurement templates, segmented demand curves, and a downloadable vendor dossier with model-level specification comparisons, please consult the full report.
PW Consulting is prepared to brief executive teams, run supplier-selection workshops, and build bespoke financial scenarios that operationalize these insights for 2026 capital and commercial planning.
For detailed analysis of this topic, please visit the official page: Blood Bank Refrigerators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com