

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hydration Bottle Market to Grow at 6.5% CAGR Through 2032

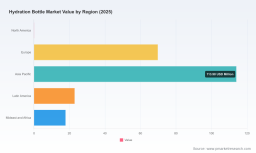
Hydration Bottle Market — 2026 Strategic Preview
PW Consulting’s Hydration Bottle Market study (base year 2025; historical 2020–2025; forecast 2026–2032) frames the sector at a defining inflection point. The report synthesizes high-frequency market data, supplier intelligence and regulatory mapping into an executive-grade playbook for decision-makers planning product, channel and M&A moves in 2026. This preview outlines why the study matters to corporate leaders and what actionable direction it provides — while reserving the granular segmentation tables and region/application splits for the full report.
Hydration Bottle Market
Why executives should care in 2026
-
Steady expansion with opportunity windows: The market trajectory through the forecast period is underpinned by multi-year compounding growth (CAGR 6.5%). That expansion is not uniform: pockets of premiumization, sustainability-driven premium demand and digital-enabled products are materially outpacing mature commodity segments. Knowing where to allocate growth investments is now a first-order strategic decision.
Hydration Bottle Market -
Concentration creates leverage: Market concentration is high — the top-three players capture a dominant share and the top-five an even larger proportion of value. That concentration intensifies competitive dynamics around brand, distribution and innovation, but it also creates M&A arbitrage opportunities for challengers and private capital seeking consolidation plays.
Hydration Bottle Market -
Regulatory and material regimes are reshaping cost and claims: Standards for BPA-free plastics, ISO-driven quality certification for stainless steel production and labeling obligations for any added electrolytes are all active constraints that need to be integrated into sourcing and R&D roadmaps if companies are to avoid compliance-driven product rework or market access delays.
What the research delivers — practical, decision-ready outputs
The PW Consulting study is structured to move beyond descriptive market graphs and into implementable strategy. Key deliverables include:
-
Rigorous market sizing and a transparent forecast engine: full time-series (2020–2032) with scenario layers (baseline, downside and upside) and sensitivity to material cost and channel mix shifts.
-
Competitive benchmarking and capability heatmaps: product portfolios, pricing ladders, channel footprints, manufacturing capabilities and patent/activity indicators for the leading manufacturers and notable challengers.
-
Go-to-market playbooks by archetype: tactical templates for premium D2C brands, mass-market retail players, private-label manufacturers and OEM channel partners including launch checklists, sample SKU portfolios and promotional calendar suggestions aligned to seasonal demand.
-
Supply chain and raw-material stress tests: scenario analysis that quantifies exposure to stainless-steel and high-performance plastics (e.g., Tritan) supply disruptions, lead-time risk, and pricing pass-through mechanics.
-
Regulatory compliance matrix: mapped obligations across major jurisdictions for material safety claims, manufacturing certifications and labeling requirements for value-added hydration products.
-
M&A and partnership target shortlists: prioritized sets of bolt-on targets and collaboration candidates, with preliminary valuation heuristics and integration risk ratings.
-
KPIs and monitoring dashboards: recommended metrics to track week-on-week and month-on-month (inventory days, SKU-level gross margin, channel CAC, consumer repeat rate), plus a data-sourcing guide for live monitoring.
Competitive landscape — what the leaders are doing
The market’s competitive architecture is shaped by a mix of outdoor-heritage brands, design-driven premium players and mass-market innovators. The report includes deep profiles and strategic analysis of core firms that shape the category:
-
CamelBak Products, LLC (Petaluma, CA): a leader in durability and outdoor-focused design; recent launches emphasize recycled-material collections that both meet consumer sustainability preferences and adjust supplier relationships toward circular material streams.
-
Hydro Flask (Boulder, CO): continues to dominate premium insulated stainless-steel demand; its 2024 launch of lightweight eco-focused lines signals a push to reconcile performance with portability and lower carbon footprint claims.
-
Nalgene (Rochester, NY): remains the reference brand for durable, BPA-free Tritan plastic bottles; product expansions and refreshes are being used to protect mass-market shelf presence and to defend against price-based private-label incursions.
-
Klean Kanteen (Boulder, CO): emphasizes food-grade, vacuum-insulated stainless steel and positions toward health-conscious consumers and institutional buyers who prioritize compliance and workplace sustainability programs.
-
Contigo (Chicago, IL): increasingly mixes convenience-driven design with tech-enabled offerings — its smart hydration bottle launched in 2024 points to an adjacent playbook where IoT features and digital services (hydration tracking) open recurring revenue and data-capture opportunities.
These public moves — from recycled-material launches to smart products — inform the report’s recommended strategic options for incumbents and challengers alike.
Materials, regulation and consumer dynamics — the operating environment
-
Materials regime: Stainless steel and Tritan plastics remain the dominant production substrates due to durability and scale economies. The report models cost curves and supplier concentration for each material class, allowing procurement teams to hedge exposure and design dual-sourcing strategies.
-
Regulatory overlay: Mandatory BPA-free and phthalate-free labeling in major markets, ISO 9001:2015 expectations for reusable stainless steel production facilities and nutrition/ingredient disclosure standards for electrolyte-enhanced hydration products require clear compliance pathways — not optional checkboxes.
-
Consumer preference vectors: Sustainability and reuse are persistent megatrends driving premium elevation; at the same time, digital convenience and health personalization (hydration tracking, added electrolytes) are emerging demand drivers that change price elasticity and lifetime value calculations.
Strategic implications for 2026 planning
-
Portfolio prioritization: We recommend a two-track product portfolio — defend core commodity SKUs while selectively investing in premium insulated and smart-enabled lines that deliver higher margin and stronger brand loyalty metrics.
-
Sourcing and certification: Short-term investments in dual-sourcing stainless-steel capacity and securing ISO quality certification reduce supply shock risk and shorten time-to-market for premium launches; include compliance timelines in 2026 CAPEX planning.
-
Channel mix and pricing: Expand D2C initiatives for premium launches to capture richer margin and data; preserve retail scale via tailored assortment and private-label partnerships in non-core channels. Use dynamic pricing pilots to measure elasticity across heritage and new product lines.
-
Digital + services playbook: For firms considering smart bottles, pilot programs should prioritize data privacy, recurring subscription models (hydration coaching or replacement caps) and integration with wellness platforms to accelerate payback.
-
M&A and portfolio optimization: Given the high CR3/CR5 concentration, there are defensible consolidation plays in niche insulation tech, material recycling capabilities and digital services — each target type has distinct integration risk and synergies quantified in the full study.
What to expect from the full report
The complete PW Consulting Hydration Bottle Market report provides chapter-level depth that supports boardroom decisions and 90-day execution plans. Highlights include:
-
Full forecast models with scenario toggles and download-ready spreadsheets for CFO stress-testing.
-
SKU-level margin templates and promotional elasticity matrices for CPG and retail teams.
-
Regulatory playbooks by jurisdiction and a supplier vetting toolkit for procurement teams.
-
Executive briefing slides and a one-day strategy workshop framework customized to your company’s profile.
Recommended next steps (90-day playbook)
-
Buy the full report and schedule a tailored executive briefing with PW Consulting to map the findings to your organization’s priorities.
-
Run a rapid internal audit of material and certification exposure; prioritize ISO alignment and dual sourcing within your Q3 procurement roadmap.
-
Initiate two product pilots in parallel — one premium insulated SKU sold via D2C and one smart-enabled cap as a limited release — using the report’s go-to-market templates to measure CAC and early repeat rates.
-
Identify consolidation targets in adjacent niches (recycling, IoT caps, insulation tech) and start preliminary outreach backed by the report’s M&A shortlists and valuation heuristics.
Closing
The hydration bottle category is no longer just a mass-market commodity. Underneath steady overall growth (historical to 2025 and projected across our forecast window) there are distinct, investable accelerants: sustainability, premium insulated performance and digital services. PW Consulting’s study translates those accelerants into executable playbooks — balancing defensible near-term actions with strategic capability investments that will determine winners in 2026 and beyond. For access to the full dataset, regional and application splits, and the downloadable forecasting model, refer to the full report and our accompanying executive workshop.
For detailed analysis of this topic, please visit the official page: Hydration Bottle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com