

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Mushrooms Market Set to Grow at 9.6% CAGR to 2032

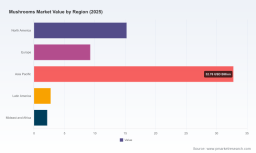
Mushrooms Market 2026: Strategic Imperatives for Executive Decision‑Makers
Between 2020 and 2025 the global mushrooms market moved from a sizeable base to a materially larger and more complex ecosystem. Our research shows the market expanded from roughly USD 41.8 billion in 2020 to about USD 62.2 billion in 2025. Using 2025 as the base year, PW Consulting projects the market will continue on a robust trajectory through our forecast window (2026–2032), with compound annual growth of 9.6% and an expected market size that approaches USD 118.2 billion by 2032. For executives making resource allocation, M&A, or new‑product decisions in 2026, these headline dynamics are not just background noise — they reframe strategic priorities.
Mushrooms Market
Why this study matters in 2026
-
Acceleration and scale: A near‑double market projection by 2032 implies that scale economies, capital intensity, and capacity timing will be decisive. Decisions on facility investments, automation, and distribution partnerships taken in 2026 will determine competitiveness throughout the next cycle.
Mushrooms Market -
Sustainability as a price of admission: Innovations such as peat‑free cultivation are no longer niche R&D headlines. Leading growers are embedding sustainable substrates and certification into their production roadmaps — a practical requirement for access to premium retail and institutional customers.
Mushrooms Market -
Supply‑side signal clarity: Industry reporting and grower surveys indicate modest year‑on‑year changes in crop volume and organic production trends. These operational signals should inform procurement strategies, contract length, and buffer stocking decisions rather than being treated as incidental.
-
Innovation hubs and networking: The calendar of trade events (European and Asian Mushroom Days, and emergent national expos) continues to concentrate new cultivation technologies, substrate innovation, and distribution models. Executives who prioritize participation will unlock partnership and licensing opportunities earlier.
What the report delivers — practical outputs for 2026 action
-
Transparent market sizing and forecast models: Base‑year 2025 calibration, historical analysis (2020–2025), and scenario‑based forecasts for 2026–2032 that combine price‑volume modeling with sensitivity analysis across key drivers.
-
Demand archetypes and product playbooks: Segmented demand profiles (fresh, value‑added, functional/ingredient, cosmetics, pharmaceutical R&D channels), with go‑to‑market templates for retailers, CPG incumbents, and ingredient suppliers.
-
Supply‑chain economics and cost curves: Benchmarks for cultivation CapEx/Opex, substrate sourcing options, energy and labor intensity by cultivation system, and automation break‑even calculations designed for boardroom decision packs.
-
M&A and partnership scorecards: A practical methodology for target prioritization, synergy sizing, and integration risk assessment tailored to both horizontal consolidation and vertical integration plays.
-
Regulatory and sustainability roadmaps: Actionable compliance checklists, certification pathways, and commercial levers associated with peat‑free and organic production that affect shelf access and pricing power.
-
Commercial deployment tools: Negotiation playbooks for long‑term offtake, supplier risk matrices, SKU rationalization templates, and channel margin models to accelerate commercialization.
Competition and market structure — where advantage will come from
The reported concentration metrics point to a moderately consolidated market: the three largest participants account for just over one‑third of market share, and the five largest just over forty percent. This structure creates dual strategic spaces: scale advantages for large integrated players and pockets of high margin opportunity for specialized operators who can command premium positioning or proprietary capabilities.
-
Integrated scale operators (examples): Major North American and European producers have focused on high‑throughput cultivation, cold‑chain logistics, and retail distribution relationships. Their playbooks emphasize capacity utilization, retail category management, and shelf presence.
-
Specialists and niche innovators (examples): Family‑run and boutique growers concentrating on specialty, organic, or exotic varieties are leveraging product differentiation, premium pricing, and e‑commerce channels. These firms are also the primary testbeds for substrate and cultivation innovation.
-
Contract manufacturers and substrate suppliers: Integrated groups that control both cultivation and substrate supply are extracting margin through vertical control and innovation in growing media (including peat alternatives), presenting attractive targets for strategic buyers wanting secure inputs.
PW Consulting’s competitive dossiers include concise strategic summaries for core industry players — their positioning, core capabilities, and plausible next moves — to support rapid competitor benchmarking and M&A screening.
Recent industry signals that should inform 2026 strategy
-
Trade‑show cadence: Europe and China remain focal points for product, equipment, and substrate innovation; newly emergent national expos are expanding industry connectivity in Asia and South Asia. These forums are primary channels for commercialization of cultivation and processing innovations.
-
Operational trends: National statistics indicate modest shifts in crop volumes year‑on‑year and a mixed trajectory for certified organic production. These operational data points should be used to stress‑test inventory and procurement assumptions rather than treated as static baselines.
-
Sustainability initiatives: The adoption of peat‑free production practices by leading producers is a structural change in European operations with cascading implications for substrate suppliers, input suppliers, and certification bodies.
-
Data transparency: Increasing public reporting by growers and national agricultural services is improving market visibility — enabling higher‑fidelity forecasting but also raising the bar for competitive response times.
How the C‑suite should use this intelligence in 2026
-
Prioritize capacity timing: Use our scenario models to decide whether to defer, accelerate, or scale facility investments given probable demand paths and cost inflation in inputs and energy.
-
Embed sustainability into product roadmaps: Convert sustainability commitments (e.g., peat‑free practices) into concrete product launches and procurement contracts to protect shelf access and price premiums.
-
Refine M&A filters: Apply our M&A scorecards to shortlist targets that deliver immediate synergies in distribution, substrate sourcing, or value‑added product lines; focus on bolt‑on deals that shorten time‑to‑market.
-
Operationalize risk: Incorporate crop volume and organic production trends into procurement and inventory policies; stress‑test counterparty concentration and logistics disruptions with scenario planning.
-
Commercial experiments: Run two‑quarter pilot programs for differentiated SKUs (functional ingredients, premium fresh, or shelf‑stable innovations) with pre‑tested margin levers and marketing playbooks from our templates.
Data & methodology — what’s in the black box
The study is anchored on a 2025 base year and a historical series spanning 2020–2025. Forecasts cover 2026–2032 and are presented under a dual approach: a primary deterministic forecast (price × volume by product family) and an overlay of three risk scenarios that stress test demand shocks, input cost inflation, and regulatory shifts. Research inputs include primary interviews with growers and processors, published national agricultural statistics, participation in industry trade forums, supply‑chain cost surveys, and audited company disclosures. To preserve commercial value for subscribers, the full report contains the granular segmentation tables, regional breakdowns, and channel mixes that informed the headline forecast.
Chapter preview (trailer)
- Executive summary and headline forecast
- Market sizing methodology and model mechanics
- Demand segmentation and buyer archetypes
- Supply‑side economics: cultivation, substrate, and processing
- Distribution and retail economics
- Regulation, certification, and sustainability scenarios
- Competitive landscape and company dossiers
- M&A playbook and valuation templates
- Commercial deployment toolkits and KPI dashboards
PW Consulting’s Mushrooms Market study is designed as a decision‑support instrument for strategy teams, corporate development, procurement, and operations groups. The headline market trajectory, material sustainability inflection points, and evolving supply‑chain economics together create a narrow window in 2026 to secure advantaged positions. For the tables, datasets, and executable templates that underpin our model — including the full segmentation and regional breakdowns omitted here — please consult the full PW Consulting report and data pack.
For detailed analysis of this topic, please visit the official page: Mushrooms Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com