

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Transglutaminase Market to Grow at 7.4% CAGR Through 2032 — PW Consulting Insights
By pmarketresearch, 2026-07-13
Transglutaminase Market — 2026 Strategic Preview
Executive trailer
As food systems accelerate toward higher-efficiency protein utilization and diversified product formats, transglutaminase (TG) has emerged from a niche enzymatic tool into a strategic ingredient across meat, dairy, bakery and plant-based applications. PW Consulting’s latest study—anchored on a 2025 base year and projecting through 2032—quantifies this shift and translates it into practical decision support for commercial leaders in 2026. The global market, which registered meaningful expansion through the early 2020s, is forecast to continue growing at a compound annual growth rate (CAGR) of 7.4% over the 2026–2032 horizon, unlocking a materially larger addressable market by the end of the forecast period.
Transglutaminase Market
Why 2026 is a turning point
-
Regulatory momentum: Recent regulatory developments in major markets during 2026 have broadened permissible TG use cases and clarified safety pathways, materially changing market access calculus for manufacturers and ingredient suppliers.
Transglutaminase Market -
Commercial convergence: Food processors are converging product engineering, labeling strategy and cost-to-serve optimization—placing TG at the intersection of formulation efficiency and sensory fidelity for both animal- and plant-based proteins.
Transglutaminase Market -
Competitive reshaping: The supplier landscape shows a moderate level of concentration, leaving room for both scale players and specialized entrants to compete on formulation support, regulatory competence and channel partnerships.
Macro snapshot (concise, decision-focused)
Using 2025 as the analytical base year, PW Consulting’s topline indicates a market that has grown consistently since 2020 and is projected to expand materially over 2026–2032 at a 7.4% CAGR. By 2032, the market is expected to be significantly larger than it is in 2025—an outcome driven by broader application approvals, deeper penetration into plant-based and processed-protein categories, and adoption by mid-sized processors seeking yield and texture advantages. For executives evaluating 12–36 month initiatives, this macro trajectory reframes TG from a specialty cost driver into a strategic ingredient class with scalable ROI potential.
What the full study delivers (practical content)
-
Proprietary demand model and scenario suite: a base case plus alternative uptake scenarios calibrated to regulatory outcomes, protein price volatility and plant-based adoption curves—designed for sensitivity testing against your P&L levers.
-
Commercial playbooks: go-to-market blueprints for ingredient suppliers, co-manufacturers and food processors that include product positioning, sample dosing regimes, pilot protocols and win-loss templates for enterprise negotiations.
-
Regulatory and safety timeline: cross-jurisdiction mapping of approvals, dossiers and likely friction points—equipped with templated evidence packages to accelerate submissions and limit rework.
-
Supply chain risk matrix: supplier concentration analysis, production footprint mapping, alternative sourcing scenarios and logistical stress tests tailored to the enzyme manufacturing workflow.
-
Commercially actionable competitor intelligence: validated supplier profiles, partnership archetypes, pricing posture indicators and acquisition target diagnostics.
-
Implementation KPIs and sample financial models: investment case templates (capex, incremental margin uplift, payback timelines) for plant trials, co-development agreements and distribution expansion.
Competitive dynamics — what matters in 2026
The market structure is neither a monopoly nor a fully atomized commodity space. Three- and five-firm concentration metrics indicate a marketplace where leading suppliers hold meaningful share but do not fully exclude niche innovators. In practice, this creates a dual-track competitive environment:
-
Scale players can leverage brand recognition, global sales networks and long-standing customer relationships to secure large processor contracts and co-development deals.
-
Specialist firms can win on formulation breadth, regulatory dossiers for specific jurisdictions, certifications (e.g., Halal/Kosher) and tailored solutions for emerging segments such as meat analogs and vegan cheeses.
Profiles and strategic implications — select suppliers
-
Ajinomoto Co., Inc. — A global leader with the Activa® microbial TG offering. For processors targeting premium texture and international distribution, partnering with Ajinomoto provides a low-friction route to validated formulations and supply continuity. Strategic move: negotiate multi-market framework agreements with stepwise SKU rollouts and co-branded pilot programs.
-
Nanning Pangbo Biological Engineering — A large-scale Chinese producer with a strong position in food-grade microbial TG. For buyers seeking cost-competitive volume supply, Pangbo is a credible source; however, purchasers should combine volume contracts with quality audits and dual-sourcing to mitigate geographic concentration risk.
-
BDF Natural Ingredients, S.L. — A European supplier actively pursuing regulatory clearance in the EU. BDF’s dossier submission signals a near-term opportunity for European processors to integrate locally-sourced TG under a compliance umbrella. Strategic move: European processors should engage early on joint safety studies and co-marketing to accelerate acceptance.
-
Kinry Biotech (Jinan) — Offers a product line with recognized certification credentials, including Halal as of early 2026. This is an important differentiator for exporters to key export markets and for processors targeting niche religious or cultural segments.
-
Yiming Biotechnology, Taixing Dongsheng, Micro-Tech and Caldic — These companies illustrate the diversity of provider archetypes: regional specialists, product-line innovators for bakery and analogs, and specialty distributors who combine formulation services with enzyme supply. Commercial strategies should evaluate whether capability is best accessed via direct supply, licensing or white-label partnerships.
Regulatory tailwinds and watchpoints
-
Regulatory expansions in 2026 have broadened permissible TG uses in several jurisdictions, enabling product developers to explore applications previously constrained by labeling or permitted-use rules. That said, specific dossier approvals (and the timing thereof) will materially affect regional rollout sequencing; careful regulatory sequencing is now a competitive lever.
-
Authorities’ positive signals (including no-questions responses and dossier submissions in major markets) de-risk investments in formulation and scale-up—but they do not eliminate reputational risk. Consumer-facing communications strategy must be coordinated with regulatory filings to prevent headline-driven setbacks.
Practical, prioritized actions for 2026 decision-makers
-
Integrate regulatory scenario testing into product-roadmap gate reviews. Treat dossier outcomes as binary inflection points that shift resource allocation between regions and SKUs.
-
Pursue staged pilot programs with both a global scale supplier and a specialist provider. This hedges supply risk while enabling comparative performance benchmarking in your specific formulations.
-
Execute a supply-chain due-diligence playbook: dual-source where feasible, validate GMP traceability, and model logistic shock scenarios at the enzyme supplier and co-manufacturing tiers.
-
Align marketing, regulatory and quality teams to prepare transparent product communication—educational materials, clear labeling options and supply-trace narratives that anticipate consumer and retail questions.
-
Assess M&A and partnership targets against three criteria: regulatory competence (dossiers and certifications), formulation IP (proprietary dosing/formats), and channel access to priority segments (e.g., plant-based meat analogs, halal markets).
Risk scenarios and mitigation
Key downside scenarios include regulatory reversals driven by new safety data, emergent consumer resistance ("meat glue" perception), and supply-chain disruption concentrated in a few production hubs. PW Consulting’s report delivers mitigation playbooks—ranging from staged supply diversification and contract structures that include capacity guarantees, to consumer-facing education campaigns co-funded with suppliers.
How to use the full PW Consulting study
Consider the report as an operational decision kit rather than a static forecast. Use the demand model to size pilot investments, the regulatory timeline to prioritize dossier spending, and the competitor playbooks to structure win-win supplier relationships. For commercial teams, the included pricing and margin templates can be adapted to build a business case for ingredient substitution, product premiumization or launch sequencing across channels.
Closing — the strategic value proposition
For executives making 2026 capital and commercial choices, TG is no longer a marginal ingredient—it is a lever for yield improvement, product differentiation and supply efficiency. The market’s multi-year growth at a robust mid-single-digit-plus CAGR, combined with evolving regulatory acceptance and a market structure that rewards both scale and specialization, creates a compelling environment for targeted investment. PW Consulting’s full Transglutaminase Market study equips you with the models, regulatory roadmaps and commercial playbooks required to convert that growth into measurable business outcomes—while intentionally withholding the granular subsegment tables that determine precise tactical moves. Access to those datasets empowers the next level of execution planning.
For detailed analysis of this topic, please visit the official page: Transglutaminase Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cutting Tools Market — USD 25.78B in 2025, poised for 6.4% CAGR to 2032
By pmarketresearch, 2026-07-13
Cutting Tools Market: Strategic Briefing for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present a focused, actionable orientation to our new Cutting Tools Market study. This briefing translates the study’s macro vantage into immediate implications for executives preparing strategy and capital allocation decisions in 2026. It demonstrates the report’s analytical depth while preserving the proprietary, granular segment intelligence that drives operational decisions — the exact segment-level allocations and unit economics are reserved for the full report and supporting datasets.
Cutting Tools Market
Sizing and trajectory: where the market stands
The cutting tools market has moved from a cyclical recovery in the early 2020s into a structurally expanding industry. Our study benchmarks the market at USD 25.78 Billion in 2025 (base year) and documents steady growth from 2020. Looking forward, the market is expected to expand at a compound annual growth rate (CAGR) of 6.4% through our forecast horizon (2026–2032), with total revenues approaching USD 40 Billion by 2032. That trajectory reflects both secular demand drivers — industrial automation, electrification of automotive powertrains, and continued capital renewal in precision-machining sectors — and transient rebounds in end-market activity.
Cutting Tools Market
Why this research matters for 2026 decisions
- Capital allocation: Accurate, consensus-calibrated topline growth and scenario outputs let you prioritize CAPEX and R&D investments for a medium-growth environment rather than a high‑growth or recessionary one.
- Supply chain resilience: The report quantifies exposure to raw-material and trade-policy shocks, enabling supply‑chain reconfiguration and hedging strategies that protect gross margins under tariff volatility.
- Portfolio optimization: Actionable frameworks in the study allow firms to align product portfolios (materials, geometries, coatings) to the demand mix that will drive value through 2032.
- M&A and partnership screening: With market concentration metrics and competitive maps, the study supports quick-screening of bolt-on targets and strategic alliances for scale, capability or geographic reach.
Core market dynamics shaping strategy in 2026
- Raw-material pressure and input risk: Tungsten carbide — a core feedstock — has seen cost escalation. Higher raw-material prices compress margins and force choices between absorbing costs, raising prices, or accelerating material substitution and yield improvements. Tactical responses range from hedging and forward purchase agreements to invest-to-save in recycling and remanufacturing programs.
- Trade and regulatory friction: Recent policy actions — export controls and tariff enhancements on tungsten products and related inputs, along with ongoing investigations affecting industrial equipment imports — have materially increased geopolitical supply risk. These developments make dual‑sourcing, nearshoring, and tariff engineering non‑optional elements of procurement strategy through at least 2027.
- End‑market mix and product evolution: Demand remains driven by traditional anchors — automotive, general machinery, and aerospace/energy — but the technical mix is shifting toward higher‑value specialty geometries, coatings and multi‑material solutions (e.g., carbide+ceramics). Manufacturers and distributors able to fast-follow design wins with application‑specific toolsets capture disproportionate margin expansion.
- Aftermarket and services monetization: Tool lifecycle services — regrinding, coating refresh, digital monitoring of tool life — are emerging as predictable, higher-margin annuities. Our research demonstrates how service models improve customer retention and create premium pricing opportunities.
- Digital and manufacturing productivity: Digitalization (tool‑life analytics, adaptive machining, integration with CAM systems) is moving from novelty to operational requirement. Early adopters report measurable cycle‑time and scrap‑reduction gains that translate into stronger purchasing justification for premium-priced tools.
Recent industry signals: what to watch
- Demand pulse: US shipment data indicates a strong near‑term upswing in cutting‑tool demand; shipment releases for early 2026 show double‑digit year‑over‑year increases in certain months — a signal of resumed industrial capex in specific end markets.
- Catalog and breadth plays: Several suppliers expanded product breadth in early 2026, launching larger catalogues and extended product families — a clear move to increase wallet share with OEMs and distributors.
- Targeted product innovation: Major suppliers announced new grades and micro‑tools in Q1–Q2 2026, underscoring continued emphasis on higher‑precision, specialized tooling for micro‑machining and challenging materials.
Competitive landscape: concentration and strategic archetypes
The market exhibits moderate consolidation: the top three players capture a meaningful portion of global revenue, and the top five widen that share notably. That structure creates a mixed arena where global technology leaders coexist with nimble specialists and strong regional players. Key competitive archetypes found in our fieldwork include:
Cutting Tools Market
- Global system suppliers with integrated offering sets (advanced grades, tooling systems, and application engineering) — these firms compete on technology and OEM relationships.
- Specialists focused on niche geometries, remanufacturing, or miniaturized tooling — they defend margin through technical differentiation and service models.
- Distributors and hybrid manufacturers that scale through catalog breadth and logistics excellence.
Representative companies profiled in the study range across these archetypes: established multinational manufacturers active in advanced grades and tooling systems; specialized carbide and reamer makers with remanufacture capabilities; and catalog/distribution leaders that emphasize breadth and quick fulfillment. The report includes diagnostic profiles of each, analyzing capabilities, channel leverage, and M&A posture while preserving commercially sensitive details for subscribers.
What the full report delivers (operational, not just descriptive)
- Topline market sizing and a granular growth model covering 2020–2032, with scenario runs that isolate the impact of raw‑material shocks and tariff regimes.
- Segmentation by region, material/type and application — with implied unit economics, margin models and relative growth velocity (note: detailed segment allocations and unit prices are gated in the full dataset).
- Comprehensive supply‑chain map, from primary feedstocks to finished‑good distribution, with points of vulnerability and recommended mitigations.
- Competitive benchmarking for leading suppliers (technology, channel, IP and service capabilities) and a M&A and partnership playbook tailored to different buyer profiles.
- Actionable go‑to‑market playbooks for OEMs, distributors and captive toolrooms: pricing levers, service bundles, digital productization approaches and sample ROI cases.
- Regulatory and trade-impact assessment, including tariff sensitivity tables and recommended procurement hedges for 12‑month and 36‑month horizons.
Strategic imperatives for 2026 (what leaders are doing now)
- Adopt a tiered sourcing strategy: combine secured long‑term contracts for critical carbides with strategic inventory buffers and vetted secondary suppliers outside single‑source jurisdictions.
- Invest in remanufacturing and recycling: recycle tungsten‑bearing scrap to reduce exposure to market price swings and create a defensive cost advantage.
- Prioritize product‑led differentiation: accelerate launches of geometry‑specific toolsets and coatings that are proven to reduce cycle time or extend tool life — these justify premium pricing and deepen OEM relationships.
- Monetize aftermarket and services: build subscription or outcome‑based contracts (e.g., cost per hole, availability‑backed services) to stabilize revenue and improve customer stickiness.
- Scenario‑test tariffs and export controls: operationalize contingency plans that include nearshoring, tariff pass‑through mechanisms, and hybrid production footprints.
- Leverage digital tooling: couple tool telemetry with CAM integration to deliver measurable productivity improvements to customers and create commercialization hooks for premium tools.
- Use M&A selectively to fill capability gaps: prioritize targets that deliver immediate margin expansion (service platforms, remanufacturers) or accelerated access to strategic end markets.
Scenario planning and next steps
2026 is a year of choices: the market’s mid‑single‑digit CAGR provides stable growth, but rising input costs and geopolitical trade measures make execution risk asymmetric. Leading firms will tilt their portfolios toward higher‑value offerings, lock in more resilient supply chains, and convert product innovation into recurring service revenues. They will also run robust scenario analysis — which our study supplies — to quantify how a shock (e.g., extended export controls or a multi‑year raw‑material spike) affects demand, margin and capital needs across business lines.
PW Consulting’s Cutting Tools Market report is designed for executives who need both the strategic frame and the hands‑on playbooks to act now. The full report and dataset provide the gated segment economics, provider scorecards, and interactive scenario models that are indispensable for detailed action planning. For the granular segment allocations, supplier scorecards, and downloadable scenario models referenced here, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Cutting Tools Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Water Leak Detection Market to Reach USD 279M by 2032 at 6.52% CAGR
By pmarketresearch, 2026-07-13
Strategic Preview: Water Leak Detection Systems Market — Why 2026 Is a Decision Year
As PW Consulting’s senior strategic advisor and industry analyst, I present a forward-looking synthesis of the Water Leak Detection Systems market designed to orient executive decisions in 2026. This piece highlights the market’s trajectory, the regulatory and technology dynamics reshaping buying behavior, and the competitive moves that will matter for procurement, product strategy, and M&A. It deliberately previews analytic depth while withholding granular segment tables and regional/application breakouts to preserve the “trailer” experience — the full intelligence, models, and vendor scorecards are available in the source report.
Water Leak Detection Systems Market
High‑level market trajectory: a dynamic growth story
The water leak detection market has evolved from a niche mitigation product to a strategic operational technology. Between 2020 and the 2025 base year, the market expanded materially from the low hundreds to a stronger base — reflecting growing adoption across built environments, utilities, and critical infrastructure. PW Consulting’s forecasting model projects the market continuing to grow at a compound annual growth rate of approximately 6.52% across the next phase, positioning the industry on a sustained growth path through the 2026–2032 forecast horizon. By 2026 the market steps into a new scale, and our 2032 outlook shows the technology ecosystem maturing further as integrated hardware, software and services converge.
Water Leak Detection Systems Market
Why 2026 matters for executives
- Regulatory inflection points are compressing timelines. Mandates and standards—ranging from EU water-management directives to national utility leakage requirements—are converting optional protection spend into structured procurement. Organizations that align procurement, compliance, and asset-management strategies in 2026 will avoid retroactive capex and elevated remediation costs.
- Cost of failure becomes quantifiable. New guidelines and energy/water accounting rules mean that the hidden costs of undetected leaks (lost product, energy to treat and pump water, equipment damage and downtime) are increasingly recognised in corporate P&L and capital planning. Decision-makers who can map detection ROI to these avoided costs gain clear budget priority.
- Technology convergence creates strategic choices. Flow‑based systems, sensor cable networks, acoustic technologies and satellite/AI analytics are converging into multi‑layered detection stacks. 2026 is the year when pilots must either be scaled or shelved—delaying action risks vendor lock‑in or falling behind in interoperability and data standards.
- Service-led offerings reduce total lifetime cost. Vendors are packaging hardware with cloud analytics, automatic shut‑off, and managed monitoring. Buyers must decide whether to buy products, managed services, or hybrid contracts; the wrong model can shift risk and inflate operating cost.
Regulatory and macro drivers shaping procurement
Regulatory pressure is a principal accelerant. Europe’s water management framework and national building‑management standards are pushing institutional buyers toward defined technical specifications and verifiable monitoring regimes. In parallel, utility regulators in various jurisdictions are mandating leakage reduction targets and incentivising investments in pipeline‑level detection. In the United States, federal infrastructure assessments and guidance have elevated the economic case for proactive detection, quantifying treated water losses and their operational impact.
Water Leak Detection Systems Market
These mandates change procurement from a cost‑avoidance exercise to a compliance and resilience programme—affecting vendor selection criteria, metrics for success, and allowable funding sources. Organizations that integrate compliance requirements into their 2026 rollout plans gain both budgetary clarity and competitive advantage in capital allocation.
Technology and deployment dynamics
- Layered detection architectures win. Single‑technology approaches (acoustic only, or flow only) are giving way to layered systems that combine continuous flow analytics, zone addressable sensing, acoustic pinpointing, and remote satellite or aerial leak detection. The combined stack lowers false positives and improves time‑to‑isolation.
- Data and integration are the new battleground. The value of any detection system is amplified by analytics, alert orchestration, and integration with facility management and SCADA systems. Vendors offering open APIs, pre‑built integrations, and strong data governance will command premium positions.
- Service models and managed detection. Expect rising adoption of 24/7 monitoring subscriptions, SLA‑backed response contracts, and outcome‑based commercial models that tie fees to leakage reduction outcomes or response times.
- Labor arbitrage and automation. The high cost of manual inspection—particularly in commercial and industrial facilities—drives demand for automated detection and automatic shutoff, lowering downtime and insurance exposures.
Competitive landscape — who to watch
The market remains moderately fragmented with leading firms capturing a non‑dominant share; the top three firms together account for roughly a quarter of the market and the top five capture around a third. That concentration profile creates fertile ground for differentiation through product depth, service capabilities and channel partnerships.
- Aqualeak Detection Ltd (UK) has positioned itself as a vertically integrated manufacturer offering flow, sensor and distance measuring systems. Recent product launches include connected automatic shutoff devices and multi‑zone addressable EMS systems that speak directly to facility automation teams.
- The Detection Group, Inc specialises in FM‑approved wireless systems with continuous monitoring—focusing on commercial and industrial portfolios where 24/7 uptime is critical.
- Dorlen Products Inc has scale in sensor cable deployments and an installed base spanning many thousands of sites—a strong footing for upselling analytics and managed services.
- FloLogic, MultiTech, HW group, TTK, Megger/SebaKMT, Grove and Badger Meter represent complementary strengths across flow analytics, LoRaWAN connectivity, cable‑based sensing, acoustic leak detection for utilities, IoT sensors, and integrated utility platforms. Each brings differentiated IP that is increasingly being combined in multi‑vendor solutions.
Recent industry activity validates the trends above: in late 2025 and early 2026 several vendors showcased deeper integration and productisation—exhibitions and product launches from major suppliers demonstrated a push to tie detection hardware to SaaS analytics and automatic remediation. Collaborations using AI and satellite analytics have started to surface measurable utility wins, demonstrating that remote sensing can materially reduce leak incidence when integrated into broader detection programmes.
What the PW Consulting report delivers (practical, actionable content)
Our full market study is designed for procurement leads, CTOs, facility managers, utility program directors and corporate strategists. It is intentionally operational and includes:
- Proprietary market sizing and a seven‑year forecast model (historical 2020–2025 baseline; base year 2025), with scenario runs for conservative, base, and accelerated adoption pathways.
- Vendor scorecards and capability heatmaps that evaluate product breadth, service delivery, data integration, and implementation risk.
- Implementation playbooks for three buyer archetypes—utilities, commercial real estate/facilities, and industrial process operators—covering procurement templates, pilot design, KPIs, and O&M governance.
- Technology roadmaps that map sensing modalities (flow, acoustic, cable, satellite/AI), expected unit‑cost trends, and interoperability requirements through 2032.
- Pricing and commercial model guidance, including TCO calculators and contract clauses for outcome‑based or managed services engagements.
- Regulatory impact analysis and compliance checklists tailored to major jurisdictions and standards bodies.
- Strategic M&A and partnership playbooks identifying where scale, data, or channel partnerships can accelerate market entry.
To preserve our clients’ competitive advantage, the report omits some public-facing segment tables from this preview; those detailed splits and company‑level revenue estimates are available within the subscription content.
Strategic implications and recommended actions for 2026
- Prioritise staged deployments tied to compliance. Align pilots with regulatory milestones. Successful 2026 pilots should be designed to validate both operational KPIs (leak detection time, false positive rates) and financial KPIs (avoided loss and mitigation cost).
- Adopt an integration-first procurement spec. Specify open APIs, data export standards, and SCADA/CMMS integration requirements up front to avoid costly rip‑and‑replace cycles.
- Buy outcomes, not only devices. For critical facilities, prioritise vendors or partners that offer outcome guarantees or SLA‑backed monitoring. This shifts risk and aligns incentives for rapid remediation.
- Evaluate hybrid sourcing. Combine best‑of‑breed sensors with centralised analytics and local service partners to balance innovation and reliability.
- Plan for scale with data governance. Define data retention, sharing and privacy policies before deployment so that analytics can be safely monetised or shared across asset portfolios.
Final perspective — what leadership must decide in 2026
Water leak detection is no longer a defensive line item; it is an operational risk play with measurable financial upside. The choices executives make in 2026—about how to integrate detection into asset management, whether to buy outcomes vs. capital assets, and which technology layers to prioritise—will determine cost of ownership and resilience over the next decade. The market’s steady CAGR and the demonstrable wins from recent vendor deployments make the economics compelling. The remaining strategic questions are primarily organizational and contractual.
PW Consulting’s full report equips decision‑makers with the models, vendor intelligence, procurement templates, and implementation playbooks needed to act confidently in 2026. For those ready to convert pilot momentum into enterprise‑scale programmes, the report provides the step‑by‑step guidance and vendor analysis required to de‑risk rollouts and capture measurable returns.
Next step
Access the complete study for the detailed segmentation, the vendor scorecards, and the downloadable forecasting model that underpins our recommendations. The full report contains the granular tables and scenario models that organisations need to finalise 2026 budgets and procurement strategies.
For detailed analysis of this topic, please visit the official page: Water Leak Detection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Indium Market 2026: Strategic Preview for Decision-Makers
Executive teaser
As strategic advisors to senior management teams in materials, electronics, and semiconductor ecosystems, PW Consulting presents this executive preview of our Indium Market study. The research distills years of primary and secondary intelligence—policy scans, price modeling, producer interviews, and demand scenarios—into actionable guidance for decisions that will shape 2026 sourcing, investment and vertical-integration strategies.
Indium Market
Why this matters in 2026
Indium sits at the intersection of electronics materials, photonics substrates, and specialty alloys. After a measured recovery through the early 2020s, the market expanded from an estimated USD 162.3 Million in 2020 to USD 200.0 Million in our 2025 base year, and our bottom-up models project growth to roughly USD 308.8 Million by 2032. That trajectory implies a compounded annual growth rate of 6.5% over the 2026–2032 forecast window—sufficient to change investment appetites across supply chain tiers.
Indium Market
For 2026 corporate planning, this means firms must move beyond short-term spot market reactions and adopt multi-dimensional strategies: secure diversified feedstock, protect supply through contractual levers, invest in alternative materials or recycling capacity, and prepare for regulatory shocks that can rapidly alter regional sourcing economics.
Indium Market
What the full PW Consulting study delivers (practical scope)
- Market sizing and trend calibration: rigorous historical reconciliation (2020–2025) and probabilistic forecasting (2026–2032) with scenario ranges tied to demand drivers and price elasticity assumptions.
- Supply-side analysis: asset-level mapping of primary production, smelter byproducts, and secondary (recycled) capacity, plus near-term expansion and closure risks.
- Demand decomposition framework: end-use drivers, substitution risks, and sensitivity matrices that translate unit demand into dollar exposure under alternative technology scenarios.
- Price formation and cost curve modeling: warehouse price scenarios, input-cost pass-through, and inventory-to-consumption ratio thresholds that historically precipitate price spikes.
- Regulatory and trade-impact playbook: quantified scenarios for tariffs, export controls, and licensing requirements—together with mitigation tactics and contingency contracting language.
- Competitive intelligence and transaction-ready output: supplier scorecards, M&A target shortlist, and integration checklists for buyers evaluating downstream moves (manufacturing, recycling, or wafer fabs).
- Operational tools: procurement negotiation templates, hedging decision trees, and a risk-heatmap dashboard tailored for supply chain and corporate development teams.
Market outlook—what the numbers mean for strategy
The market’s increase from the early-2020s base into 2025 demonstrates both demand resilience and the impact of supply-side concentration. Our modeled path to roughly USD 309 Million by 2032 is driven by continued consumption in established electrically conductive coatings and by accelerating new demand pockets in photonics substrates and advanced packaging. A steady 6.5% CAGR is large enough to incentivize upstream capital allocation but small enough that entrants will require differentiated capabilities—cost, reliability, or recycling—to displace incumbent supply.
Because the market is moderately concentrated, strategic moves by a small set of producers or refiners have outsized effects on pricing and availability. Our market concentration metrics indicate a dominant top-three share and a substantial top-five share, underscoring why supply diversification and long-term offtakes are core elements of a robust sourcing strategy.
Supply-demand dynamics and risk flashpoints
- Geopolitical and trade policy: Recent policy actions—such as the 25% ad valorem tariff on specified critical minerals announced by the U.S. and new export licensing requirements introduced by a major producing country—have materially increased trade friction and upstream risk premia. These are modeled in our baseline and downside scenarios.
- Price volatility: Warehouse prices for refined product showed abrupt movement in 2024, with estimated average prices increasing materially year-on-year; our scenario work illustrates price thresholds where downstream buyers typically accelerate substitution and recycling initiatives.
- End-use concentration: Indium tin oxide (ITO) coatings continue to be the largest single consumption application globally. Changes in display technology roadmaps, notably shifts between LCD and emissive display platforms or adoption of oxide conductors, are built into our demand sensitivity runs.
- Recycling and secondary supply: Secondary recovery remains a strategic lever to smooth supply shocks. Our operational playbook details the breakeven horizon for investments in recovery versus long-term contracted purchases.
Competitive landscape—who to watch
We profile manufacturers, refiners, recyclers, and advanced materials players that collectively shape availability, technology direction, and pricing dynamics. Key participants covered include:
- Indium Corporation (Clinton, New York, United States) — A premier manufacturer and supplier focused on high‑purity indium metals, compounds, alloys, solders and thermal interface solutions for electronics, semiconductor and photonics markets. Recent strategic R&D collaborations and product innovations underscore its role in shaping U.S. supply options.
- Umicore (Brussels, Belgium) — An advanced materials and recycling leader with capabilities in indium refining and circular supply solutions for electronics and telecommunications. Their public disclosures emphasize positioning in semiconductor materials supply chains.
- Teck Resources Limited (Vancouver, Canada) — A primary producer sourcing indium as a byproduct of base-metal operations; operational decisions at primary mines materially affect upstream throughput.
- Dowa Holdings Co., Ltd. (Tokyo, Japan) — A vertically integrated producer and recycler supplying both primary and secondary feedstock to high-tech markets.
- Korea Zinc Co., Ltd. (Seoul, South Korea) — A major smelter with high‑purity product streams serving display and semiconductor markets.
- Nyrstar (Brussels, Belgium) — A zinc and lead producer with byproduct indium recovery and refining operations that can flex regional supply balances.
- PPM Pure Metals GmbH (Ganderkesee, Germany) — A specialist supplier of high‑purity indium and alloys targeting semiconductor and research applications.
- AXT Inc. (Fremont, California, United States) — A manufacturer of indium phosphide (InP) substrates and wafers for telecom and photonics; noteworthy as photonics wafer capacity expansions reshape substrate demand.
Recent developments we track include strategic R&D alliances, product awards, and infrastructure investments that increase regional production or processing density. Examples include partnerships to expand critical metals production capacity, industry awards that validate supplier sustainability performance, and the construction of industrial-scale photonic wafer fabs—each of which has supply, margin and technology implications.
Strategic implications and recommended plays for 2026
- Procurement: Move from spot-only purchasing to blended strategies combining multi-year offtakes, conditional call options, and local buffer inventories sized by our inventory sensitivity models.
- Supply diversification: Prioritize secondary-sourcing pathways and certified refiners with transparent traceability to mitigate export-control and tariff shocks.
- Vertical options: Evaluate selective downstream integration or minority equity in recyclers and substrate fabs where long-term demand linkage or technology ownership provides competitive advantage.
- Substitution and product design: Fund R&D pilots to qualify indium-reducing or indium-free material systems for non-core product lines, with trigger points set by our price-implementation matrix.
- Regulatory readiness: Establish a trade-policy watch and rapid-response playbook, including contract language and insurance instruments, to address tariff escalations or licensing restrictions.
How to use this preview—and what’s withheld
This preview is designed as a decision-grade orientation, not a replacement for the full dossier. To preserve commercial value and encourage direct examination of the source analysis, granular segmentation tables (regional and application-level breakdowns), detailed supplier market shares, and transaction-ready financial models are intentionally withheld from this summary. These elements are included in the full PW Consulting Indium Market report, which contains downloadable spreadsheets, scenario toggles, and supplier due-diligence appendices.
Next steps for executives
- Book a brief with PW Consulting’s Indium practice to receive a tailored briefing that maps our scenarios to your product portfolio and procurement exposures.
- Request the scenario workbook to run your own sensitivity tests on pricing, inventory and substitution timelines.
- Engage our M&A and supply assurance teams if considering upstream investments, strategic partnerships with recyclers, or offtake negotiations with key refiners.
Closing perspective
By 2026, indium will no longer be a niche raw material issue discussed only by commodity teams; it will be a cross-functional strategic variable that affects manufacturing timelines, product roadmaps and capital allocation. Our study equips leaders to translate the market’s projected expansion—from a 2025 base into a robust 2032 outlook at a projected 6.5% CAGR—into defensible, executable plans. For organizations that move early—securing diversified supply, investing in circularity, and operationalizing policy-readiness—the market growth ahead represents a durable competitive opportunity. For those that delay, the combination of trade friction, concentrated production and price volatility will raise the cost of doing business.
To obtain the full report, datasets, and scenario workbooks, visit the PW Consulting Indium Market report page or contact our Indium practice lead for a confidential briefing.
For detailed analysis of this topic, please visit the official page: Indium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Arsenic Removal Market to Expand at 6.5% CAGR Through 2032
By pmarketresearch, 2026-07-13
Arsenic Removal Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s senior industry analysts, we present a high-level strategic primer on the Arsenic Removal Market ahead of our full 2026 study release. This introduction lays out the market’s trajectory, the competitive contours, and the practical decision levers that executives should be weighing now. Numbers cited below are macro-level only; detailed regional, application and vendor-level splits are intentionally reserved for the full report to preserve the “trailer” character of this brief and to guide decision-makers to the complete intelligence package.
Arsenic Removal Market
Market arc and headline metrics
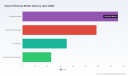
The market for arsenic removal technologies has shown steady expansion through the early 2020s and enters 2026 from a position of durable growth. Using 2025 as the base year, our topline model indicates a market measured in the low-hundreds (USD, million) that expands at a compound annual growth rate (CAGR) of approximately 6.5% over the forecast window to 2032. That growth reflects the intersection of regulatory persistence, incremental infrastructure investment, and technology-driven replacement cycles.
Arsenic Removal Market
For executives this means two important takeaways: first, the market is large and expanding fast enough to justify dedicated commercial focus, but second, it is not a rapid one-off boom — it rewards optimized product lifecycles, service models and financing pathways that capture recurring revenue over many years.
Arsenic Removal Market
Drivers and headwinds that will shape 2026 choices
-
Regulatory constancy and compliance demand — The U.S. EPA’s maintenance of the arsenic MCL (10 µg/L) continues to anchor municipal and community-level investment in treatment upgrades. Many public systems are identified in regulatory reviews as requiring system refreshes or technology changes to sustain compliance rather than one-time remediation.
-
Small-system affordability and financing dynamics — Financing programs targeted at small community systems remain an essential enabler of demand. Access to low-cost capital and grant/loan programs materially affects procurement cycles and the selection of technologies with predictable lifecycle costs.
-
Operational cost pressure and lifecycle externalities — The lifecycle cost of arsenic removal solutions is amplified by hazardous-waste classification of spent media and sludges, and by regional shortages of trained operators. These factors increase both O&M burdens and the total cost of ownership (TCO) over asset life.
-
Sectoral demand pockets — Beyond municipal drinking water, targeted industrial users (for example, food & beverage and specialty agriculture) are emerging as meaningful pockets of demand where high-value, performance-guaranteed systems are prioritized over lowest upfront cost.
-
Technology substitution and hybridization — Established approaches (adsorption, ion exchange, membranes, oxidation/coagulation) are being recombined and optimized to address local water chemistry, waste-handling constraints and footprint limits. Effective differentiation increasingly depends on service packaging and waste-minimization credentials, not technology novelty alone.
Structural implications for supplier economics
The combination of regulatory-driven base demand and pronounced operational externalities creates a supplier market where margin capture stems less from raw-media sales and more from bundled services: validation studies, guaranteed-performance contracts, media regeneration/logistics, and remote monitoring. Suppliers that can materially lower disposal costs or extend media life while assuring compliance will see disproportionate commercial returns.
In procurement conversations during 2026, buyer teams will privilege TCO models that explicitly quantify disposal and labor risk. At the same time, suppliers that can offer financing partnerships or align with public funding mechanisms will improve sales velocity into smaller systems where capital constraints otherwise delay upgrades.
Competitive landscape — who matters and why
The market landscape today is a mix of specialty media manufacturers, packaged-system integrators, engineering firms and consumer-focused vendors. Each cohort plays a different role in the commercialization chain:
-
Specialist media firms (e.g., companies deploying high-selectivity titanium-oxide or other proprietary adsorbents) focus on product performance and regeneration characteristics. Their commercial edge is in materials science, often supported by targeted field validation.
-
Process integrators and EPCs bring packaged, site-ready systems that reduce installation complexity for municipalities and industry customers. Their value proposition is speed-to-compliance and single-point accountability for performance guarantees.
-
Residential and commercial POU/POE brands compete on certification, ease-of-use and channel reach. Certifications and recognized media brands remain central to adoption in household and small-business contexts.
-
Bioprocess and precipitation specialists are relevant where wastewater and groundwater projects demand robust heavy-metal co-removal strategies and where sludge management can be integrated into existing treatment trains.
Key vendors profiled in our study (representing these competing archetypes) include technology-focused media manufacturers, packaged-system suppliers and consumer brands. Each has a distinct go-to-market logic: media innovators demonstrate technical differentiation and case studies; engineering firms translate that into municipal scale; consumer brands convert certification into retail and installer demand. Recent field activity—such as a series of high-profile installations in specialty agricultural regions and exhibition activity at major trade shows—underscores active pipeline development and field validation as a commercial accelerant.
Strategic playbook for 2026
For C-suite and business-unit leaders, the following strategic moves should be considered as part of 2026 planning cycles:
-
Buyers (municipal & industrial): Insist on total cost of ownership proposals that quantify waste disposal, operator training and lifecycle replacement. Structure procurement to include performance-based milestones tied to regulatory outcomes; retain contractual rights for independent verification.
-
Suppliers: Shift commercial emphasis from unit sales to lifecycle services. Develop media-regeneration or take-back programs to address hazardous-waste liabilities; bundle remote monitoring to mitigate labor shortages and provide predictive maintenance revenue.
-
Investors and M&A strategists: Look for tuck-in targets that add local service footprints or unique waste-management capabilities. The market rewards scale in servicing distributed, small-system clients and technology differentiation in minimizing secondary waste.
-
R&D and product leaders: Prioritize selectivity, regeneration potential and lower-sludge processes. Pilot hybrid solutions that combine oxidation pretreatment with high-selectivity adsorption to optimize media life and reduce downstream handling costs.
-
Procurement and finance teams: Coordinate with public financing programs and structure phased financing to align capital expenditures with observed compliance deadlines. Consider outcome-linked pay structures where allowable under procurement rules.
What the PW Consulting report delivers
The full PW Consulting Arsenic Removal Market study is designed as an operational playbook for 2026. Highlights include:
-
Topline market sizing (USD, million) with historical baseline (2020–2025), a clearly documented base year (2025), and a scenario-modeled forecast covering 2026–2032 using a 6.5% central CAGR—useful for medium-term capacity and investment planning.
-
Vendor scorecards and comparative technology matrices that evaluate performance, waste profile, install footprint, and service readiness across major solution categories.
-
Actionable procurement templates and TCO calculators that integrate disposal liabilities, labor availability risk and public financing levers so procurement teams can quickly compare proposals on an apples-to-apples basis.
-
Case studies and field validation dossiers, including recent real-world installations that illustrate technology selection under non-ideal chemistries and constrained budgets.
-
Regulatory mapping and compliance timelines that translate policy persistence into procurement urgency and capital planning timelines.
-
Risk matrices and mitigation playbooks—covering supply chain stress, raw-material variability, and hazardous waste handling—that finance and operations teams can use to stress-test initiatives prior to commitment.
Note: the public executive summary intentionally omits detailed regional and application-level splits, vendor revenue shares and certain granular cost tables. These are available in the full, licensed dataset and accompanying interactive dashboards.
Closing — what to act on in the next 90 days
For leaders preparing 2026 budgets and strategy cycles, the next quarter is the window to: finalize portfolio priorities (capex vs O&M-led offerings); initiate or accelerate pilots that validate low-waste, low-labor options in environments with constrained operator availability; and engage early with financing partners to align procurement timelines with compliance deadlines. The macro trajectory supports continued investment, but the highest ROI will accrue to organizations that internalize lifecycle externalities—especially waste management and operator dependency—into product design and commercial models.
PW Consulting’s full report delivers the datasets, scoring frameworks and procurement-ready tools to operationalize these recommendations. For access to the complete market breakdowns, vendor benchmarks and interactive TCO models, please visit our report page or contact our industry practice to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Arsenic Removal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Smart Gas Meter Market to Reach USD 344.8M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-13
Smart Gas Meter Market — Strategic Briefing for 2026 Decision-Makers
As utilities, meter manufacturers, technology vendors and investors enter 2026, the smart gas meter market is at a clear inflection point. Our PW Consulting Smart Gas Meter Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes market sizing, technology trajectories, regulatory drivers and vendor strategies into an action-oriented playbook. In short, this is the operating manual for executives who must convert regulatory pressure, decarbonization commitments and network modernization budgets into defensible procurement, product and investment decisions.
Smart Gas Meter Market
Market trajectory — what the topline numbers tell you
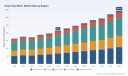
The market has shown steady growth through the early 2020s and accelerated into the mid-decade. Measured in USD (Million), the market increased from the low‑hundreds in 2020 to roughly USD 215 Million in the base year 2025 and is forecast to expand to the low‑hundreds by 2032. Our model applies a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 forecast period, reflecting combined effects of mandated metering accuracy, AMI/AMR rollouts, hydrogen-readiness requirements and continued adoption of low‑power wide area communications for remote readout and analytics.
Smart Gas Meter Market
Those topline dynamics matter because they shape three practical decisions for 2026: (1) the size and timing of procurement waves; (2) the acceptable payback period for advanced features (hydrogen‑compatibility, remote shut‑off, integrated MRV telemetry); and (3) where to concentrate proof‑of‑concepts versus full deployments. The report provides revenue and volume scenarios that convert the headline CAGR into discrete procurement buckets and multi‑year capex planning templates. (Note: our public summary intentionally omits granular segment tables and regional share percentages — full datasets and downloadable models are available on the report landing page.)
Smart Gas Meter Market
Why 2026 is a strategic inflection year
-
Regulatory tightening is compressing timelines. EU regulations on methane measurement and updated energy efficiency directives have already increased minimum accuracy and remote‑readability requirements, while several national authorities are accelerating compliance timelines.
-
Technology readiness has matured. Low‑power communications (LoRaWAN, NB‑IoT), improved ultrasonic sensing and more efficient battery systems have lowered the lifecycle cost of “true” smart gas meters versus legacy mechanical devices.
-
Decarbonization plans are shifting product specs. Hydrogen blending and pure hydrogen readiness are no longer future proofing — product roadmaps and certification pathways must be resolved before large capital deployments.
These forces create a near‑term premium for devices and systems that are demonstrably compliant, low‑lifecycle‑cost and upgradeable. Our study lays out not only the market demand curve, but the operational constraints (meter lifecycles, grid integration timelines, and audit/MRV windows) that make 2026 the last practicable year for many procurement decisions if utilities want to minimize retrofit costs during 2028–2032 upgrades.
Technology and regulatory dynamics to watch
-
Accuracy and MRV: EU Methane Regulation 2024/1787 and related MRV mandates require higher metering accuracy and traceable measurement records. Utilities and vendors will need to demonstrate both device precision and a secure data chain to satisfy audits.
-
Hydrogen compatibility: The industry is bifurcating into hydrogen‑ready meters and legacy designs. Hydrogen‑compatibility is not merely a sensor spec — it entails materials certification, recalibrated algorithms and updated validation regimes. Vendors are already launching multirange diaphragm and ultrasonic products to address this need.
-
Communications and battery life: Low‑power communication stacks and energy‑efficient radio modules are now a baseline requirement. Solutions that extend field battery life materially reduce total cost of ownership and are decisive in large, dispersed residential rollouts.
-
Interoperability & cybersecurity: With smart gas meters increasingly tied into AMI and utility OT networks, encryption, secure boot and interoperability with existing head‑end systems are procurement must‑haves.
Competitive landscape — who’s shaping the market
The market is commercially active and technologically diverse. Leading industrial and metering firms are deploying ultrasonic and advanced diaphragm designs, launching hydrogen‑tolerant platforms, and embedding edge intelligence and remote shut‑off capabilities. Notable vendor moves include:
-
Itron Inc. (United States) — Itron’s Intelis ultrasonic smart gas meters combine integrated shut‑off valves, edge intelligence and AMI compatibility. The company reported having surpassed three million shipments by May 2025, demonstrating strong operational scale in key utility accounts.
-
Honeywell International Inc. (United States) — Honeywell has announced a portfolio that includes ultrasonic residential meters with remote shut‑off and diaphragm variants designed for 100% hydrogen readiness; a multirange residential version was advanced in March 2025.
-
Landis+Gyr (Switzerland) — Landis+Gyr introduced the Surent™ G480 ultrasonic meter for North American utility modernization in February 2026 and secured a large‑scale deployment agreement with Origin Energy in June 2026, signaling aggressive expansion into utility upgrade projects.
-
Sensus / Xylem (United States) — Sensus‑branded next‑generation meters emphasize extended battery life through low‑power communications, with product launches in early 2025 that position them for large grid rollouts.
-
Zenner International (Germany) — Zenner has integrated over ten million sensors into global LoRaWAN networks (reported September 2025), showcasing scale in IoT connectivity and a service‑oriented approach to meter deployments.
-
Diehl Metering, Apator, RMG, Romet, SenseMi, Flonidan and other OEMs — These firms are focusing on analytics platforms, modular meter designs (LoRaWAN/NB‑IoT), and regional certification efforts to capture municipal and commercial business lines.
Collectively, the vendor landscape reflects a market that is technologically competitive but commercially fragmented: several capable vendors are pursuing differentiated go‑to‑market strategies rather than a single dominant incumbent. Our report maps vendor strengths and weaknesses across eight procurement dimensions — technology fit, certification readiness, AMI compatibility, TCO, service footprint, manufacturing capacity, cybersecurity, and upgradeability — so buyers can short‑list suppliers with objective, repeatable criteria.
What the PW Consulting report delivers — practical, decision‑ready outputs
-
Market sizing and scenarios: Topline and scenario models from 2020–2032 (base 2025), with downloadable revenue and unit forecasts by technology class and application tier.
-
Regulatory impact assessments: Regionally contextualized compliance timelines and a checklist for MRV and hydrogen certification readiness.
-
Procurement playbooks: RFx templates, evaluation scorecards, contract clauses for performance warranties, and a failure‑mode analysis to reduce retrofit risk.
-
CapEx / OpEx modelling: Payback calculators that fold in battery life, communication costs, installation and retrofit scenarios to estimate lifetime TCO under different deployment profiles.
-
Vendor dossiers and negotiation guides: Concise profiles of leading suppliers, recent product launches, and a negotiation framework keyed to supply chain constraints and warranty exposure.
-
Roadmaps and implementation templates: Pilot‑to‑scale roll‑out sequencing, data‑integration blueprints for AMI/MDMS, and a phased approach to hydrogen transition that minimizes stranded asset risk.
How executives should use this study in 2026
-
Utilities: Use the procurement playbook and compliance timelines to align meter selection with MRV auditing windows and to avoid costly mid‑life retrofits. Prioritize pilot programs for hydrogen‑readiness in mixed‑blend zones and lock in interoperability requirements in early RFx documents.
-
OEMs and component suppliers: Benchmark product roadmaps against our technology and certification matrices. Identify white‑space opportunities where buyers demand battery lifetimes, retrofitability or integrated safety (remote shut‑off) that are not met by incumbent offers.
-
Investors and project developers: Apply our scenario models to underwriting assumptions for deployment rates and warranty exposure. The growth profile and vendor fragmentation create acquisition opportunities in services, communications, and analytics enablers.
-
Systems integrators and software firms: Leverage the AMI/MDMS integration blueprints to accelerate time‑to‑value and package compelling OPEX‑based offerings for utilities seeking to outsource metering intelligence.
What we intentionally withhold — and where to find it
This introductory briefing demonstrates the depth and practical focus of the full PW Consulting Smart Gas Meter Market study, but it omits certain granular segmentation tables and discrete regional/application share percentages in order to preserve the full commercial value of the report. The comprehensive dataset — including detailed regional forecasts, unit‑level breakdowns by diaphragm, ultrasonic and other types, application splits (residential, commercial, industrial), and the full vendor market shares and concentration metrics — is available on the report landing page and via our secure data portal. For procurement teams, the downloadable RFx templates and TCO calculators require report access.
Closing — the immediate next steps for 2026
For organizations that must decide in 2026 whether to accelerate retrofit waves, standardize on hydrogen‑ready devices, or lock in multi‑year supplier agreements, the value of a tightly focused, data‑driven road map cannot be overstated. The PW Consulting study converts the market’s mid‑decade momentum and regulatory urgency into an executable plan: procurement windows, pilot sequencing, vendor short‑lists and the financial models needed to justify capital allocation.
To access the full dataset, scenario models and procurement assets referenced above, visit our Smart Gas Meter Market report page or contact the PW Consulting research team for a guided briefing and a tailored extract for your deployment geography and operating model.
For detailed analysis of this topic, please visit the official page: Smart Gas Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LVT Market Set to Hit USD 213.2M by 2032 at 3.55% CAGR
By pmarketresearch, 2026-07-13
Luxury Vinyl Tile (LVT) Market — Strategic Intelligence Briefing for 2026
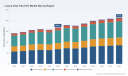
As companies plan capital allocation and product strategy for 2026, the Luxury Vinyl Tile (LVT) market sits at an inflection point where incremental growth, raw‑material shocks, and sustainability-driven regulation converge. Our proprietary market sizing places the global market at approximately USD 168.31 Million in the 2025 base year, with a steady compound annual growth rate of about 3.55% through the 2026–2032 forecast window. By 2032 the market is forecast to surpass USD 213 Million under the baseline scenario. These headline figures mask a more dynamic underlying picture — one that demands a calibrated mix of procurement discipline, product innovation, and regulatory foresight. This briefing explains why the full PW Consulting LVT Market study is essential for executives making strategic bets in 2026, and what decision‑ready outputs you will be able to act upon immediately.
Luxury Vinyl Tile (LVT) Market
Why this research matters in 2026
- Volatility in feedstock and its near‑term cost pass‑through. Recent sharp rises in PVC resin pricing — driven by oil price swings, ethylene supply constraints and geopolitically induced dislocations — materially increase manufacturing cost risk for LVT producers. Our analysis identifies which manufacturing and product archetypes are most exposed to resin price moves and where margin compression versus price pass‑through is most likely.
- Regulatory inflection points. The removal of certain export rebates and evolving chemical lists (notably upcoming LBC Red List revisions) are altering global supply economics and product formulation choices. These regulatory shifts accelerate demand for non‑PVC or hybrid formulations in specific channels and place compliance and certification at the center of go‑to‑market planning.
- Decarbonization and reputational dynamics. Leading suppliers are already quantifying emissions reductions — for example, a recognized global player reported a 27% reduction in Scope 1–3 emissions in 2025 en route to interim targets. Buyers and procurement teams will increasingly evaluate supplier supply‑chain traceability and lifecycle footprints as part of sourcing and specification decisions.
- Market structure: fragmentation with scale pockets. The competitive field remains fragmented — modest market concentration leaves room for regional champions, private label growth, and opportunistic consolidation. That structure influences pricing dynamics, supplier bargaining power, and the attractiveness of vertical integration or strategic JV arrangements.
Report deliverables — practical, transaction‑ready outputs
PW Consulting’s full report is structured to support immediate executive action rather than academic description. Key operational deliverables include:
Luxury Vinyl Tile (LVT) Market
- Transparent market‑sizing and forecasting methodology. A replicable top‑down and bottom‑up model covering historical 2020–2025 performance and scenario forecasts through 2032, allowing you to rebase assumptions to your cost, pricing and mix inputs.
- Scenario toolset. Three investable scenarios (baseline, raw‑material shock, regulatory acceleration) with elasticities for price, volume and margin by product architecture, enabling rapid stress tests for business plans and M&A targets.
- Supplier and capacity map. A verified map of manufacturing footprints, tiered supplier capabilities, and near‑term capacity expansions — designed for procurement to target sourcing diversification and for strategy teams to evaluate insourcing or greenfield opportunities.
- Channel and product playbooks. Actionable GTM tactics for core channels (commercial specification, residential retail, institutional procurement) including sample specification language to accelerate listing and reduce project approval cycles.
- Sustainability & compliance toolkit. A stepwise R&D and procurement pathway for reformulating toward low‑VOC, reduced‑PVC or hybrid constructions, aligned with certification timelines and likely Red List impacts.
- Pricing and hedging framework. Practical guidance for building index‑linked cost pass‑through clauses, resin hedging approaches, and margin protection strategies for both manufacturers and distributors.
- M&A and partnership screening matrix. A prioritized lens for targets based on capacity fit, product adjacency, geographic exposure and regulatory risk — designed for private equity and strategic buyers evaluating bolt‑on or consolidation plays.
Competitive landscape — how leading suppliers are positioning
The LVT supplier universe spans multinational flooring conglomerates, regional specialists, and high‑volume manufacturers. Our competitive analysis synthesizes strategic imperatives for the market’s most influential players and highlights where value creation is concentrated:
Luxury Vinyl Tile (LVT) Market
- Mohawk Industries (Dalton, Georgia) — Emphasizing premium LVT and rigid‑core ranges, Mohawk’s collections focus on high‑value aesthetics and differentiated textures. Their product cadence targets premium retail and specification channels where brand and design command price premiums.
- Shaw Industries Group (Dalton, Georgia) — With resilient SPC and LVT portfolios under identifiable brands, Shaw concentrates on integrated supply‑chain advantages and broad distribution networks, particularly in North American retail and commercial channels.
- Tarkett (Marseille, France) — Notable for accelerating non‑PVC innovations and hybrid offerings, Tarkett’s recent ReNue hybrid product expansion illustrates how incumbents are hedging regulatory and raw‑material risk through material diversification.
- Karndean Designflooring (Lichfield, UK) — A design‑led specialist with a strong emphasis on waterproof and durable aesthetics, Karndean’s activity underscores the ongoing premiumization of residential and boutique commercial segments.
- Interface, Inc. (Atlanta, Georgia) — Focused on high‑performance commercial LVT formats, Interface leverages specification relationships and sustainability credentials to defend margin in institutional procurement.
- Gerflor, Forbo, COREtec and regional leaders — These vendors concentrate on differentiated surface treatments, low‑VOC and compliance‑driven product families, and are increasingly visible in Europe and specialized commercial projects.
- Large Chinese manufacturers and OEMs — A cohort of high‑volume producers continues to supply realistic wood and stone visuals at scale. Their strategic moves into foreign markets, vertical integration and price leadership materially shape global supply dynamics.
Collectively, the market shows limited top‑end concentration: the top three and top five shares indicate a fragmented landscape with space for differentiated brands and low‑cost scale players alike. That structure shapes competitive tactics — from specification capture and design innovation to aggressive channel expansion and selective vertical integration.
Risk scenarios and sensitivity levers we model
- Raw‑material shock. We model the P&L pass‑through for sudden PVC resin price spikes (the industry has already experienced outsized moves linked to Middle East conflicts and supply constraints). The report identifies product formats and geographies where hedging or formula change achieves the fastest margin stabilization.
- Regulatory acceleration. With anticipated LBC Red List updates and changing export tax regimes, we stress‑test reformulation timelines and certification bottlenecks, quantifying time‑to‑market impacts for non‑PVC alternatives.
- Demand reallocation. We consider scenarios where commercial specification demand weakens versus residential premiumization, showing where SKU rationalization and channel re‑focus yield the fastest ROI.
How executives and investors should use this intelligence in 2026
- Procurement & supply‑chain teams: Rebalance supplier portfolios now — diversify resin sourcing, establish conditional contracts with escalation triggers, and onshore critical SKUs to reduce geopolitical exposure.
- Product and R&D leaders: Prioritize hybrid and low‑PVC formulations for channels where regulation and customer demand converge; invest in production modularity to switch face layers and cores with minimal downtime.
- Commercial and specification teams: Use the report’s channel playbooks to shorten approval cycles in healthcare, education and corporate interiors; emphasize third‑party certifications and lifecycle impact data in bids.
- Corporate development & PE: Target acquisitions that add capacity in resilient geographic nodes, or that provide proprietary surface treatments and non‑PVC chemistry — both high ROI levers in a tightening regulatory landscape.
- Boards & CFOs: Ensure scenario‑based stress tests inform capital allocation — particularly for plant expansions where resin exposure and energy inputs are significant operating cost drivers.
What we intentionally hold back — and why
True to the “trailer” principle, this briefing demonstrates the depth and practical utility of our analysis while deliberately omitting granular segment and regional tables. The report contains those detailed split matrices, SKU‑level margin curves, and supplier scorecards necessary for negotiation and investment decisions. Those assets are provided within PW Consulting’s full subscription package and are designed to be operationalized directly into ERP, procurement and M&A diligence workflows.
Next steps — how to convert insight into advantage
- Secure the full market model and scenario workbook to run your internal sensitivities against our baseline forecasts.
- Request the supplier‑capability map and procurement playbook to begin a three‑month supplier diversification program.
- Engage PW Consulting for a rapid 8–12 week product portfolio and cost‑to‑serve optimisation sprint tied to the regulatory timelines most likely to affect your products.
In a market that is growing steadily at an identifiable compound rate but is simultaneously vulnerable to supply, regulatory and sustainability shocks, the difference between winning and lagging will be set by who moves first on procurement strategy, product reformulation and certification. Our full LVT Market Report provides the executable playbooks, verified supplier intelligence, and scenario tools you need to make those moves decisively in 2026.
— PW Consulting, Senior Strategic Advisory & Industry Analysis
For detailed analysis of this topic, please visit the official page: Luxury Vinyl Tile (LVT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Isobutene Market to Reach USD 44.1B by 2032 at 4.45% CAGR
By pmarketresearch, 2026-07-13
Isobutene Market Outlook 2026: Strategic Imperatives for Industrial Decision-Makers
Executive summary
The global isobutene market has moved from a stabilizing post‑pandemic recovery into a structurally different phase where feedstock dynamics, regulatory timelines and selective capacity investments will determine winners and losers. Our baseline analysis shows the market expanding from roughly USD 24.5 Billion in 2020 to an estimated USD 32.45 Billion in 2025, and continuing on a compound annual growth path (CAGR of approximately 4.45%) to reach the low‑mid‑USD 40 Billion range by the early 2030s. For senior executives planning through 2026, this report translates those headline trajectories into concrete decision levers — where to invest, when to secure feedstock, which value chains to prioritize, and how to structure partnerships to preserve margin and optionality.
Isobutene Market
Why 2026 is a strategic inflection point
Several near‑term factors converge in 2026 that make this the most operationally consequential planning horizon for companies exposed to isobutene: a recalibrated feedstock cost environment, regulatory compliance deadlines affecting industrial refrigeration and chemical processes, and a market that remains highly concentrated among a handful of global suppliers. Taken together, these create material implications for procurement strategies, capital deployment and product positioning.
Isobutene Market
- Macro growth with tactical volatility: The market’s multi‑year growth trajectory is robust enough to justify capacity investments in selected pockets, but short‑term pricing and inventory swings will test project economics and contract structures.
- Regulatory cliffs: U.S. regulatory transitions (notably programs linked to HFC/industrial refrigeration compliance) impose discrete dates that can shift demand patterns for certain chemical intermediates and refrigerant substitutes — a timing factor that cannot be ignored in plant schedule decisions.
- Concentrated supply base: A small group of integrated and merchant suppliers controls the lion’s share of available polymer‑grade isobutene, which raises the strategic importance of diversified sourcing, long‑term off‑take frameworks and supplier risk assessments.
Market trajectory and what the numbers mean for 2026 decisions
Between 2020 and 2025 the market expanded significantly, driven by downstream demand for butyl rubber, fuel additives and specialty elastomers. Our forecast to 2032 embeds a steady CAGR of ~4.45%, reflecting steady downstream growth, incremental conversion of refinery/cracker C4 streams into higher‑value derivatives, and an emerging share of bio‑derived isobutene solutions. For 2026 planning this implies:
Isobutene Market
- Capital projects sanctioned late in 2026 must assume modest but persistent volume growth; break‑even horizons are achievable but sensitive to feedstock and energy cost assumptions.
- Procurement teams should model both long‑term contracted volumes and a disciplined spot exposure strategy — the latter because Q4 2025 already showed buyers returning to spot markets as inventories and crack spreads adjusted.
- Commercial strategies (pricing tiers, premium product positioning, and certification for low‑carbon content) will compound returns for suppliers who can credibly offer differentiated, high‑purity grades.
Dynamics shaping supply, pricing and risk
Our dynamic analysis focuses on four interlinked drivers that will determine margin evolution and availability in 2026:
- Feedstock & energy inputs: Isobutane and broader refinery/cracker economics remain the single largest cost lever. The market saw a period of feedstock softening in 2025 owing to elevated inventories and weaker crude derivatives — yet late‑2025 operational pressures at some cracker/refinery assets tightened quotations as buyers rebalanced inventories.
- Regulatory timing & compliance: Recent regulatory activity related to technology transition programs and HFC phase‑downs introduces compliance milestones that meaningfully affect demand in certain niche applications and can prompt accelerated procurement or product reformulation cycles.
- Geopolitical & trade constraints: Sanctions and restricted access to certain production hubs have constrained export flows from specific suppliers, tightening availability in some derivative chains and raising the value of supply diversification.
- Decarbonization & new feedstocks: Emerging bio‑based isobutene offerings are moving from pilot to commercial demo stages. While volumes remain modest today, they provide strategic optionality for customers targeting low‑carbon supply chains and regulatory preference.
Competitive landscape — who matters and why
The isobutene market is dominated by vertically integrated petrochemical players and a smaller set of specialized merchant processors. Our competitive analysis combines capacity footprints, integration advantages, technology roadmaps and recent strategic moves to identify near‑term winners and strategic vulnerabilities:
- Global integrated majors (e.g., large refiners and crackers): Players with integrated refinery/cracker complexes are advantaged on cost and feedstock flexibility. Their ability to redirect C4 streams into higher‑value derivatives provides margin resilience when markets soften.
- Merchant specialists and dedicated processors: Dedicated isobutene processors and merchant suppliers capture value through product purity, flexible packaging and fast response to spot demand — attributes that are increasingly valuable in lubricant additive and specialty elastomer markets.
- Technology leaders and low‑cost exporters: Firms with proprietary catalyst routes, ultra‑low feedstock cost bases, or integrated downstream platforms can compress time to market for new grades and defend against margin erosion through scale and techno‑economic advantage.
Key companies profiled in our analysis include large integrated producers, regional champions and innovators in bio‑isobutene. We map each firm’s strategic positioning — from co‑production models, steam‑cracker integration and high‑purity gas supply, to merchant processing and emerging bio‑routes — and evaluate how recent moves (capacity expansions, technology partnerships and plant upgrades) alter competitive dynamics going into 2026.
Recent strategic moves that change the 2026 playbook
- Several merchant processors and majors announced capacity upgrades or expansions across 2024–2025 to strengthen regional supply footholds — a signal that suppliers expect baseline growth and are seeking to capture higher‑margin specialty streams.
- Technology partnerships focused on catalysts and process optimization are reshaping production cost curves and product quality, enabling players to target premium application segments.
- Bio‑based pilots moving toward commercialization create a staged disruption path: regulatory‑driven demand for low‑carbon chemicals can produce early‑mover advantages for certified suppliers.
What this report contains — practical outputs for the executive team
Designed as an operationally actionable intelligence package for 2026 planning cycles, the full study provides:
- A detailed historical and forecast market model (2020–2032) with scenario runs that stress‑test price, feedstock and policy variables.
- A plant‑level capacity map and utilization analysis to identify pinch points and potential sourcing gaps.
- Supply‑cost curve and margin sensitivity matrices for different feedstock and energy scenarios.
- Commercial playbooks for procurement, including contract templates, inventory sizing heuristics, and spot vs. term coverage strategies.
- A supplier due‑diligence framework tailored to isobutene's purity and logistics constraints, plus an M&A heatmap highlighting consolidation possibilities and distressed asset opportunities.
- Regulatory impact analysis and a compliance timing matrix tied to specific product categories and regional timelines.
How to use this intelligence in 2026 planning
Executives should translate these insights into three clear actions for the 2026 planning cycle:
- Lock in optionality: Structure a mix of long‑term off‑take contracts with flexibility clauses and staged spot exposure. Use indexed pricing terms tied to feedstock proxies to protect margin in volatile spreads.
- Prioritize feedstock resilience: Where possible, secure diversified C4 streams or invest in upstream integration to reduce vulnerability to short‑term cracker outages and geopolitical supply interruptions.
- Invest selectively in differentiation: Target investments that yield premium positioning — high‑purity grades, low‑carbon certification, or downstream integration into specialty elastomers — rather than broad capacity increases in commoditized streams.
Conclusion — the strategic payoff
For leaders making capital allocation, sourcing and commercial strategy decisions in 2026, the isobutene market presents a predictable long‑run growth story overlaid by tactical volatility and concentrated supply dynamics. Success will not be about forecasting the next quarterly price move; it will be about designing structurally resilient sourcing, targeted differentiation in product offerings, and regulatory‑aware operating models. Our study distills the market’s five‑year signals into a set of executable choices that preserve upside while mitigating downside.
Next steps
This article highlights the analytical depth and practical orientation of our full Isobutene Market study while deliberately omitting the granular segmentation tables and proprietary plant‑level data that form the core of our competitive advantage. To access the complete dataset, scenario models and the supplier heatmap essential for 2026 decision‑making, visit our report page and download the full briefing.
For detailed analysis of this topic, please visit the official page: Isobutene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com