

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cutting Tools Market — USD 25.78B in 2025, poised for 6.4% CAGR to 2032

Cutting Tools Market: Strategic Briefing for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present a focused, actionable orientation to our new Cutting Tools Market study. This briefing translates the study’s macro vantage into immediate implications for executives preparing strategy and capital allocation decisions in 2026. It demonstrates the report’s analytical depth while preserving the proprietary, granular segment intelligence that drives operational decisions — the exact segment-level allocations and unit economics are reserved for the full report and supporting datasets.
Cutting Tools Market
Sizing and trajectory: where the market stands
The cutting tools market has moved from a cyclical recovery in the early 2020s into a structurally expanding industry. Our study benchmarks the market at USD 25.78 Billion in 2025 (base year) and documents steady growth from 2020. Looking forward, the market is expected to expand at a compound annual growth rate (CAGR) of 6.4% through our forecast horizon (2026–2032), with total revenues approaching USD 40 Billion by 2032. That trajectory reflects both secular demand drivers — industrial automation, electrification of automotive powertrains, and continued capital renewal in precision-machining sectors — and transient rebounds in end-market activity.
Cutting Tools Market
Why this research matters for 2026 decisions
- Capital allocation: Accurate, consensus-calibrated topline growth and scenario outputs let you prioritize CAPEX and R&D investments for a medium-growth environment rather than a high‑growth or recessionary one.
- Supply chain resilience: The report quantifies exposure to raw-material and trade-policy shocks, enabling supply‑chain reconfiguration and hedging strategies that protect gross margins under tariff volatility.
- Portfolio optimization: Actionable frameworks in the study allow firms to align product portfolios (materials, geometries, coatings) to the demand mix that will drive value through 2032.
- M&A and partnership screening: With market concentration metrics and competitive maps, the study supports quick-screening of bolt-on targets and strategic alliances for scale, capability or geographic reach.
Core market dynamics shaping strategy in 2026
- Raw-material pressure and input risk: Tungsten carbide — a core feedstock — has seen cost escalation. Higher raw-material prices compress margins and force choices between absorbing costs, raising prices, or accelerating material substitution and yield improvements. Tactical responses range from hedging and forward purchase agreements to invest-to-save in recycling and remanufacturing programs.
- Trade and regulatory friction: Recent policy actions — export controls and tariff enhancements on tungsten products and related inputs, along with ongoing investigations affecting industrial equipment imports — have materially increased geopolitical supply risk. These developments make dual‑sourcing, nearshoring, and tariff engineering non‑optional elements of procurement strategy through at least 2027.
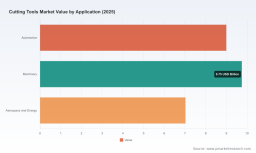
- End‑market mix and product evolution: Demand remains driven by traditional anchors — automotive, general machinery, and aerospace/energy — but the technical mix is shifting toward higher‑value specialty geometries, coatings and multi‑material solutions (e.g., carbide+ceramics). Manufacturers and distributors able to fast-follow design wins with application‑specific toolsets capture disproportionate margin expansion.
- Aftermarket and services monetization: Tool lifecycle services — regrinding, coating refresh, digital monitoring of tool life — are emerging as predictable, higher-margin annuities. Our research demonstrates how service models improve customer retention and create premium pricing opportunities.
- Digital and manufacturing productivity: Digitalization (tool‑life analytics, adaptive machining, integration with CAM systems) is moving from novelty to operational requirement. Early adopters report measurable cycle‑time and scrap‑reduction gains that translate into stronger purchasing justification for premium-priced tools.
Recent industry signals: what to watch
- Demand pulse: US shipment data indicates a strong near‑term upswing in cutting‑tool demand; shipment releases for early 2026 show double‑digit year‑over‑year increases in certain months — a signal of resumed industrial capex in specific end markets.
- Catalog and breadth plays: Several suppliers expanded product breadth in early 2026, launching larger catalogues and extended product families — a clear move to increase wallet share with OEMs and distributors.
- Targeted product innovation: Major suppliers announced new grades and micro‑tools in Q1–Q2 2026, underscoring continued emphasis on higher‑precision, specialized tooling for micro‑machining and challenging materials.
Competitive landscape: concentration and strategic archetypes
The market exhibits moderate consolidation: the top three players capture a meaningful portion of global revenue, and the top five widen that share notably. That structure creates a mixed arena where global technology leaders coexist with nimble specialists and strong regional players. Key competitive archetypes found in our fieldwork include:
Cutting Tools Market
- Global system suppliers with integrated offering sets (advanced grades, tooling systems, and application engineering) — these firms compete on technology and OEM relationships.
- Specialists focused on niche geometries, remanufacturing, or miniaturized tooling — they defend margin through technical differentiation and service models.
- Distributors and hybrid manufacturers that scale through catalog breadth and logistics excellence.
Representative companies profiled in the study range across these archetypes: established multinational manufacturers active in advanced grades and tooling systems; specialized carbide and reamer makers with remanufacture capabilities; and catalog/distribution leaders that emphasize breadth and quick fulfillment. The report includes diagnostic profiles of each, analyzing capabilities, channel leverage, and M&A posture while preserving commercially sensitive details for subscribers.
What the full report delivers (operational, not just descriptive)
- Topline market sizing and a granular growth model covering 2020–2032, with scenario runs that isolate the impact of raw‑material shocks and tariff regimes.
- Segmentation by region, material/type and application — with implied unit economics, margin models and relative growth velocity (note: detailed segment allocations and unit prices are gated in the full dataset).
- Comprehensive supply‑chain map, from primary feedstocks to finished‑good distribution, with points of vulnerability and recommended mitigations.
- Competitive benchmarking for leading suppliers (technology, channel, IP and service capabilities) and a M&A and partnership playbook tailored to different buyer profiles.
- Actionable go‑to‑market playbooks for OEMs, distributors and captive toolrooms: pricing levers, service bundles, digital productization approaches and sample ROI cases.
- Regulatory and trade-impact assessment, including tariff sensitivity tables and recommended procurement hedges for 12‑month and 36‑month horizons.
Strategic imperatives for 2026 (what leaders are doing now)
- Adopt a tiered sourcing strategy: combine secured long‑term contracts for critical carbides with strategic inventory buffers and vetted secondary suppliers outside single‑source jurisdictions.
- Invest in remanufacturing and recycling: recycle tungsten‑bearing scrap to reduce exposure to market price swings and create a defensive cost advantage.
- Prioritize product‑led differentiation: accelerate launches of geometry‑specific toolsets and coatings that are proven to reduce cycle time or extend tool life — these justify premium pricing and deepen OEM relationships.
- Monetize aftermarket and services: build subscription or outcome‑based contracts (e.g., cost per hole, availability‑backed services) to stabilize revenue and improve customer stickiness.
- Scenario‑test tariffs and export controls: operationalize contingency plans that include nearshoring, tariff pass‑through mechanisms, and hybrid production footprints.
- Leverage digital tooling: couple tool telemetry with CAM integration to deliver measurable productivity improvements to customers and create commercialization hooks for premium tools.
- Use M&A selectively to fill capability gaps: prioritize targets that deliver immediate margin expansion (service platforms, remanufacturers) or accelerated access to strategic end markets.
Scenario planning and next steps
2026 is a year of choices: the market’s mid‑single‑digit CAGR provides stable growth, but rising input costs and geopolitical trade measures make execution risk asymmetric. Leading firms will tilt their portfolios toward higher‑value offerings, lock in more resilient supply chains, and convert product innovation into recurring service revenues. They will also run robust scenario analysis — which our study supplies — to quantify how a shock (e.g., extended export controls or a multi‑year raw‑material spike) affects demand, margin and capital needs across business lines.
PW Consulting’s Cutting Tools Market report is designed for executives who need both the strategic frame and the hands‑on playbooks to act now. The full report and dataset provide the gated segment economics, provider scorecards, and interactive scenario models that are indispensable for detailed action planning. For the granular segment allocations, supplier scorecards, and downloadable scenario models referenced here, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Cutting Tools Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com