

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Indium Market to grow at 6.5% CAGR (2026–2032)

Indium Market 2026: Strategic Preview for Decision-Makers
Executive teaser
As strategic advisors to senior management teams in materials, electronics, and semiconductor ecosystems, PW Consulting presents this executive preview of our Indium Market study. The research distills years of primary and secondary intelligence—policy scans, price modeling, producer interviews, and demand scenarios—into actionable guidance for decisions that will shape 2026 sourcing, investment and vertical-integration strategies.
Indium Market
Why this matters in 2026
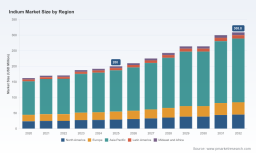
Indium sits at the intersection of electronics materials, photonics substrates, and specialty alloys. After a measured recovery through the early 2020s, the market expanded from an estimated USD 162.3 Million in 2020 to USD 200.0 Million in our 2025 base year, and our bottom-up models project growth to roughly USD 308.8 Million by 2032. That trajectory implies a compounded annual growth rate of 6.5% over the 2026–2032 forecast window—sufficient to change investment appetites across supply chain tiers.
Indium Market
For 2026 corporate planning, this means firms must move beyond short-term spot market reactions and adopt multi-dimensional strategies: secure diversified feedstock, protect supply through contractual levers, invest in alternative materials or recycling capacity, and prepare for regulatory shocks that can rapidly alter regional sourcing economics.
Indium Market
What the full PW Consulting study delivers (practical scope)
- Market sizing and trend calibration: rigorous historical reconciliation (2020–2025) and probabilistic forecasting (2026–2032) with scenario ranges tied to demand drivers and price elasticity assumptions.
- Supply-side analysis: asset-level mapping of primary production, smelter byproducts, and secondary (recycled) capacity, plus near-term expansion and closure risks.
- Demand decomposition framework: end-use drivers, substitution risks, and sensitivity matrices that translate unit demand into dollar exposure under alternative technology scenarios.
- Price formation and cost curve modeling: warehouse price scenarios, input-cost pass-through, and inventory-to-consumption ratio thresholds that historically precipitate price spikes.
- Regulatory and trade-impact playbook: quantified scenarios for tariffs, export controls, and licensing requirements—together with mitigation tactics and contingency contracting language.
- Competitive intelligence and transaction-ready output: supplier scorecards, M&A target shortlist, and integration checklists for buyers evaluating downstream moves (manufacturing, recycling, or wafer fabs).
- Operational tools: procurement negotiation templates, hedging decision trees, and a risk-heatmap dashboard tailored for supply chain and corporate development teams.
Market outlook—what the numbers mean for strategy
The market’s increase from the early-2020s base into 2025 demonstrates both demand resilience and the impact of supply-side concentration. Our modeled path to roughly USD 309 Million by 2032 is driven by continued consumption in established electrically conductive coatings and by accelerating new demand pockets in photonics substrates and advanced packaging. A steady 6.5% CAGR is large enough to incentivize upstream capital allocation but small enough that entrants will require differentiated capabilities—cost, reliability, or recycling—to displace incumbent supply.
Because the market is moderately concentrated, strategic moves by a small set of producers or refiners have outsized effects on pricing and availability. Our market concentration metrics indicate a dominant top-three share and a substantial top-five share, underscoring why supply diversification and long-term offtakes are core elements of a robust sourcing strategy.
Supply-demand dynamics and risk flashpoints
- Geopolitical and trade policy: Recent policy actions—such as the 25% ad valorem tariff on specified critical minerals announced by the U.S. and new export licensing requirements introduced by a major producing country—have materially increased trade friction and upstream risk premia. These are modeled in our baseline and downside scenarios.
- Price volatility: Warehouse prices for refined product showed abrupt movement in 2024, with estimated average prices increasing materially year-on-year; our scenario work illustrates price thresholds where downstream buyers typically accelerate substitution and recycling initiatives.
- End-use concentration: Indium tin oxide (ITO) coatings continue to be the largest single consumption application globally. Changes in display technology roadmaps, notably shifts between LCD and emissive display platforms or adoption of oxide conductors, are built into our demand sensitivity runs.
- Recycling and secondary supply: Secondary recovery remains a strategic lever to smooth supply shocks. Our operational playbook details the breakeven horizon for investments in recovery versus long-term contracted purchases.
Competitive landscape—who to watch
We profile manufacturers, refiners, recyclers, and advanced materials players that collectively shape availability, technology direction, and pricing dynamics. Key participants covered include:
- Indium Corporation (Clinton, New York, United States) — A premier manufacturer and supplier focused on high‑purity indium metals, compounds, alloys, solders and thermal interface solutions for electronics, semiconductor and photonics markets. Recent strategic R&D collaborations and product innovations underscore its role in shaping U.S. supply options.
- Umicore (Brussels, Belgium) — An advanced materials and recycling leader with capabilities in indium refining and circular supply solutions for electronics and telecommunications. Their public disclosures emphasize positioning in semiconductor materials supply chains.
- Teck Resources Limited (Vancouver, Canada) — A primary producer sourcing indium as a byproduct of base-metal operations; operational decisions at primary mines materially affect upstream throughput.
- Dowa Holdings Co., Ltd. (Tokyo, Japan) — A vertically integrated producer and recycler supplying both primary and secondary feedstock to high-tech markets.
- Korea Zinc Co., Ltd. (Seoul, South Korea) — A major smelter with high‑purity product streams serving display and semiconductor markets.
- Nyrstar (Brussels, Belgium) — A zinc and lead producer with byproduct indium recovery and refining operations that can flex regional supply balances.
- PPM Pure Metals GmbH (Ganderkesee, Germany) — A specialist supplier of high‑purity indium and alloys targeting semiconductor and research applications.
- AXT Inc. (Fremont, California, United States) — A manufacturer of indium phosphide (InP) substrates and wafers for telecom and photonics; noteworthy as photonics wafer capacity expansions reshape substrate demand.
Recent developments we track include strategic R&D alliances, product awards, and infrastructure investments that increase regional production or processing density. Examples include partnerships to expand critical metals production capacity, industry awards that validate supplier sustainability performance, and the construction of industrial-scale photonic wafer fabs—each of which has supply, margin and technology implications.
Strategic implications and recommended plays for 2026
- Procurement: Move from spot-only purchasing to blended strategies combining multi-year offtakes, conditional call options, and local buffer inventories sized by our inventory sensitivity models.
- Supply diversification: Prioritize secondary-sourcing pathways and certified refiners with transparent traceability to mitigate export-control and tariff shocks.
- Vertical options: Evaluate selective downstream integration or minority equity in recyclers and substrate fabs where long-term demand linkage or technology ownership provides competitive advantage.
- Substitution and product design: Fund R&D pilots to qualify indium-reducing or indium-free material systems for non-core product lines, with trigger points set by our price-implementation matrix.
- Regulatory readiness: Establish a trade-policy watch and rapid-response playbook, including contract language and insurance instruments, to address tariff escalations or licensing restrictions.
How to use this preview—and what’s withheld
This preview is designed as a decision-grade orientation, not a replacement for the full dossier. To preserve commercial value and encourage direct examination of the source analysis, granular segmentation tables (regional and application-level breakdowns), detailed supplier market shares, and transaction-ready financial models are intentionally withheld from this summary. These elements are included in the full PW Consulting Indium Market report, which contains downloadable spreadsheets, scenario toggles, and supplier due-diligence appendices.
Next steps for executives
- Book a brief with PW Consulting’s Indium practice to receive a tailored briefing that maps our scenarios to your product portfolio and procurement exposures.
- Request the scenario workbook to run your own sensitivity tests on pricing, inventory and substitution timelines.
- Engage our M&A and supply assurance teams if considering upstream investments, strategic partnerships with recyclers, or offtake negotiations with key refiners.
Closing perspective
By 2026, indium will no longer be a niche raw material issue discussed only by commodity teams; it will be a cross-functional strategic variable that affects manufacturing timelines, product roadmaps and capital allocation. Our study equips leaders to translate the market’s projected expansion—from a 2025 base into a robust 2032 outlook at a projected 6.5% CAGR—into defensible, executable plans. For organizations that move early—securing diversified supply, investing in circularity, and operationalizing policy-readiness—the market growth ahead represents a durable competitive opportunity. For those that delay, the combination of trade friction, concentrated production and price volatility will raise the cost of doing business.
To obtain the full report, datasets, and scenario workbooks, visit the PW Consulting Indium Market report page or contact our Indium practice lead for a confidential briefing.
For detailed analysis of this topic, please visit the official page: Indium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com