

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: LVT Market Set to Hit USD 213.2M by 2032 at 3.55% CAGR

Luxury Vinyl Tile (LVT) Market — Strategic Intelligence Briefing for 2026
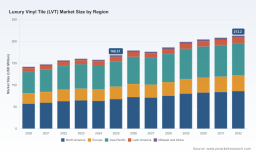
As companies plan capital allocation and product strategy for 2026, the Luxury Vinyl Tile (LVT) market sits at an inflection point where incremental growth, raw‑material shocks, and sustainability-driven regulation converge. Our proprietary market sizing places the global market at approximately USD 168.31 Million in the 2025 base year, with a steady compound annual growth rate of about 3.55% through the 2026–2032 forecast window. By 2032 the market is forecast to surpass USD 213 Million under the baseline scenario. These headline figures mask a more dynamic underlying picture — one that demands a calibrated mix of procurement discipline, product innovation, and regulatory foresight. This briefing explains why the full PW Consulting LVT Market study is essential for executives making strategic bets in 2026, and what decision‑ready outputs you will be able to act upon immediately.
Luxury Vinyl Tile (LVT) Market
Why this research matters in 2026
- Volatility in feedstock and its near‑term cost pass‑through. Recent sharp rises in PVC resin pricing — driven by oil price swings, ethylene supply constraints and geopolitically induced dislocations — materially increase manufacturing cost risk for LVT producers. Our analysis identifies which manufacturing and product archetypes are most exposed to resin price moves and where margin compression versus price pass‑through is most likely.
- Regulatory inflection points. The removal of certain export rebates and evolving chemical lists (notably upcoming LBC Red List revisions) are altering global supply economics and product formulation choices. These regulatory shifts accelerate demand for non‑PVC or hybrid formulations in specific channels and place compliance and certification at the center of go‑to‑market planning.
- Decarbonization and reputational dynamics. Leading suppliers are already quantifying emissions reductions — for example, a recognized global player reported a 27% reduction in Scope 1–3 emissions in 2025 en route to interim targets. Buyers and procurement teams will increasingly evaluate supplier supply‑chain traceability and lifecycle footprints as part of sourcing and specification decisions.
- Market structure: fragmentation with scale pockets. The competitive field remains fragmented — modest market concentration leaves room for regional champions, private label growth, and opportunistic consolidation. That structure influences pricing dynamics, supplier bargaining power, and the attractiveness of vertical integration or strategic JV arrangements.
Report deliverables — practical, transaction‑ready outputs
PW Consulting’s full report is structured to support immediate executive action rather than academic description. Key operational deliverables include:
Luxury Vinyl Tile (LVT) Market
- Transparent market‑sizing and forecasting methodology. A replicable top‑down and bottom‑up model covering historical 2020–2025 performance and scenario forecasts through 2032, allowing you to rebase assumptions to your cost, pricing and mix inputs.
- Scenario toolset. Three investable scenarios (baseline, raw‑material shock, regulatory acceleration) with elasticities for price, volume and margin by product architecture, enabling rapid stress tests for business plans and M&A targets.
- Supplier and capacity map. A verified map of manufacturing footprints, tiered supplier capabilities, and near‑term capacity expansions — designed for procurement to target sourcing diversification and for strategy teams to evaluate insourcing or greenfield opportunities.
- Channel and product playbooks. Actionable GTM tactics for core channels (commercial specification, residential retail, institutional procurement) including sample specification language to accelerate listing and reduce project approval cycles.
- Sustainability & compliance toolkit. A stepwise R&D and procurement pathway for reformulating toward low‑VOC, reduced‑PVC or hybrid constructions, aligned with certification timelines and likely Red List impacts.
- Pricing and hedging framework. Practical guidance for building index‑linked cost pass‑through clauses, resin hedging approaches, and margin protection strategies for both manufacturers and distributors.
- M&A and partnership screening matrix. A prioritized lens for targets based on capacity fit, product adjacency, geographic exposure and regulatory risk — designed for private equity and strategic buyers evaluating bolt‑on or consolidation plays.
Competitive landscape — how leading suppliers are positioning
The LVT supplier universe spans multinational flooring conglomerates, regional specialists, and high‑volume manufacturers. Our competitive analysis synthesizes strategic imperatives for the market’s most influential players and highlights where value creation is concentrated:
Luxury Vinyl Tile (LVT) Market
- Mohawk Industries (Dalton, Georgia) — Emphasizing premium LVT and rigid‑core ranges, Mohawk’s collections focus on high‑value aesthetics and differentiated textures. Their product cadence targets premium retail and specification channels where brand and design command price premiums.
- Shaw Industries Group (Dalton, Georgia) — With resilient SPC and LVT portfolios under identifiable brands, Shaw concentrates on integrated supply‑chain advantages and broad distribution networks, particularly in North American retail and commercial channels.
- Tarkett (Marseille, France) — Notable for accelerating non‑PVC innovations and hybrid offerings, Tarkett’s recent ReNue hybrid product expansion illustrates how incumbents are hedging regulatory and raw‑material risk through material diversification.
- Karndean Designflooring (Lichfield, UK) — A design‑led specialist with a strong emphasis on waterproof and durable aesthetics, Karndean’s activity underscores the ongoing premiumization of residential and boutique commercial segments.
- Interface, Inc. (Atlanta, Georgia) — Focused on high‑performance commercial LVT formats, Interface leverages specification relationships and sustainability credentials to defend margin in institutional procurement.
- Gerflor, Forbo, COREtec and regional leaders — These vendors concentrate on differentiated surface treatments, low‑VOC and compliance‑driven product families, and are increasingly visible in Europe and specialized commercial projects.
- Large Chinese manufacturers and OEMs — A cohort of high‑volume producers continues to supply realistic wood and stone visuals at scale. Their strategic moves into foreign markets, vertical integration and price leadership materially shape global supply dynamics.
Collectively, the market shows limited top‑end concentration: the top three and top five shares indicate a fragmented landscape with space for differentiated brands and low‑cost scale players alike. That structure shapes competitive tactics — from specification capture and design innovation to aggressive channel expansion and selective vertical integration.
Risk scenarios and sensitivity levers we model
- Raw‑material shock. We model the P&L pass‑through for sudden PVC resin price spikes (the industry has already experienced outsized moves linked to Middle East conflicts and supply constraints). The report identifies product formats and geographies where hedging or formula change achieves the fastest margin stabilization.
- Regulatory acceleration. With anticipated LBC Red List updates and changing export tax regimes, we stress‑test reformulation timelines and certification bottlenecks, quantifying time‑to‑market impacts for non‑PVC alternatives.
- Demand reallocation. We consider scenarios where commercial specification demand weakens versus residential premiumization, showing where SKU rationalization and channel re‑focus yield the fastest ROI.
How executives and investors should use this intelligence in 2026
- Procurement & supply‑chain teams: Rebalance supplier portfolios now — diversify resin sourcing, establish conditional contracts with escalation triggers, and onshore critical SKUs to reduce geopolitical exposure.
- Product and R&D leaders: Prioritize hybrid and low‑PVC formulations for channels where regulation and customer demand converge; invest in production modularity to switch face layers and cores with minimal downtime.
- Commercial and specification teams: Use the report’s channel playbooks to shorten approval cycles in healthcare, education and corporate interiors; emphasize third‑party certifications and lifecycle impact data in bids.
- Corporate development & PE: Target acquisitions that add capacity in resilient geographic nodes, or that provide proprietary surface treatments and non‑PVC chemistry — both high ROI levers in a tightening regulatory landscape.
- Boards & CFOs: Ensure scenario‑based stress tests inform capital allocation — particularly for plant expansions where resin exposure and energy inputs are significant operating cost drivers.
What we intentionally hold back — and why
True to the “trailer” principle, this briefing demonstrates the depth and practical utility of our analysis while deliberately omitting granular segment and regional tables. The report contains those detailed split matrices, SKU‑level margin curves, and supplier scorecards necessary for negotiation and investment decisions. Those assets are provided within PW Consulting’s full subscription package and are designed to be operationalized directly into ERP, procurement and M&A diligence workflows.
Next steps — how to convert insight into advantage
- Secure the full market model and scenario workbook to run your internal sensitivities against our baseline forecasts.
- Request the supplier‑capability map and procurement playbook to begin a three‑month supplier diversification program.
- Engage PW Consulting for a rapid 8–12 week product portfolio and cost‑to‑serve optimisation sprint tied to the regulatory timelines most likely to affect your products.
In a market that is growing steadily at an identifiable compound rate but is simultaneously vulnerable to supply, regulatory and sustainability shocks, the difference between winning and lagging will be set by who moves first on procurement strategy, product reformulation and certification. Our full LVT Market Report provides the executable playbooks, verified supplier intelligence, and scenario tools you need to make those moves decisively in 2026.
— PW Consulting, Senior Strategic Advisory & Industry Analysis
For detailed analysis of this topic, please visit the official page: Luxury Vinyl Tile (LVT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com