

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Smart Gas Meter Market to Reach USD 344.8M by 2032 at 6.98% CAGR

Smart Gas Meter Market — Strategic Briefing for 2026 Decision-Makers
As utilities, meter manufacturers, technology vendors and investors enter 2026, the smart gas meter market is at a clear inflection point. Our PW Consulting Smart Gas Meter Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes market sizing, technology trajectories, regulatory drivers and vendor strategies into an action-oriented playbook. In short, this is the operating manual for executives who must convert regulatory pressure, decarbonization commitments and network modernization budgets into defensible procurement, product and investment decisions.
Smart Gas Meter Market
Market trajectory — what the topline numbers tell you
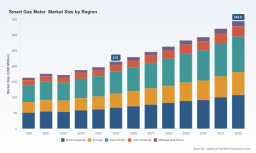
The market has shown steady growth through the early 2020s and accelerated into the mid-decade. Measured in USD (Million), the market increased from the low‑hundreds in 2020 to roughly USD 215 Million in the base year 2025 and is forecast to expand to the low‑hundreds by 2032. Our model applies a compound annual growth rate (CAGR) of 6.98% across the 2026–2032 forecast period, reflecting combined effects of mandated metering accuracy, AMI/AMR rollouts, hydrogen-readiness requirements and continued adoption of low‑power wide area communications for remote readout and analytics.
Smart Gas Meter Market
Those topline dynamics matter because they shape three practical decisions for 2026: (1) the size and timing of procurement waves; (2) the acceptable payback period for advanced features (hydrogen‑compatibility, remote shut‑off, integrated MRV telemetry); and (3) where to concentrate proof‑of‑concepts versus full deployments. The report provides revenue and volume scenarios that convert the headline CAGR into discrete procurement buckets and multi‑year capex planning templates. (Note: our public summary intentionally omits granular segment tables and regional share percentages — full datasets and downloadable models are available on the report landing page.)
Smart Gas Meter Market
Why 2026 is a strategic inflection year
-
Regulatory tightening is compressing timelines. EU regulations on methane measurement and updated energy efficiency directives have already increased minimum accuracy and remote‑readability requirements, while several national authorities are accelerating compliance timelines.
-
Technology readiness has matured. Low‑power communications (LoRaWAN, NB‑IoT), improved ultrasonic sensing and more efficient battery systems have lowered the lifecycle cost of “true” smart gas meters versus legacy mechanical devices.
-
Decarbonization plans are shifting product specs. Hydrogen blending and pure hydrogen readiness are no longer future proofing — product roadmaps and certification pathways must be resolved before large capital deployments.
These forces create a near‑term premium for devices and systems that are demonstrably compliant, low‑lifecycle‑cost and upgradeable. Our study lays out not only the market demand curve, but the operational constraints (meter lifecycles, grid integration timelines, and audit/MRV windows) that make 2026 the last practicable year for many procurement decisions if utilities want to minimize retrofit costs during 2028–2032 upgrades.
Technology and regulatory dynamics to watch
-
Accuracy and MRV: EU Methane Regulation 2024/1787 and related MRV mandates require higher metering accuracy and traceable measurement records. Utilities and vendors will need to demonstrate both device precision and a secure data chain to satisfy audits.
-
Hydrogen compatibility: The industry is bifurcating into hydrogen‑ready meters and legacy designs. Hydrogen‑compatibility is not merely a sensor spec — it entails materials certification, recalibrated algorithms and updated validation regimes. Vendors are already launching multirange diaphragm and ultrasonic products to address this need.
-
Communications and battery life: Low‑power communication stacks and energy‑efficient radio modules are now a baseline requirement. Solutions that extend field battery life materially reduce total cost of ownership and are decisive in large, dispersed residential rollouts.
-
Interoperability & cybersecurity: With smart gas meters increasingly tied into AMI and utility OT networks, encryption, secure boot and interoperability with existing head‑end systems are procurement must‑haves.
Competitive landscape — who’s shaping the market
The market is commercially active and technologically diverse. Leading industrial and metering firms are deploying ultrasonic and advanced diaphragm designs, launching hydrogen‑tolerant platforms, and embedding edge intelligence and remote shut‑off capabilities. Notable vendor moves include:
-
Itron Inc. (United States) — Itron’s Intelis ultrasonic smart gas meters combine integrated shut‑off valves, edge intelligence and AMI compatibility. The company reported having surpassed three million shipments by May 2025, demonstrating strong operational scale in key utility accounts.
-
Honeywell International Inc. (United States) — Honeywell has announced a portfolio that includes ultrasonic residential meters with remote shut‑off and diaphragm variants designed for 100% hydrogen readiness; a multirange residential version was advanced in March 2025.
-
Landis+Gyr (Switzerland) — Landis+Gyr introduced the Surent™ G480 ultrasonic meter for North American utility modernization in February 2026 and secured a large‑scale deployment agreement with Origin Energy in June 2026, signaling aggressive expansion into utility upgrade projects.
-
Sensus / Xylem (United States) — Sensus‑branded next‑generation meters emphasize extended battery life through low‑power communications, with product launches in early 2025 that position them for large grid rollouts.
-
Zenner International (Germany) — Zenner has integrated over ten million sensors into global LoRaWAN networks (reported September 2025), showcasing scale in IoT connectivity and a service‑oriented approach to meter deployments.
-
Diehl Metering, Apator, RMG, Romet, SenseMi, Flonidan and other OEMs — These firms are focusing on analytics platforms, modular meter designs (LoRaWAN/NB‑IoT), and regional certification efforts to capture municipal and commercial business lines.
Collectively, the vendor landscape reflects a market that is technologically competitive but commercially fragmented: several capable vendors are pursuing differentiated go‑to‑market strategies rather than a single dominant incumbent. Our report maps vendor strengths and weaknesses across eight procurement dimensions — technology fit, certification readiness, AMI compatibility, TCO, service footprint, manufacturing capacity, cybersecurity, and upgradeability — so buyers can short‑list suppliers with objective, repeatable criteria.
What the PW Consulting report delivers — practical, decision‑ready outputs
-
Market sizing and scenarios: Topline and scenario models from 2020–2032 (base 2025), with downloadable revenue and unit forecasts by technology class and application tier.
-
Regulatory impact assessments: Regionally contextualized compliance timelines and a checklist for MRV and hydrogen certification readiness.
-
Procurement playbooks: RFx templates, evaluation scorecards, contract clauses for performance warranties, and a failure‑mode analysis to reduce retrofit risk.
-
CapEx / OpEx modelling: Payback calculators that fold in battery life, communication costs, installation and retrofit scenarios to estimate lifetime TCO under different deployment profiles.
-
Vendor dossiers and negotiation guides: Concise profiles of leading suppliers, recent product launches, and a negotiation framework keyed to supply chain constraints and warranty exposure.
-
Roadmaps and implementation templates: Pilot‑to‑scale roll‑out sequencing, data‑integration blueprints for AMI/MDMS, and a phased approach to hydrogen transition that minimizes stranded asset risk.
How executives should use this study in 2026
-
Utilities: Use the procurement playbook and compliance timelines to align meter selection with MRV auditing windows and to avoid costly mid‑life retrofits. Prioritize pilot programs for hydrogen‑readiness in mixed‑blend zones and lock in interoperability requirements in early RFx documents.
-
OEMs and component suppliers: Benchmark product roadmaps against our technology and certification matrices. Identify white‑space opportunities where buyers demand battery lifetimes, retrofitability or integrated safety (remote shut‑off) that are not met by incumbent offers.
-
Investors and project developers: Apply our scenario models to underwriting assumptions for deployment rates and warranty exposure. The growth profile and vendor fragmentation create acquisition opportunities in services, communications, and analytics enablers.
-
Systems integrators and software firms: Leverage the AMI/MDMS integration blueprints to accelerate time‑to‑value and package compelling OPEX‑based offerings for utilities seeking to outsource metering intelligence.
What we intentionally withhold — and where to find it
This introductory briefing demonstrates the depth and practical focus of the full PW Consulting Smart Gas Meter Market study, but it omits certain granular segmentation tables and discrete regional/application share percentages in order to preserve the full commercial value of the report. The comprehensive dataset — including detailed regional forecasts, unit‑level breakdowns by diaphragm, ultrasonic and other types, application splits (residential, commercial, industrial), and the full vendor market shares and concentration metrics — is available on the report landing page and via our secure data portal. For procurement teams, the downloadable RFx templates and TCO calculators require report access.
Closing — the immediate next steps for 2026
For organizations that must decide in 2026 whether to accelerate retrofit waves, standardize on hydrogen‑ready devices, or lock in multi‑year supplier agreements, the value of a tightly focused, data‑driven road map cannot be overstated. The PW Consulting study converts the market’s mid‑decade momentum and regulatory urgency into an executable plan: procurement windows, pilot sequencing, vendor short‑lists and the financial models needed to justify capital allocation.
To access the full dataset, scenario models and procurement assets referenced above, visit our Smart Gas Meter Market report page or contact the PW Consulting research team for a guided briefing and a tailored extract for your deployment geography and operating model.
For detailed analysis of this topic, please visit the official page: Smart Gas Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com