

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Water Leak Detection Market to Reach USD 279M by 2032 at 6.52% CAGR

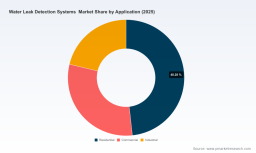
Strategic Preview: Water Leak Detection Systems Market — Why 2026 Is a Decision Year
As PW Consulting’s senior strategic advisor and industry analyst, I present a forward-looking synthesis of the Water Leak Detection Systems market designed to orient executive decisions in 2026. This piece highlights the market’s trajectory, the regulatory and technology dynamics reshaping buying behavior, and the competitive moves that will matter for procurement, product strategy, and M&A. It deliberately previews analytic depth while withholding granular segment tables and regional/application breakouts to preserve the “trailer” experience — the full intelligence, models, and vendor scorecards are available in the source report.
Water Leak Detection Systems Market
High‑level market trajectory: a dynamic growth story
The water leak detection market has evolved from a niche mitigation product to a strategic operational technology. Between 2020 and the 2025 base year, the market expanded materially from the low hundreds to a stronger base — reflecting growing adoption across built environments, utilities, and critical infrastructure. PW Consulting’s forecasting model projects the market continuing to grow at a compound annual growth rate of approximately 6.52% across the next phase, positioning the industry on a sustained growth path through the 2026–2032 forecast horizon. By 2026 the market steps into a new scale, and our 2032 outlook shows the technology ecosystem maturing further as integrated hardware, software and services converge.
Water Leak Detection Systems Market
Why 2026 matters for executives
- Regulatory inflection points are compressing timelines. Mandates and standards—ranging from EU water-management directives to national utility leakage requirements—are converting optional protection spend into structured procurement. Organizations that align procurement, compliance, and asset-management strategies in 2026 will avoid retroactive capex and elevated remediation costs.
- Cost of failure becomes quantifiable. New guidelines and energy/water accounting rules mean that the hidden costs of undetected leaks (lost product, energy to treat and pump water, equipment damage and downtime) are increasingly recognised in corporate P&L and capital planning. Decision-makers who can map detection ROI to these avoided costs gain clear budget priority.
- Technology convergence creates strategic choices. Flow‑based systems, sensor cable networks, acoustic technologies and satellite/AI analytics are converging into multi‑layered detection stacks. 2026 is the year when pilots must either be scaled or shelved—delaying action risks vendor lock‑in or falling behind in interoperability and data standards.
- Service-led offerings reduce total lifetime cost. Vendors are packaging hardware with cloud analytics, automatic shut‑off, and managed monitoring. Buyers must decide whether to buy products, managed services, or hybrid contracts; the wrong model can shift risk and inflate operating cost.
Regulatory and macro drivers shaping procurement
Regulatory pressure is a principal accelerant. Europe’s water management framework and national building‑management standards are pushing institutional buyers toward defined technical specifications and verifiable monitoring regimes. In parallel, utility regulators in various jurisdictions are mandating leakage reduction targets and incentivising investments in pipeline‑level detection. In the United States, federal infrastructure assessments and guidance have elevated the economic case for proactive detection, quantifying treated water losses and their operational impact.
Water Leak Detection Systems Market
These mandates change procurement from a cost‑avoidance exercise to a compliance and resilience programme—affecting vendor selection criteria, metrics for success, and allowable funding sources. Organizations that integrate compliance requirements into their 2026 rollout plans gain both budgetary clarity and competitive advantage in capital allocation.
Technology and deployment dynamics
- Layered detection architectures win. Single‑technology approaches (acoustic only, or flow only) are giving way to layered systems that combine continuous flow analytics, zone addressable sensing, acoustic pinpointing, and remote satellite or aerial leak detection. The combined stack lowers false positives and improves time‑to‑isolation.
- Data and integration are the new battleground. The value of any detection system is amplified by analytics, alert orchestration, and integration with facility management and SCADA systems. Vendors offering open APIs, pre‑built integrations, and strong data governance will command premium positions.
- Service models and managed detection. Expect rising adoption of 24/7 monitoring subscriptions, SLA‑backed response contracts, and outcome‑based commercial models that tie fees to leakage reduction outcomes or response times.
- Labor arbitrage and automation. The high cost of manual inspection—particularly in commercial and industrial facilities—drives demand for automated detection and automatic shutoff, lowering downtime and insurance exposures.
Competitive landscape — who to watch
The market remains moderately fragmented with leading firms capturing a non‑dominant share; the top three firms together account for roughly a quarter of the market and the top five capture around a third. That concentration profile creates fertile ground for differentiation through product depth, service capabilities and channel partnerships.
- Aqualeak Detection Ltd (UK) has positioned itself as a vertically integrated manufacturer offering flow, sensor and distance measuring systems. Recent product launches include connected automatic shutoff devices and multi‑zone addressable EMS systems that speak directly to facility automation teams.
- The Detection Group, Inc specialises in FM‑approved wireless systems with continuous monitoring—focusing on commercial and industrial portfolios where 24/7 uptime is critical.
- Dorlen Products Inc has scale in sensor cable deployments and an installed base spanning many thousands of sites—a strong footing for upselling analytics and managed services.
- FloLogic, MultiTech, HW group, TTK, Megger/SebaKMT, Grove and Badger Meter represent complementary strengths across flow analytics, LoRaWAN connectivity, cable‑based sensing, acoustic leak detection for utilities, IoT sensors, and integrated utility platforms. Each brings differentiated IP that is increasingly being combined in multi‑vendor solutions.
Recent industry activity validates the trends above: in late 2025 and early 2026 several vendors showcased deeper integration and productisation—exhibitions and product launches from major suppliers demonstrated a push to tie detection hardware to SaaS analytics and automatic remediation. Collaborations using AI and satellite analytics have started to surface measurable utility wins, demonstrating that remote sensing can materially reduce leak incidence when integrated into broader detection programmes.
What the PW Consulting report delivers (practical, actionable content)
Our full market study is designed for procurement leads, CTOs, facility managers, utility program directors and corporate strategists. It is intentionally operational and includes:
- Proprietary market sizing and a seven‑year forecast model (historical 2020–2025 baseline; base year 2025), with scenario runs for conservative, base, and accelerated adoption pathways.
- Vendor scorecards and capability heatmaps that evaluate product breadth, service delivery, data integration, and implementation risk.
- Implementation playbooks for three buyer archetypes—utilities, commercial real estate/facilities, and industrial process operators—covering procurement templates, pilot design, KPIs, and O&M governance.
- Technology roadmaps that map sensing modalities (flow, acoustic, cable, satellite/AI), expected unit‑cost trends, and interoperability requirements through 2032.
- Pricing and commercial model guidance, including TCO calculators and contract clauses for outcome‑based or managed services engagements.
- Regulatory impact analysis and compliance checklists tailored to major jurisdictions and standards bodies.
- Strategic M&A and partnership playbooks identifying where scale, data, or channel partnerships can accelerate market entry.
To preserve our clients’ competitive advantage, the report omits some public-facing segment tables from this preview; those detailed splits and company‑level revenue estimates are available within the subscription content.
Strategic implications and recommended actions for 2026
- Prioritise staged deployments tied to compliance. Align pilots with regulatory milestones. Successful 2026 pilots should be designed to validate both operational KPIs (leak detection time, false positive rates) and financial KPIs (avoided loss and mitigation cost).
- Adopt an integration-first procurement spec. Specify open APIs, data export standards, and SCADA/CMMS integration requirements up front to avoid costly rip‑and‑replace cycles.
- Buy outcomes, not only devices. For critical facilities, prioritise vendors or partners that offer outcome guarantees or SLA‑backed monitoring. This shifts risk and aligns incentives for rapid remediation.
- Evaluate hybrid sourcing. Combine best‑of‑breed sensors with centralised analytics and local service partners to balance innovation and reliability.
- Plan for scale with data governance. Define data retention, sharing and privacy policies before deployment so that analytics can be safely monetised or shared across asset portfolios.
Final perspective — what leadership must decide in 2026
Water leak detection is no longer a defensive line item; it is an operational risk play with measurable financial upside. The choices executives make in 2026—about how to integrate detection into asset management, whether to buy outcomes vs. capital assets, and which technology layers to prioritise—will determine cost of ownership and resilience over the next decade. The market’s steady CAGR and the demonstrable wins from recent vendor deployments make the economics compelling. The remaining strategic questions are primarily organizational and contractual.
PW Consulting’s full report equips decision‑makers with the models, vendor intelligence, procurement templates, and implementation playbooks needed to act confidently in 2026. For those ready to convert pilot momentum into enterprise‑scale programmes, the report provides the step‑by‑step guidance and vendor analysis required to de‑risk rollouts and capture measurable returns.
Next step
Access the complete study for the detailed segmentation, the vendor scorecards, and the downloadable forecasting model that underpins our recommendations. The full report contains the granular tables and scenario models that organisations need to finalise 2026 budgets and procurement strategies.
For detailed analysis of this topic, please visit the official page: Water Leak Detection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com