

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Predicts 8.52% CAGR for Environmental Risk Management Market in 2026–2032 Outlook
By pmarketresearch, 2026-07-13
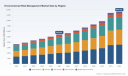
Environmental Risk Management Market: Strategic Imperatives for 2026 — PW Consulting Insights
As organizations confront accelerating climate impact, tighter regulatory scrutiny, and expanding stakeholder expectations, environmental risk management (ENRM) has moved from technical compliance to board‑level strategic priority. PW Consulting’s latest Environmental Risk Management Market report — anchored on a 2025 base year with historical context back to 2020 and forward forecasts to 2032 — synthesizes rigorous market modelling, scenario analysis, vendor due diligence, and practical playbooks intended to inform executive decisions throughout 2026.
Environmental Risk Management Market
Key macro takeaways: the global ENRM market surpassed USD 5.4 billion in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 8.52% through our forecast horizon, approaching the USD 9–10 billion range by the early 2030s. Market concentration remains moderate, with the top three and five players accounting for a meaningful—but not dominant—share, reinforcing a landscape of specialist firms, engineering majors, and new technology entrants competing alongside integrated service providers.
Environmental Risk Management Market
Why 2026 Is a Strategic Inflection Point
- Standards and governance are changing the mandate. The publication of ISO 14001:2026 raises the bar on environmental management systems by elevating climate, biodiversity, and supply‑chain oversight to board‑level concerns and mandating more explicit context analysis. The standard’s three‑year transition window means many organizations will need to accelerate readiness work in 2026 to meet certification timelines.
- Insurance and financial ecosystems are recalibrating risk transfer. Recent market forecasts have highlighted shifting capacity and policy constructs for multinational environmental liabilities. Insurers and risk managers are re‑pricing exposures and demanding greater data transparency and scenario testing before extending coverage.
- Technology and analytics are delivering new leverage. AI, remote sensing, predictive analytics, and integrated risk‑assessment platforms are enabling earlier detection and quantification of environmental risk — but they also introduce vendor‑selection and data‑governance challenges that companies must solve this year.
- Investor and regulator expectations are converging. Survey evidence indicates institutional investors increasingly require formal governance structures and documented ENRM frameworks; 2026 is the year many organisations will need to demonstrate operationalised processes rather than aspirational policies.
What Our Report Delivers — Practical, Actionable Intelligence
PW Consulting’s report is designed as a decision‑support toolkit for executives, in‑house counsel, risk managers, and transaction teams. The deliverables include:
Environmental Risk Management Market
- Robust market sizing and trajectory (historic and forecast), with sensitivity bands to reflect policy, technology adoption, and insurance market shocks;
- Scenario analyses that model policy tightening, catastrophic event clustering, and rapid technology uptake — each mapped to expected financial and operational impacts;
- Vendor benchmarking and capability matrices that evaluate engineering firms, specialist consultants, software providers, and remediation operators against a common set of commercial, technical, and delivery metrics;
- Regulatory readiness playbooks aligned to ISO 14001:2026 and other emergent compliance vectors — including board‑level templated disclosures, audit checklists, and transition timelines;
- Procurement and contracting guidance (SLA examples, performance bonds, indemnity frameworks) tailored to common ENRM engagement archetypes;
- Investment and M&A heat maps that identify high‑opportunity service niches, margin profiles, and strategic partnership routes to accelerate capability build;
- Practical case studies and implementation blueprints illustrating remediation programmes, operational risk reduction, and integrated INSUR‑TECH pilots.
To respect the report’s role as a source of proprietary intelligence, this release deliberately summarizes high‑level conclusions while withholding granular regional/vertical splits and itemised revenue tables. Those detailed sub‑segment datasets and vendor scorecards are accessible through the full report and bespoke advisory engagements.
Competitive Dynamics: How the Leading Players Are Positioning
The ENRM competitive landscape blends global engineering and professional services firms, operational operators, and specialised consultancies. The leading players — spanning engineering majors, environmental consultancies, and remediation specialists — are pursuing distinct but convergent strategies:
- Integration of advisory and delivery: Firms with technical remediation capabilities are bundling assessment, design, implementation, and long‑term monitoring to capture greater lifetime value from clients shifting toward integrated risk management solutions.
- Digital and analytics investments: Many incumbents are either building or partnering to deliver risk assessment platforms, remote sensing integration, and AI‑enabled scenario modelling to meet clients’ demand for quantifiable, auditable risk metrics.
- Service diversification: Beyond classic consulting, market leaders are scaling insurance advisory, environmental liability finance, and operational services (e.g., waste/water treatment) to create defensible revenue streams and stickier client relationships.
- Targeted M&A and alliances: Acquisitions remain a rapid path to capability in niches such as biodiversity assessment, carbon removal verification, and advanced remediation technologies.
For executives evaluating partners or targets, the report’s vendor scorecards provide comparative assessments across technical depth, geographic reach, digital maturity, and contract delivery performance. Given the market’s moderate concentration metrics, there remains ample room for specialist challengers to scale—especially those combining niche technical superiority with cloud‑native analytics and insurance‑grade data governance.
Operational and Investment Priorities for 2026
Based on our modelling and client work, the following priorities should govern capital, talent, and procurement choices in 2026:
- Governance first: Establish or strengthen board‑level oversight of ENRM, with defined KPIs, scenario‑based capital allocation triggers, and linked incentive mechanisms.
- Certify to the new standard: Begin ISO 14001:2026 transition planning immediately. Map gaps in biodiversity, supply‑chain oversight, and climate scenario analysis so certifications can be updated within the transition window without disrupting operations.
- Invest in data and analytics: Prioritise pilots that integrate remote sensing, field sensors, and predictive models into a single risk dashboard suitable for investors, insurers, and regulators.
- Hedge with insurance and contractual levers: Reassess insurance programmes with an eye to new capacity constraints; incorporate stronger contractual protections and third‑party validation requirements in high‑exposure contracts.
- Capability build vs buy decisioning: Use our report’s investment heat maps to decide whether to acquire remediation or analytics capability, partner for rapid access, or build in‑house over a defined timeframe.
- Talent and supplier ecosystems: Expand multidisciplinary teams that combine environmental science, data engineering, and legal/risk expertise; align procurement to prefer providers with robust data‑governance and audit trails.
Stress‑Testing Risks: Scenarios to Model Now
Our report models several plausible risk shocks that materially affect 2026 planning:
- Policy shock: Accelerated national or supranational regulation that shortens ISO transition expectations or imposes stricter liability frameworks;
- Insurance contraction: Capacity withdrawal in high‑liability sectors leading to higher retention and greater demand for risk mitigation services;
- Event clustering: Series of climate‑related incidents concentrating remediation demand and supply‑chain strain, increasing costs and extending project timelines;
- Rapid tech disruption: Breakthroughs in sensors or remediation technology that shift competitive advantage to nimble entrants.
Each scenario is accompanied in the full report by quantified financial impacts, suggested mitigation pathways, and contingency playbooks for operations, procurement, and capital allocation.
How to Use This Intelligence in 2026 Decision Cycles
- Embed report scenarios into annual budgeting and capital expenditure prioritisation.
- Use the vendor scorecards to inform RFIs and to structure pilot contracts with clear performance‑to‑pay milestones.
- Combine our regulatory readiness checklists with internal audits to create a time‑bound remediation plan for ISO transition and related compliance obligations.
- Adopt the report’s M&A heat maps to set acquisition screening criteria and to accelerate diligence for asset‑level environmental liabilities.
Accessing the Full Intelligence
In this briefing we surface strategic conclusions and actionable guidance while preserving the proprietary sub‑segment economics, regional and vertical revenue splits, and full vendor scorecards for the complete PW Consulting report. Those detailed datasets — including the granular regional/industry breakdowns, provider financials, and transactional comparables — are intentionally withheld here to preserve their advisory value and are available via the report portal or through a tailored advisory engagement.
For executives prioritising environmental risk as a strategic agenda item in 2026, PW Consulting offers rapid readiness assessments, bespoke M&A diligence, vendor selection support, and implementation services to operationalise the recommendations in this report.
Contact PW Consulting to schedule a briefing or to obtain the full Environmental Risk Management Market report and supporting datasets.
For detailed analysis of this topic, please visit the official page: Environmental Risk Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Desktop Hypervisor Market to Expand from USD 475.0 Million in 2025 to USD 743.0 Million by 2032 at a 6.61% CAGR — Hosted Hypervisors Lead; North America Tops with USD 200.6M (CR3 82.5%)
By pmarketresearch, 2026-07-13
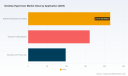
Desktop Hypervisor Market: Strategic Imperatives for Enterprise Leaders — PW Consulting Outlook 2026
Executive summary
PW Consulting’s latest market research on the Desktop Hypervisor Market provides a practical, decision‑ready roadmap for CIOs, CTOs, and procurement leaders preparing budgets and platform strategies for 2026 and beyond. Our bottom‑up model anchors to a 2025 baseline and projects a steady expansion through the forecast period 2026–2032 at a compounded annual growth rate (CAGR) of 6.61%. In dollar terms, the market moves from an indicative baseline in 2025 to an expected mid‑high single‑digit uplift year‑over‑year, with the market size reaching roughly USD 743.0 Million by 2032 under our central scenario.
Desktop Hypervisor Market
Two structural signals should guide enterprise planning immediately: first, the market is highly concentrated — the top three vendors account for the vast majority of revenue capture (CR3 ~82.5%), and the top five approach near‑total dominance (CR5 ~91.3%). Second, technology and policy shifts (including vendor licensing changes and new hypervisor entrants targeting specific workloads) are re‑shaping competitive dynamics faster than many IT procurement cycles can adapt. Our report synthesizes these dynamics into actionable frameworks and tools tailored for 2026 decision windows.
Desktop Hypervisor Market
Why this report is strategic for 2026 decisions
-
Stabilized growth trajectory with tactical inflection points — The projected CAGR provides a reliable macro backdrop for capital and operational planning; however, vendor behaviour and platform announcements create short windows where choices made in 2026 materially affect TCO and lock‑in over the following three to five years.
Desktop Hypervisor Market -
Concentration risk and supply‑side leverage — With a small number of vendors commanding the majority of the market, enterprises must design procurement strategies that balance strategic vendor relationships with hedges against pricing and licensing risk.
-
Security and compliance pressure — Industry standards such as NIST SP 800‑125 and PCI DSS virtualization guidance are converging on stricter expectations for hypervisor lifecycle management, logging, and hardening. These are not optional checkboxes; they materially affect architecture choices between hosted and bare‑metal approaches.
Market dynamics that will shape 2026 playbooks
-
Licensing and go‑to‑market adjustments — Recent vendor moves have reset pricing and distribution norms. Enterprises must treat licensing policy as an active variable in vendor selection, not as a sunk cost. Rapid policy changes can create immediate opportunities for cost reduction or unexpected constraints on deployment models.
-
Diversification of workload targets — Desktop hypervisors continue to serve software development and testing, enterprise IT administration, and education/personal use, but we are seeing rising, specialized adoption for unified communications, virtualization of endpoint security agents, and lightweight VDI scenarios at the edge.
-
Hardware dependencies and performance ceilings — Effective desktop virtualization hinges on host hardware capabilities (e.g., CPU virtualization extensions such as Intel VT‑x or AMD‑V, second‑level address translation (SLAT), and adequate memory footprint). Absent these, nested or multi‑VM workloads experience non‑linear degradation. Our operational playbooks spotlight procurement standards that avoid these bottlenecks.
-
Regulatory and audit posture — For PCI‑relevant and other regulated environments, virtualized desktops introduce additional scanning, logging, and segmentation requirements. The report provides prescriptive controls to reduce audit remediation costs and enforceable checklists for operational teams.
Competitive landscape: what enterprises need to know
The competitive set includes established desktop hypervisor vendors and adjacent platform players. Each brings differentiated strengths and tradeoffs that matter to enterprise purchasers.
-
Broadcom (VMware) — VMware’s desktop hypervisor products remain feature‑rich for cross‑platform development and complex testing workflows. Notably, recent policy updates have materially changed the commercial calculus for some use cases, and procurement teams should reevaluate TCO models that were built on prior licensing assumptions.
-
Oracle (VirtualBox) — As a widely used open‑source option, VirtualBox offers a low‑friction path for broad compatibility across host/guest platforms. It is attractive for labs, developer sandboxes, and budget‑constrained deployments, but support SLAs and enterprise‑grade security integrations should be evaluated case‑by‑case.
-
Microsoft (Hyper‑V) — The built‑in hypervisor on mainstream Windows editions reduces deployment complexity for Windows‑centric environments and leverages operating‑system level integration for management and security. Hardware prerequisites (e.g., SLAT and VT‑x/AMD‑V) remain decisive factors for performance and feature enablement.
-
Parallels (Corel) — Parallels Desktop’s optimized support for Apple silicon and Intel Macs addresses the growing heterogeneous endpoint estate. For organizations standardizing on macOS for developer productivity or design workflows, Parallels provides a performance‑oriented, low‑friction option.
-
Citrix Systems — Historically focused on workspace virtualization, Citrix’s capabilities remain relevant where integration into VDI and managed workspace services is a priority. Enterprises should model integration costs against alternative pure desktop hypervisor strategies.
Recent vendor moves and new entrants — implications for procurement
-
Open policy shifts by major vendors can create one‑time windows for renegotiation or refactoring. Our research details how to operationalize vendor policy changes into renegotiation playbooks and migration pilots.
-
New announcements from infrastructure vendors targeting specific workloads (e.g., unified communications) indicate a trend of verticalized hypervisors. These niche entrants can be compelling for specialized workloads but require careful validation against enterprise security and manageability standards.
What’s in the PW Consulting report — practical deliverables
Beyond market sizing and high‑level trends, the report is structured to be directly useful to teams executing on virtualization strategy in 2026:
-
Decision frameworks: vendor short‑listing matrices, risk scorecards, and a procurement timeline template aligned to typical fiscal cycles.
-
TCO and ROI models: downloadable spreadsheets and scenario runs for common migration paths (lift‑and‑shift, phased refactor, hybrid hosted/bare‑metal) that feed into CAPEX/OPEX planning.
-
Security and compliance playbooks: mapping of NIST SP 800‑125 and PCI DSS virtualization guidelines to operational controls, logging standards, and audit evidence artifacts.
-
Hardware compatibility and procurement checklist: minimum host specifications, SLAT and virtualization extension requirements, and guidance for avoiding common bottlenecks when deploying multiple concurrent VMs.
-
Competitive profiles and negotiation levers: vendor posture analysis, feature tradeoff matrices, and recommended contractual clauses to mitigate concentration risk.
-
Use‑case playbooks: prescriptive deployment designs for development/testing labs, enterprise IT administration, remote learning, and niche workloads such as unified communications virtualization.
Practical first steps for 2026
-
Conduct a hardware triage across your endpoint fleet against minimum SLAT/VT‑x/AMD‑V requirements and map remediation costs into the 2026 budget. Failing to address host capability gaps is the most common cause of poor virtualization economics.
-
Revisit vendor licensing models and apply our short‑form renegotiation playbook to any contract expiring within 12–18 months. Policy changes among major suppliers have recalibrated potential savings and risks.
-
Apply our compliance mapping to any use case that touches regulated data. Early alignment to NIST and PCI expectations reduces audit remediation spend and operational downtime.
-
Run a pilot that stresses both performance and security telemetry. Use the KPI set in our report to validate vendor claims across real workloads before a broad rollout.
Conclusion — the strategic inflection is now
As the desktop hypervisor market grows steadily through the forecast horizon, the combination of concentrated vendor power, evolving licensing paradigms, and tighter security/compliance regimes means 2026 is a pivotal year for firms choosing how to virtualize endpoints. PW Consulting’s report translates the market’s macro trajectory and competitive realities into operational tools designed to reduce risk, optimize costs, and accelerate secure deployment.
For teams writing 2026 budgets, designing migration programs, or recalibrating vendor relationships, the report delivers the practical intelligence and decision engines needed to act confidently. To access the proprietary segmentation tables, granular scenario outputs, and the full set of templates and models that underpin our recommendations, please visit our official PW Consulting report page for the Desktop Hypervisor Market.
For detailed analysis of this topic, please visit the official page: Desktop Hypervisor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Outdoor Warning and Mass Notification Systems Market Poised to Reach USD 4,584.88 Million by 2032
By pmarketresearch, 2026-07-13
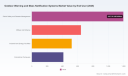
Outdoor Warning and Mass Notification Systems Market: Strategic Briefing for 2026 Decision-Makers
As organizations and public authorities reassess resilience investments in the wake of increasingly complex hazards, the outdoor warning and mass notification systems market is transitioning from point solutions to integrated, policy-driven ecosystems. PW Consulting’s latest market research — based on a 2025 base year and a forecast through 2032 — quantifies this transition and translates it into pragmatic decision levers. Our analysis shows that the global market expanded from USD 1,940.5 Million in 2020 to USD 2,778.0 Million in 2025 and is projected to reach USD 4,584.88 Million by 2032, representing a compound annual growth rate (CAGR) of 7.42% over the 2026–2032 forecast period. This briefing synthesizes the report’s strategic value for 2026 procurement, technology, and program design choices — without disclosing the granular splits that are available in the full report.
Outdoor Warning And Mass Notification Systems Market
Why this matters in 2026
-
Funding windows and regulation are aligning. Government grant programs and legislative initiatives are creating momentary accelerants for modernization programs; program managers who plan now will be best positioned to capture funds and de-risk rollouts.
Outdoor Warning And Mass Notification Systems Market -
Priorities have shifted from pure coverage to integration and intelligence. Agencies increasingly demand systems that support polygon-based alerting, IPAWS compatibility, and on-premise architectures for data sovereignty and operational continuity.
Outdoor Warning And Mass Notification Systems Market -
Vendor consolidation and product lifecycle events are changing procurement dynamics. Buyers face both the opportunity of integrated platforms and the complexity of managing legacy obsolescence.
Market trajectory and what it means for buyers
The market’s steady growth through 2025 and the projected acceleration through 2032 at a 7.42% CAGR reflect multiple converging drivers: capital allocation to civic resilience, regulatory mandates for interoperable alerting, and technology upgrades that enable intelligible, geo-targeted outdoor voice and siren systems. For practitioners this translates into three practical implications:
-
Timing matters. 2026 is a strategic inflection point: projects initiated this year have the best chance to align with available funding cycles and to leverage next-generation standards being embedded by regulators.
-
Integration is non-negotiable. Solutions must support multi-channel orchestration (IP, cellular, siren, giant-voice) and interface cleanly with national alerting architectures to avoid stranded investments.
-
Lifecycle planning beats reactive replacement. With several suppliers updating product roadmaps and issuing obsolescence notices, procuring agencies should adopt vendor-agnostic migration plans that prioritize backwards compatibility, encryption, and modular upgrades.
Regulatory and funding context shaping 2026 decisions
-
Grant and legislative activity has accelerated the market: for example, a major federal grant program earmarked USD 40 million for next-generation warning systems in fiscal 2025, and the SIREN Act introduced in 2026 proposes additional grant streams for siren modernization and sensor integration. These are not one-off events — they alter the sample set of fundable scope items and create windows for larger projects.
-
Standards and platform updates matter operationally: IPAWS enhancements and polygon-based alerting mandates now appear explicitly in procurement specifications, requiring systems to support finer geospatial targeting and standardized message formats.
-
Data sovereignty and cybersecurity requirements are driving on-premise deployment preferences for critical infrastructure and government agencies. Compliance frameworks (e.g., FISMA-like controls) affect architecture choices and total cost of ownership.
Technology and deployment trends — what to prioritize
-
Voice intelligibility and long-range acoustic performance remain core differentiators. Modern outdoor voice systems and long-range acoustic devices now combine power with signal processing to achieve higher message clarity in urban and complex acoustic environments.
-
Networked, encrypted siren stations are replacing isolated mechanical units. Buyers should demand end-to-end encryption, robust remote diagnostics, and the ability to perform secure group updates to avoid field rework.
-
Hybrid architectures — on-premise orchestration with cloud-enabled analytics — offer the best balance between control and capability. They allow local authorities to maintain sovereignty while tapping centralized command-and-control improvements and remote support.
-
Sensor integration and situational triggers (weather feeds, seismic sensors, industrial detectors) are increasingly being bundled into end-to-end offers, shifting value from standalone sirens to ecosystem-enabled decisioning.
Competitive landscape — read the signals, not just the logos
The market exhibits moderate concentration: the top three vendors account for a meaningful share, and the top five increase that footprint further. However, the vendor field is diverse, spanning specialist siren manufacturers, acoustic device suppliers, large industrial players, and regional niche providers. PW Consulting’s report profiles strategic behaviors and go-to-market postures across this landscape to help buyers and investors identify the right fit for their risk profile and procurement timeline.
-
Specialist acoustic and siren firms continue to lead on product performance and domain-specific innovation. Companies with deep heritage in outdoor voice, networked sirens, and encrypted deployments remain preferred for municipality and defense projects.
-
Large systems integrators and industrial players are extending into mass notification, leveraging existing relationships with critical infrastructure operators to offer bundled services and lifecycle support.
-
Regional manufacturers retain advantages in localized standards, service footprints, and faster deployment cycles for smaller jurisdictions.
Selected recent market cues illustrate the competitive and procurement dynamics that will inform 2026 decisions: notable municipal and county deployments have continued through 2025 and into 2026, specialist vendors have won orders emphasizing vocal clarity and long-range coverage, and major suppliers have issued product-line updates and obsolescence notices that will influence replacement cycles.
What the report delivers — actionable content for program leaders
PW Consulting’s full report is designed as an implementation-ready playbook for 2026. Highlights include:
-
Market sizing and conservative-to-aggressive scenario forecasts (2026–2032) to support business cases and capital planning.
-
A procurement decision framework that maps mission requirements to technology architectures and procurement modalities (capex vs. service models), including vendor shortlists by use-case.
-
Vendor scorecards and comparative matrices that evaluate acoustic performance, integration readiness, cybersecurity posture, service coverage, and lifecycle risks.
-
Deployment playbooks: installation checklists, interoperability test plans, and maintenance schedules aimed at reducing time-to-benefit and operational surprises.
-
Regulatory mapping: analysis of grant eligibility, compliance checkpoints, and message-format requirements tied to federal and international standards.
-
Total cost of ownership (TCO) models and phased-upgrade blueprints to support budget conversations and vendor negotiations.
-
Case studies and supplier sourcing templates derived from recent municipal and county projects to illustrate procurement language and risk mitigation strategies.
To preserve competitive advantage for subscribers and to respect client confidentiality, the report intentionally withholds certain granular regional and application-level splits from this public briefing. These detailed allocations, along with supplier-level financial benchmarking and downloadable procurement templates, are available in the full report.
Practical recommendations for 2026 program sponsors
-
Prioritize integration-first procurements. Solicit requirements that mandate IPAWS compatibility, polygon-targeting, and secure remote management to avoid retrofits.
-
Build migration-aware contracts. Include clauses for firmware update support, parts availability commitments, and orderly end-of-life transitions to mitigate obsolescence risk.
-
Leverage available funding windows. Align project milestones to grant cycles and legislative initiatives; structure deliverables to match funder acceptance criteria.
-
Test for operational performance, not just specifications. Include intelligibility metrics and geo-targeted scenario testing in acceptance criteria.
-
Plan for hybrid architectures. Combine on-premise control with selective cloud services for analytics and remote support while preserving sovereignty where required.
Final perspective
For executives, procurement officers, and resilience planners, 2026 represents a strategic crossroads: the market’s growth trajectory and the policy environment together create a window for durable modernization. PW Consulting’s market forecasting and playbook-style guidance translate the sector’s expansion (from USD 1,940.5 Million in 2020 to a projected USD 4,584.88 Million by 2032 at a 7.42% CAGR for the 2026–2032 period) into concrete choices about architecture, sourcing, and program timing. The full report supplies the granular intelligence — including regional and application breakdowns, vendor financials, and procurement templates — that organizations need to convert this strategic moment into resilient, cost-effective systems.
To access the complete analysis, vendor scorecards, and deployment templates referenced in this briefing, please visit PW Consulting’s report page. Our team is available for briefings and bespoke advisory engagements to adapt the study’s insights to your operational and fiscal constraints.
For detailed analysis of this topic, please visit the official page: Outdoor Warning And Mass Notification Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: European bread market valued at $55B in 2025, forecast to reach $65.4B by 2032 on a 2.5% CAGR
By pmarketresearch, 2026-07-13
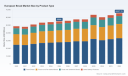
European Bread Market 2026 Preview: Strategic Imperatives for Producers, Retailers, and Investors
PW Consulting's latest European Bread Market report (base year 2025) delivers a practical, decision-focused roadmap for executives preparing budgets, supply strategies, and M&A activity for 2026 and beyond. The European bread market registered steady recovery through 2020–2025 and stood at approximately USD 55,000 million in 2025. Our modelling projects continued expansion across 2026–2032 at a compound annual growth rate of 2.5%, reaching an estimated USD 65,378 million by 2032. This briefing outlines the strategic value of the report for boardrooms and business units while deliberately reserving detailed segment-level tables and region-specific figures for subscribers to the full report.
European Bread Market
Why this report matters for 2026 decisions
-
Actionable foresight for 2026 planning cycles: The forecast cadence and scenario modelling included in the report align with typical capex and commercial planning timelines, translating macro projections into quarterly, channel‑level implications for 2026 budgeting and 2027–2028 operational plans.
European Bread Market -
Risk-first supply decisions: With raw material volatility intensifying, procurement teams need granular stress tests and hedging playbooks to justify supplier contracts, working capital and storage investments. Our report maps likely P&L sensitivity to commodity moves under multiple scenarios.
European Bread Market -
M&A and partnership prioritisation: The study filters potential targets by strategic fit, integration risk and near-term synergies—equipping corporate development teams with a ranked shortlist and valuation heuristics geared to current market multiples.
-
Regulatory-readiness: New and upcoming rules will reshape packaging, labelling and fortification obligations across key jurisdictions. The report translates regulatory timelines into compliance checklists, cost impact estimates and reformulation roadmaps.
Market trajectory and structural characteristics
After a mid‑cycle dip and subsequent rebound in the early 2020s, the European bread market demonstrated resilience through shifting consumer habits and cost pressures. Our base-year sizing (2025) and point forecasts through 2032 show moderate, steady growth—reflecting a maturing market where volume growth is increasingly supported by product premiumisation, convenience formats and bake-off / frozen channels rather than broad-based expansion in staple volumes.
Concentration metrics indicate a market that is not dominated by a single player: the three‑firm concentration and five‑firm concentration ratios point to a competitive landscape where national and regional champions coexist with pan‑European groups and local independents. This structure creates both acquisition opportunities for scale players and white‑space for nimble specialists focused on niche channels.
Key dynamics shaping 2026 outcomes
-
Commodity volatility: Wheat futures have moved materially—our monitoring layer observed prices around USD 666 per bushel as of May 20, 2026, up more than 20% year‑over‑year. That step‑change in raw material cost feeds directly into short‑term margin erosion for producers and can trigger rapid price‑pass through or demand shifts for lower‑cost formats. The report contains sensitivity tables linking wheat price bands to EBITDA impacts at multiple scale points.
-
Packaging and waste regulation: The EU Packaging and Packaging Waste Regulation (PPWR), in force from August 2026, imposes recyclability, recycled content and waste reduction targets. For bread producers and private‑label manufacturers, this creates immediate design and sourcing requirements for primary and secondary pack formats—impacting both cost and shelf logistics. Our compliance roadmap prioritises packaging interventions with the highest ROI and provides supplier assessment criteria for recycled content sourcing.
-
Labelling and fortification obligations: Existing EU consumer information rules continue to enforce nutrition and allergen transparency for prepacked bread products; alongside this, some national regimes (notably the UK) have phased in mandatory flour fortification measures by late 2026. These developments have product formulation and labelling implications that the report quantifies in terms of reformulation cost, labelling change management and audit readiness.
-
Channel evolution: Retail consolidation, the maturation of online speciality retail and the rapid professionalisation of foodservice bakery offer divergent growth vectors. Our channel scenarios examine trade‑off choices—e.g., margin erosion in mainstream grocery versus unit economics in QSR supply agreements and the capital efficiency of bake‑off models for quick service and in‑store fresh offers.
Competitive landscape: what incumbents and challengers are doing
The competitive field is marked by differentiated strategies: global scale players pursue geographic roll‑outs and integration into QSR supply chains; convenience‑focused specialists expand frozen and par‑baked capacity; national champions defend branded premium positions while independents capture artisan and local freshness premiums. The report contains detailed company profiles and strategic play analyses for major operators, including but not limited to Grupo Bimbo, ARYZTA, Lantmännen Unibake, Barilla, Associated British Foods (Allied Bakeries/AB Mauri), and the European Bakery Group.
-
Grupo Bimbo: Operates a pan‑European model that blends sliced and artisan formats, using acquisitive growth to consolidate shelf space and foodservice contracts. Their European footprint demonstrates how global logistics and procurement can be deployed to defend margin against commodity swings.
-
ARYZTA: A clear example of strategic capacity investment—its announced investment in a bun plant near Lisbon in early 2026 signals a targeted play into QSR and Iberian consolidation. The report includes an analysis of how such investments affect route‑to‑market and service-level economics in high‑volume contract channels.
-
Lantmännen Unibake: Expansion via acquisition into the bake‑off and frozen segments illustrates a hedge against in‑store labour scarcity and a move to scale products that fit retail convenience trends. We examine integration risks and synergies when global groups acquire regional artisan producers.
-
Barilla and Associated British Foods: These groups maintain broad retail portfolios and ingredient supply capabilities; their strategies show the value of vertical integration—both in price stability and in faster product innovation cycles.
-
European Bakery Group and other regional players: Smaller groups retain competitive advantage through local freshness, channel intimacy and tailored SKUs that large players find hard to replicate at margin. Our go‑to‑market playbooks show when to partner, acquire or compete with these specialists.
Strategic implications and recommended actions for 2026
-
Prioritise procurement resilience: Establish multi‑tier sourcing, increase indexed procurement contracts and model working capital impacts under 3–5 commodity scenarios. The report provides procurement templates and KPI dashboards that tie contract terms to margin outcomes.
-
Accelerate packaging redesign with compliance gateways: Treat PPWR readiness as a cross‑functional programme—product development, procurement and packaging engineering must align on materials choices, lead times and supplier qualification. We include a phased implementation schedule that minimises SKU disruption.
-
Reassess channel economics: Use our channel‑specific margin models to reallocate commercial investment—promotions, co‑op funds, and listing spend—to formats with durable margins in 2026 and 2027. The report quantifies break‑even points for bake‑off investments and frozen network roll‑outs.
-
Targeted M&A and partnerships: Seek tuck‑ins that bring capacity in high‑growth convenience segments or that close logistical gaps in key corridors. Our M&A screening matrix ranks targets by strategic fit, scale synergies and integration complexity.
-
Embed compliance and labelling as product differentiators: Turn regulatory changes into consumer‑facing advantages (e.g., transparent fortification messaging, clear allergen communication), rather than merely a cost of compliance. The report offers sample communication frameworks and costed labelling templates.
What’s inside the full PW Consulting report (practical modules)
-
Market sizing and forecast models (2020–2032) with downloadable model files and scenario toggles.
-
Channel and format playbooks—commercial and operational KPIs to run pilots, scale successful formats and shift trade investments.
-
Supply chain stress tests linking wheat price bands, freight and energy to margin scenarios and liquidity needs.
-
Regulatory impact matrix (PPWR, UK fortification, EU labelling) and an implementation checklist with cost ranges and timelines.
-
Competitive heatmaps and company profiles with M&A target screening and value capture cases.
-
Pricing and promotion optimization toolkit together with private‑label benchmarking and recommended tender structures for 2026 supply agreements.
-
Operational annexes—plant capex sizing, labour optimisation templates, and packaging sourcing playbooks (including recycled‑content supplier directory).
Methodology and data transparency
Our base‑year market sizing combines company reported revenues, trade statistics and primary interviews across retailers, manufacturers and distributors. Forecasts are produced using a bottom‑up SKU modelling approach cross‑checked with top‑down macro drivers and validated through scenario analysis. To preserve competitive sensitivity while enabling executive action, we provide the full dataset and replication models to subscribers; the public summary intentionally omits granular segment and regional tabulations to ensure integrity of commercial intelligence.
Next steps
For boards, executive teams and investors preparing 2026 plans, the full PW Consulting European Bread Market report is engineered to convert macro trends into executable initiatives. The public briefing above highlights the principal strategic takeaways—subscribe to access the complete datasets, downloadable forecasting models, and the tactical annexes described. PW Consulting stands ready to support bespoke scenario modelling, carve‑out due diligence or integration planning workshops to accelerate your 2026 decisions.
For detailed analysis of this topic, please visit the official page: European Bread Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Night Vision Monocular Market to Expand from USD 750 Million in 2025 to USD 1,142.7 Million by 2032 at a 6.2% CAGR
By pmarketresearch, 2026-07-13
Night Vision Monocular Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest Night Vision Monocular Market report (base year 2025) delivers a forward-looking intelligence package designed to inform high-stakes decisions in 2026. The industry has moved from an estimated USD 565.0 million in 2020 to USD 750.0 million in 2025 and is projected to expand further to roughly USD 1,142.7 million by 2032. That trajectory — underpinned by an embedded CAGR of 6.2% across the 2026–2032 forecast horizon — creates both opportunity and complexity for manufacturers, suppliers, distributors and institutional buyers. This release functions as a strategic “teaser”: we present the analytical scaffolding, practical playbooks and implications you need to act, while holding back the full, granular segment matrices to encourage direct access to the full report and dataset.
Night Vision Monocular Market
Why this report matters for 2026 planning
-
Capital allocation and R&D prioritization — With a clear market growth pathway to 2032, our scenario-based analysis helps executives determine which technology bets (digital, thermal, fusion, and intensified imaging) offer the best risk/reward given regulatory and supply constraints.
Night Vision Monocular Market -
Supply-chain resilience — We translate raw-material and component stress signals into practical mitigation levers, from dual-sourcing and nearshoring to inventory/capacity playbooks calibrated for the monocular product cycle.
Night Vision Monocular Market -
Go-to-market segmentation — We provide playbooks for channel mix optimization (direct, distribution, OEM partnerships and aftermarket services), enabling you to capture value across premium defense tenders and stabilized consumer price bands.
-
M&A and partnership targeting — Our competitive mapping and concentration analysis identify the pockets of consolidation and partner candidates where strategic acquisition or JV can accelerate capability or market entry.
-
Regulatory compliance and export strategy — We flag jurisdictional constraints and model defensive actions for companies exposed to ITAR and trade-policy shifts.
What’s inside (practical, operational content)
-
Market sizing and validated topline trajectory from 2020–2025 and forward forecasts through 2032, with scenario variants for macroeconomic and technology shocks.
-
Technology deep-dive: architecture-level assessments of image intensifier systems, digital CMOS/low-light sensors, thermal modules, and hybrid/thermal-fusion approaches — each evaluated for cost, integration complexity and upgrade path.
-
Supplier and component scorecards: risk-tiered lists, lead-time analytics, and negotiated sourcing frameworks built for real-world procurement teams.
-
Commercial playbooks: segmented go-to-market strategies, pricing ladders and channel incentives tailored for civilian, law-enforcement and defense end users.
-
Regulatory and compliance matrix: actionable checklists for ITAR, trade tariffs and export licensing, with recommended legal and operational controls.
-
Financial models and valuation templates: unit-economics models, margin stress-tests, and M&A valuation frameworks you can apply directly to deals and internal investment cases.
-
Implementation toolkits: supplier RFx templates, product road-mapping sheets, and post-acquisition integration blueprints for accelerating time-to-value.
Competitive landscape — who matters and why
The market is meaningfully concentrated: the top three firms account for a material share of industry revenues and the top five firms consolidate an even larger portion of value — a dynamic that favors scale in manufacturing, distribution and R&D. Against that backdrop, our report profiles the companies shaping product and distribution dynamics:
-
ATN Corp (Southfield, MI, USA) — A leading producer of digital and thermal monoculars with strong civilian and institutional channels; recent product updates indicate continued investment in Gen 3+ optical enhancements ( https://www.atncorp.com/).
-
Bushnell (Overland Park, KS, USA) — A long-standing consumer brand focused on accessible digital and Gen 1 systems for outdoor recreation ( https://www.bushnell.com/).
-
Teledyne FLIR (Wilsonville, OR, USA) — A thermal specialist with scouting and surveillance solutions that set performance benchmarks and platform integration standards ( https://www.flir.com/).
-
Pulsar / Yukon Advanced Optics (Moldova / Lithuania operations) — Aggressive in feature-rich digital and fusion models aimed at hunters and advanced consumers ( https://www.pulsar-vision.com/).
-
SIONYX (Bedford, MA, USA) — Innovator in color digital low-light imaging, relevant for outdoor enthusiasts and niche surveillance applications ( https://www.sionyx.com/).
-
Armasight (TNVC, Oceanside, CA, USA) — Provider of Gen 2+/Gen 3 intensifier monoculars positioned toward tactical and professional users ( https://www.armasight.com/).
-
InfiRay / Guide Sensmart (Yantai, China) — A value-oriented thermal fusion supplier with aggressive integration roadmaps ( https://www.infiray.com/).
-
AGM Global Vision (Bethesda, MD, USA) — Diverse portfolio across digital and thermal offerings, active in both commercial and professional segments ( https://www.agmglobalvision.com/).
Recent product and go-to-market moves — such as SIONYX’s late-2025 Aurora Pro Black Edition, Pulsar’s mid-2025 thermal-fusion Forward F455S with Wi-Fi streaming, ATN’s Gen 3+ PS36-3 update, and Teledyne FLIR’s SHOT Show demo of extended-battery Scout TK models — illustrate an industry that is simultaneously improving core performance and layering connectivity and usability features. These developments intensify differentiation but also raise component and regulatory complexity for market entrants.
Regulatory, raw-material and pricing headwinds — what keeps procurement awake
-
Export controls (ITAR) — High-performance Gen 3 tubes, and systems that incorporate them, are subject to strict export controls. Organizations must maintain robust licensing and partner-vetting programs for cross-border distribution.
-
Sensor and semiconductor supply — Gallium-related shortages elevated digital sensor input costs materially in recent cycles; procurement and product teams should assume elevated component pricing volatility in short- to mid-term windows.
-
Trade policy and tariffs — Recent tariffs on certain foreign-sourced thermal components materially change landed costs and supplier selection criteria; nearshoring and tariff-mitigation strategies are now core procurement levers.
-
Manufacturing lead times — High-performance image intensifier tubes and manually processed phosphor screens can face multi-month lead times; companies must plan product roadmaps against component availability profiles.
-
Consumer pricing stabilization — At the retail layer, digital consumer monoculars are trading in a stable mid-market band, compressing some volume-led growth opportunities while opening service and software monetization potential.
Priority moves for 2026 — actionable recommendations
-
Establish strategic dual-sourcing with qualification corridors. Prioritize alternate suppliers for critical chips and thermal modules, with contracted minimums and option clauses to stabilize lead times and pricing.
-
Design modular product families. Break systems into replaceable optical, sensor and power modules to accelerate upgrades and reduce time-to-market amid component scarcity.
-
Invest in certification and export compliance capacity. An internal export-control cell will reduce bid friction for defense contracts and unlock approved-export channels faster than ad-hoc outsourcing.
-
Pursue selective bolt-on acquisitions. Target sensor specialists or regional manufacturing assets that shorten supply chains and increase margin resilience.
-
Monetize software and connectivity. As devices add streaming and analytics, create subscription or data-service bundles to offset hardware margin pressure.
-
Adopt a dynamic pricing and channel incentive strategy. Use demand-sensing and inventory-linked price ladders to defend ASPs during component-cost shifts.
How to use the full report
This preview covers the strategic framing and critical implications you need to shape 2026 choices. The full PW Consulting report includes the complete, verifiable datasets, regional and application segmentation, technology-specific market splits, downloadable financial models and supplier scorecards. Those granular elements are gated to ensure the integrity of our datasets and to enable tailored advisory support — access to the complete package will allow your team to run “what-if” scenarios for specific product lines, procurement commitments and M&A targets using the precise segment-level matrices that inform valuation and planning.
To obtain the complete report, Excel models and a briefing with our senior Night Vision practice leads, visit the PW Consulting research portal or contact our client services team. If you are preparing a 2026 strategic plan, now is the window to secure supplier options, finalize product roadmaps and lock in compliance measures before mid-year procurement cycles begin.
PW Consulting — Night Vision Monocular Market Practice. Our research and advisory services combine market-scale forecasting, hands-on procurement frameworks and deal execution support for leaders that must convert market growth into durable advantage.
For detailed analysis of this topic, please visit the official page: Night Vision Monocular Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Belt Tensioner Market to Rise from USD 1,609.85 Million in 2025 to USD 2,434.10 Million by 2032 at a 6.08% CAGR
By pmarketresearch, 2026-07-13
PW Consulting Releases Strategic Brief: Industrial Belt Tensioner Market Outlook 2026 — Actionable Roadmap for Executive Decision-Making
Executive summary
PW Consulting today publishes a strategic briefing drawn from our upcoming Industrial Belt Tensioner Market report (base year 2025; historical window 2020–2025; forecast horizon 2026–2032). The market finished 2025 at approximately USD 1,610 Million and enters the 2026 planning window with momentum consistent with a mid-single-digit compound annual growth trajectory (CAGR 2026–2032: 6.08%). Our forecast model projects the market to re-accelerate over the medium term, reaching a multi-billion dollar scale by the end of the planning horizon. For 2026 specifically, the market path implies near-term demand expansion that will require executives to make targeted product, supply chain, and commercial decisions in Q1–Q2 to capture outsized share.
Industrial Belt Tensioner Market
Why this briefing matters for 2026 strategic choices
- Market timing: With baseline market scale set in 2025 and a 6.08% CAGR baked into our central scenario, 2026 acts as an inflection year where commercial investments and operational shifts begin to compound returns through 2032.
- Cost and supply volatility: Raw-material volatility—particularly in natural rubber and steel—has moved within a wide band in recent years (annual swings of 20–35% have been observed), creating margin pressure and forcing re-engineering of sourcing strategies.
- Regulatory pressure and product differentiation: Updated EU emissions and industrial efficiency standards introduced in 2025 accelerate buyer preference toward energy-efficient and low-emissions drive systems, changing specification criteria for belt tensioners and increasing the importance of lifecycle energy metrics.
- Competitive structure: The market displays moderate concentration among the largest incumbents, producing both risk and opportunity: nimble players can pursue niche specialization, while larger firms can leverage scale to integrate upstream or expand aftermarket service offerings.
What the full report delivers — practical, implementation-ready content
Our report is designed as an executive-to-execution toolkit for 2026 planning. Rather than generic market commentary, clients receive decision-ready assets that translate forecast signals into capital, commercial, and product actions:
Industrial Belt Tensioner Market
- Proprietary forecast model (2026–2032) with scenario toggles for demand elasticity, raw-material price shocks, and regulatory stringency — enabling rapid re-run of ROI on proposed investments.
- Supplier risk matrix and hedging playbook that maps component-level exposures to procurement levers (long-term contracts, multi-source qualification, nearshoring thresholds).
- Pricing-sensitivity and margin-impact simulator to evaluate value-based pricing, indexation clauses, and cost-pass-through strategies under realistic procurement cycles.
- Go-to-market playbooks for OEM, aftermarket, and industrial-distribution channels — including partner economics, inventory policies, and warranty/cost-of-ownership arguments tailored to industrial buyers.
- Product and R&D prioritization framework aligning design choices (e.g., automatic vs. fixed tensioners, sensor-enabled tension monitoring) with targeted customer segments and regulatory requirements.
- M&A and partnership screening filters that identify high-fit targets (sensor suites, aftermarket distributors, regional manufacturing footprints) and produce an integration-value estimate.
- Implementation roadmaps and KPI dashboards to convert strategic choices into board-level deliverables within a 6–18 month window.
To preserve the strategic advantage for clients, the public briefing is intentionally selective: detailed segment-level demand tables, regional and application splits, and deal-by-deal valuation worksheets are reserved for the full report and consulting engagements.
Industrial Belt Tensioner Market
Competitive landscape — positioning and near-term dynamics
The market is served by a mix of global industrials, niche specialists, and regional fabricators. Our competitive analysis highlights how product breadth, engineering depth, aftermarket reach, and service propositions shape strategic options for 2026.
- Gates Corporation (Denver, CO): A broad product portfolio and heavy-duty engineering footprint make Gates a natural scale player in power-transmission systems. Their range enables value capture across OEM and heavy-industrial aftermarket channels; the strategic implication for rivals is to either differentiate on precision/innovation or pursue adjacency through partnerships.
- Fenner Drives (Manheim, PA): Specialization in rotary and linear self-adjusting tensioners positions Fenner to command technical leadership in applications where automated compensation reduces maintenance downtime — a growing procurement criterion for capital-equipment buyers seeking TCO reductions.
- BRECOflex (Eatontown, NJ): Precision-focused manufacturers that serve timing belt and conveyor drive niches can sustain premium positions by emphasizing accuracy, low backlash, and integration for bespoke conveying systems.
- Lovejoy (Timken, Downers Grove, IL): Products that combine elastomeric damping with self-adjustment address vibration-sensitive industrial environments; this composite offering is attractive for buyers prioritizing equipment uptime and reduced bearing failures.
- Dayco (Roseville, MI): Recent product-line expansion and new heavy-duty launches underscore an offensive push into both vehicle-derived industrial markets and severe-duty fleet segments. These moves highlight the ongoing blurring of automotive-grade and industrial-spec components.
- Continental AG (Hanover, Germany) and Bando (Osaka, Japan): Large OEM-oriented suppliers with accessory-drive and auto-tensioning competences. Their investments in precision pulleys and systems-level integration are relevant for manufacturers seeking bundled drive-system solutions.
- SKF (Gothenburg, Sweden): Combines tensioner units with measurement and maintenance tools — an attractive playbook for adding sensor-led aftermarket services and predictive-maintenance offerings.
- B&B Manufacturing (La Porte, IN): ISO-certified customizers and stock producers fill the regional and niche-application gaps, serving buyers that require tailored form-factors or quick-turn replacement parts.
Industry activity through 2025–2026 shows product expansion and trade-show showcases by established players — a signal that incumbents are prioritizing product breadth and aftermarket engagement. For 2026 planning, competitive posture should be evaluated on three axes: product engineering depth, service-led differentiation, and channel reach.
Strategic imperatives for executives in 2026
- Hedge raw-material exposure now. Given large swings in rubber and steel costs, lock in a portion of critical inputs through multi-year agreements with indexation clauses and develop tested alternatives where feasible.
- Prioritize energy-efficient and compliance-ready product variants. EU regulatory updates and buyer procurement preferences make low-energy-loss designs and verified lifecycle-impact claims a commercial differentiator.
- Invest in aftermarket and service monetization. Sensor-enabled tension monitoring, condition-based spare-part programs, and extended-service contracts increase lifetime customer value and buffer cyclical OEM orders.
- Adopt a two-track R&D portfolio: sustain core mechanical reliability while accelerating modular sensor and connectivity options that enable predictive maintenance and remote diagnostics.
- Target bolt-on acquisitions that expand distribution reach or add sensing/software capabilities rather than scale-only acquisitions — the optimal M&A path for 2026 is capability-led.
- Use scenario-based capital allocation. With projected growth but intermittent year-to-year variance, capital should be staged and tied to trigger events in demand or cost trajectories.
How PW Consulting supports execution
PW Consulting’s report is more than a forecast — it is an execution engine. Deliverables include the forecast model, sensitivity workbooks, a supplier-risk playbook, go-to-market templates, and a prioritized implementation roadmap tailored to your business model. For leadership teams preparing 2026 budgets, our model links investment choices to market-share scenarios and NPV outcomes under multiple macro environments.
Because this briefing is intentionally high-level, details that many executive teams consider mission-critical — including full regional and application-level demand tables, split-by-type revenue matrices, and predefined transaction targets — are accessible only through the full report or a consulting engagement.
Next steps and how to engage
For executives and strategy teams preparing budgets, sourcing strategies, or M&A pipelines for 2026, the PW Consulting Industrial Belt Tensioner Market report is designed to convert market intelligence into boardroom-ready decisions. To request the full report, scenario toolkits, or a tailored briefing for your executive committee, contact PW Consulting. Our teams are scheduling interactive workshops to run your 2026 plan through the model and deliver an actionable 6–18 month implementation agenda.
PW Consulting — translating market foresight into strategic advantage for the industrial drive systems value chain.
For detailed analysis of this topic, please visit the official page: Industrial Belt Tensioner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Si OLED Microdisplay Market to Surge from USD 1,492.45 Million in 2025 to USD 9,289.46 Million by 2032 at a 29.85% CAGR
By pmarketresearch, 2026-07-13
Si‑OLED Microdisplay Market: Strategic Imperatives for 2026 Decision‑Makers
PW Consulting’s latest Si‑OLED Microdisplay Market study (base year 2025; historical period 2020–2025; forecast 2026–2032) surfaces a decisive inflection for near‑eye display ecosystems. Our proprietary market model — expressed in USD Million — shows the Si‑OLED market accelerating from the low‑billion dollar range in 2025 to a multi‑billion sector by the end of the forecast, underpinned by a compound annual growth rate of 29.85% across 2026–2032. For executives making capex, partnership, M&A and product roadmap decisions this year, the pace and concentration of growth create both opportunity and risk: first mover scale matters, but so does precision in technical differentiation and supply chain design.
Si Oled Microdisplay Market
Why this report matters in 2026
-
Actionable timing: The near‑term surge in demand for silicon‑backplane OLED microdisplays (Si‑OLED / OLEDoS) compresses typical product development and qualification cycles. Our analysis identifies the time windows in which investments in capacity, optics partnerships and standards compliance must be executed to capture premium segments.
Si Oled Microdisplay Market -
Capital efficiency vs. speed to market: With three firms controlling a large share of the market and the top five commanding over four‑fifths of revenue, scale advantages are material. The report quantifies the trade‑offs between building greenfield fabs, upgrading lines, or choosing fabless/licensing models, and provides financial templates to stress‑test those choices under conservative and aggressive adoption scenarios.
Si Oled Microdisplay Market -
Risk‑aware commercialization: Regulatory, defense procurement, and IP dynamics are evolving rapidly. The study integrates scenario planning for export controls, ITAR compliance and large defence awards so commercial leaders can align sales channels and contractual clauses for high‑value customers.
What the report delivers — practical, board‑ready deliverables
-
Market model with transparent assumptions: Historical reconciliation (2020–2025) and a detailed forecast (2026–2032) in USD Million, including sensitivity tables you can drop into your financial planning tools.
-
Vendor assessment framework: Comparative scorecards across technology, capacity, quality, supply chain resilience and commercial readiness. Each scorecard is designed for rapid customization during partner selection or supplier audits.
-
Go‑to‑market playbooks: Channel strategies and pricing architectures tailored for enterprise/defense, industrial/medical and AR/VR consumer segments, with practical negotiation levers and sample contract terms.
-
Technology and IP roadmap: Evaluation of silicon‑backplane approaches, pixel architectures, high‑brightness/tandem OLED strategies, and low‑power drive techniques — and guidance on where to place R&D bets to preserve product differentiation for the next three product generations.
-
Supply chain & capex planning tools: Factory ramp models, equipment sourcing roadmaps, and an input‑output matrix for component criticality (CMOS backplanes, OLED process tooling, optics modules), with recommended mitigation strategies.
-
Executive briefings & investor materials: Board slide templates and a one‑page investment thesis for use in fundraising, stakeholder updates, and M&A diligence.
-
Methodology appendix: Full disclosure of sources, base year (2025) normalization procedures, and forecasting techniques so in‑house analysts can reproduce and extend our work.
Competitive landscape — the companies that shape outcomes
The Si‑OLED segment is characterized by a mix of long‑established optics and semiconductor incumbents, specialist microdisplay houses, and vertically integrated display majors. Key firms profiled in the report include:
-
Sony Semiconductor Solutions Corporation (Japan) : A leading supplier of high‑resolution OLEDoS products, Sony marries OLED stacks to mature silicon backplane expertise. Its SKUs range from FHD to 4K density options, and its engineering focus on pixel miniaturization and peak luminance positions it as a premium systems supplier for high‑end AR/VR optics.
-
eMagin Corporation (USA) : A U.S. pure‑play with cleanroom production, eMagin emphasizes bright, rugged devices targeted at defense and industrial applications. ITAR compliance and a track record in fielded military systems make it a partner of choice where sovereign supply chains are required.
-
SeeYA Technology (China) : A recent public entrant that has rapidly scaled silicon‑OLED manufacturing. Its IPO and stated capacity expansion underscore the strategic acceleration of volume production in Asia and provide a bellwether for pricing and availability in consumer‑oriented near‑eye systems.
-
Kopin Corporation (USA) : A diversified microdisplay supplier with extensive defense field experience and a portfolio approach to display technology, Kopin offers customization and integration expertise that is valuable to system integrators.
-
BOE Technology Group (China) : As a major panel and display manufacturer, BOE brings process scale, tandem OLED techniques and integration pathways that can depress cost curves if industrialization continues at pace.
-
MICROOLED (France), Seiko Epson (Japan), OLiGHTEK (China), OLEDWorks (USA) : Specialist vendors offering high‑contrast modules, optical engines and integrated modules for targeted segments such as smart glasses, medical optics and outdoor optics. Each company’s strategic value differs by appetite for systems integration versus component supply.
Recent inflections and what they mean
-
Public markets and capacity signals: SeeYA Technology’s IPO and announced reinvestment into silicon‑OLED production represent a watershed for scale in Asia. For Western OEMs and suppliers, this should trigger an immediate re‑examination of sourcing strategies and contractual protections around yield and quality.
-
Prototype breakthroughs: Research organizations advancing ultra‑high‑resolution or ultra‑high‑brightness prototypes (including sub‑inch, multi‑megapixel demonstrations and single‑color ultra‑nits devices) indicate the technical ceiling for near‑term product differentiation. These prototypes compress development timelines for consumer AR optics and raise the bar for power budgets in wearable systems.
-
Defense procurement acceleration: Large awards and supplier selections for head‑mounted systems in 2026 signal a multi‑year revenue tail for qualified suppliers. However, defense demand comes with compliance overhead and long certification cycles, so commercial players must weigh sales opportunity against programmatic cost and IP containment requirements.
Strategic implications for 2026 corporate decision‑making
-
Prioritize truly differentiated tech or scale: At the observed market concentration levels (top‑three players capture the majority market share, and the top five approach four‑fifths dominance), mid‑sized players must choose between investing to reach scale or focusing on niche differentiation (optics integration, low‑power drive, specialized form factors).
-
Lock down critical inputs early: Equipment for silicon backplane processing, OLED deposition tooling, and precision optics are long lead‑time items. Advance procurement and multi‑sourcing contracts reduce ramp risk and preserve margin during SKU transitions.
-
Design for regulatory realities: Defense sales require ITAR/sovereign capability. Even commercial programs must anticipate export controls and localized content rules. The report includes compliance checklists and supplier‑onboarding templates to accelerate qualification.
-
Use modular integration to shorten customer lead times: Partnering with module and optical engine specialists allows faster system integration and creates service revenue opportunities, while reducing capital intensity for display fabs.
-
Adopt scenario‑based investment gates: We recommend a two‑stage investment cadence for wafer fabs and toolsets: an initial proof‑of‑capability tranche followed by a scaled capex trigger tied to volume and yield milestones. Our financial models demonstrate how this reduces downside while preserving upside participation.
-
Prepare for M&A arbitrage: With rapid consolidation signals, acquirers can secure technology or capacity advantages by targeting specialized suppliers or optics integrators. The report provides a prioritized M&A target list and valuation ranges tied to revenue and technology readiness levels.
How to use the report in the next 90 days
-
Run the report’s stress scenarios against your product roadmap and update procurement lead times in your ERP or PLM systems.
-
Engage with our vendor scorecards to qualify 2–3 supply partners for NPI trials; use the included RFP templates to accelerate negotiations.
-
Initiate a short‑form board briefing that links chosen investment gates to the report’s financial templates and risk matrices.
-
Schedule a due diligence deep‑dive if you are exploring M&A or JV activity; the report’s annex contains a ready‑to‑use diligence checklist tailored to Si‑OLED technology and manufacturing.
PW Consulting’s Si‑OLED Microdisplay Market report is intentionally rich in modeling, playbooks and executable templates — but follows a “trailer” approach: the published briefing above demonstrates analytical depth while withholding the full set of segment tables, vendor scorecards and downloadable financial models. For the complete dataset, customizable templates, and to arrange a strategy workshop tailored to your organisation’s risk posture and growth ambitions, please visit our Si‑OLED Microdisplay Market report landing page or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Si Oled Microdisplay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Zellweger Spectrum Disorders Market Poised to Expand at a 6.72% CAGR Through 2032
By pmarketresearch, 2026-07-13
Zellweger Spectrum Disorders Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
Executive summary
PW Consulting today releases a strategic industry brief focused on the Zellweger Spectrum Disorders (ZSD) market, providing executive teams with a compact, decision-ready view of commercial, clinical, diagnostic, and R&D dynamics that will shape 2026. Built on an exhaustive review of primary and secondary sources, the brief synthesizes market-level projections, competitive positioning, regulatory and reimbursement signals, and near-term scientific inflection points to inform corporate strategy, portfolio prioritization, and partnership decisions.
Zellweger Spectrum Disorders Market
Market snapshot: trajectory and what it means for 2026 planning
The ZSD ecosystem remains a small, high-value specialty market that is growing steadily. Our base-year estimate for 2025 places the total market at approximately USD 313 million (revenue unit: Million), with the market expected to expand at a compound annual growth rate (CAGR) of 6.72% over the 2026–2032 forecast window. Under PW Consulting’s baseline scenario, the market progresses to roughly USD 493 million by 2032 driven by incremental commercialization of supportive therapies, expanded diagnostic throughput, and modest uptake of ancillary clinical services.
Zellweger Spectrum Disorders Market
For executives, three implications are immediate:
Zellweger Spectrum Disorders Market
- Scale matters: absolute market size will remain limited relative to larger therapeutic areas, so strategies must prioritize high-margin, high-efficacy value propositions or platform plays that extend beyond ZSD alone.
- Growth is durable but incremental: the CAGR signals steady opportunity—sufficient to support targeted investment—yet the time horizon for sizeable returns is multi-year and requires disciplined resource allocation and partnerships.
- Concentration creates strategic leverage points: market share is clustered among a small number of specialized players, creating both entry barriers and potential M&A or alliance opportunities for companies seeking rapid access to capabilities or distribution.
What the report delivers — operational intelligence, not just numbers
PW Consulting’s ZSD market brief is designed as a pragmatic playbook. Rather than a catalogue of raw segmentation tables, the report translates market intelligence into executable options for business leaders. Key deliverables include:
- Market sizing and scenario models — top-line and sensitivity runs that reflect base, conservative, and upside adoption pathways through 2032.
- Commercial playbooks — go-to-market blueprints for specialty pharmaceuticals and diagnostic service providers, including target customer archetypes, channel strategies, and pricing levers.
- Reimbursement and HTA roadmaps — country-agnostic frameworks to prioritize payer engagement, dossier development, and real-world evidence generation in support of value claims.
- Diagnostics and testing strategy — segmentation of diagnostic use-cases (newborn screening, confirmatory panels, carrier screening, and diagnostic escalation), with recommended business models for laboratory services and instrument providers.
- Pipeline and technology watch — prioritized trackers for gene therapy, gene editing, small molecules, and supportive care technologies including timelines and critical clinical inflection points.
- Patient journey and unmet needs mapping — actionable interventions across the clinical pathway to improve adherence, diagnosis-to-treatment timelines, and patient outcomes.
Competitive landscape — who matters and why
The ZSD ecosystem comprises distinct but complementary participant groups: specialty pharma with the only approved adjunctive therapy for hepatic manifestations, genetic testing laboratories, and diagnostic/instrument suppliers. PW Consulting’s brief profiles the leading organizations that will shape market access, diagnostic throughput, and clinical practice in 2026 and beyond:
- Mirum Pharmaceuticals, Inc. — As the commercial steward of CHOLBAM (cholic acid), Mirum anchors the pharmacologic management of liver-dominant manifestations. Continued commercial availability and growth momentum for CHOLBAM reinforce its role as the standard adjunctive option for eligible patients.
- Invitae Corporation and GeneDx, LLC — These genetic testing leaders provide the molecular diagnostic panels and interpretive services that underpin case identification and clinical decision-making. Their scale and payer relationships influence diagnosis rates and downstream therapy uptake.
- PerkinElmer and Thermo Fisher Scientific — Instrumentation, reagents, and laboratory workflows supplied by these vendors enable high-throughput biochemical and genetic testing, making them strategic partners for laboratories seeking scale or improved turn-around times.
- CENTOGENE N.V. — With a focus on rare hereditary disorders, CENTOGENE’s diagnostic and registry capabilities offer a model for combining testing services with patient identification and natural history data generation.
Collectively, market concentration favors incumbent specialization while leaving room for disruptive entrants that can deliver differentiated clinical benefits, cheaper and faster diagnostics, or platform capabilities that span multiple rare disease indications.
Recent scientific and regulatory inflection points
Two developments in late 2025 and early 2026 are particularly material for strategy:
- Clinical practice reaffirmation: Clinical guideline updates in late 2025 have reconfirmed cholic acid (CHOLBAM) as an approved adjunctive treatment for liver manifestations in peroxisomal disorders, providing continued clarity for prescribers and payers and supporting commercial continuity.
- Preclinical technological breakthrough: In April 2026, a high-profile academic group reported successful base editing correction of a common PEX1 mutation in a murine ZSD model, restoring peroxisome function and reversing liver pathology. While preclinical, this result highlights the real potential—and the scientific uncertainty—around gene-editing strategies that aim to address the genetic root cause.
For corporate strategists, these signals imply a bifurcated near-term focus: defend and optimize current supportive standards of care while selectively investing in or monitoring disease-modifying approaches that, if translated to humans, would change the market’s fundamentals.
Regulatory, reimbursement and clinical realities — constraints and opportunities
Regulatory and reimbursement factors shape feasible business models today. Important contextual points include:
- CHOLBAM’s regulatory status as the first approved adjunctive treatment for peroxisomal disorders continues to anchor pharmacologic management for hepatic presentations, but no disease-modifying therapies addressing extrahepatic manifestations have demonstrated safety and effectiveness as of 2026.
- Clinical management remains largely supportive for many patients, including vitamin supplementation and device-based interventions for sensory deficits; these services represent durable, ancillary revenue pools and clinical touchpoints for care coordination models.
- Incidence remains rare, with population pockets of higher prevalence in specific geographies, which has implications for regional trial design, newborn screening initiatives, and laboratory network planning.
Strategic recommendations for 2026 executives
PW Consulting’s analysis yields five priority actions we recommend for companies aligning resources in 2026:
- Prioritize diagnostic scale: Investments that reduce time-to-diagnosis (lab automation, payer-friendly testing bundles, and clinician education) will have outsized impact on therapy uptake and patient outcomes.
- Protect and extend current standards: For incumbents with marketed therapies, double down on real-world evidence and targeted outcomes studies that reinforce payer value propositions, especially for hepatic outcomes where approved therapy exists.
- Build optionality on advanced therapeutics: Maintain a monitored investment posture in gene-editing and gene-therapy approaches—through partnerships, option agreements, or early-stage equity—while preparing commercial frameworks for a rapid pivot should clinical translation succeed.
- Design payer-first reimbursement strategies: Map reimbursement pathways now, invest in health economics models, and pilot risk-sharing agreements in select systems to accelerate coverage decisions post-launch.
- Explore consolidation and capability buys: Given the market’s concentration, M&A or licensing to acquire diagnostic capacity, patient registries, or market access expertise can shorten time-to-scale more efficiently than greenfield builds.
Why PW Consulting’s brief is strategically unique
Our ZSD market brief is intentionally structured as a decision tool, not an academic compendium. It combines quantitative market models with qualitative competitive and regulatory intelligence and translates these into executable options for business leaders—go-to-market checklists, payer engagement frameworks, and R&D prioritization matrices. Crucially, the brief balances transparency with commercial discretion: it demonstrates the methodology and directional outcomes while reserving granular segmented metrics for clients and report subscribers who require the underlying tables to execute tactical deployments.
Next steps and how to access the full intelligence
PW Consulting’s ZSD brief is intended to inform 2026 strategic planning cycles. For executive teams interested in operationalizing the findings, the next step is a tailored briefing where our analysts will walk through scenario runs, share constrained segmentation outputs, and co-design a 12–18 month action plan aligned to your capabilities.
- If you are a commercial strategy, corporate development, or R&D leader evaluating ZSD exposure, request a tailored walk-through to convert insights into a prioritized roadmap.
- For diagnostics and laboratory executives, our briefing can de-risk decisions about lab expansion, partnership models, and payer contracting.
- Investors and alliance teams can use the brief’s risk/return matrices to identify near-term targets for partnership or acquisition.
Closing takeaways
Zellweger Spectrum Disorders present a classic specialty market paradox: limited patient numbers but meaningful clinical and commercial value for organizations that execute with focus. PW Consulting’s 2026 brief equips leaders with the macro sizing, validated market scenarios, and tactical playbooks necessary to make calibrated bets—whether defending incumbent assets, scaling diagnostic reach, or selectively investing in transformative science. To access the full methodology, segmented analyses, and executable annexes, please visit our report landing page or contact PW Consulting for a brief demo.
For detailed analysis of this topic, please visit the official page: Zellweger Spectrum Disorders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com