

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Outdoor Warning and Mass Notification Systems Market Poised to Reach USD 4,584.88 Million by 2032

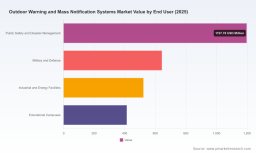
Outdoor Warning and Mass Notification Systems Market: Strategic Briefing for 2026 Decision-Makers
As organizations and public authorities reassess resilience investments in the wake of increasingly complex hazards, the outdoor warning and mass notification systems market is transitioning from point solutions to integrated, policy-driven ecosystems. PW Consulting’s latest market research — based on a 2025 base year and a forecast through 2032 — quantifies this transition and translates it into pragmatic decision levers. Our analysis shows that the global market expanded from USD 1,940.5 Million in 2020 to USD 2,778.0 Million in 2025 and is projected to reach USD 4,584.88 Million by 2032, representing a compound annual growth rate (CAGR) of 7.42% over the 2026–2032 forecast period. This briefing synthesizes the report’s strategic value for 2026 procurement, technology, and program design choices — without disclosing the granular splits that are available in the full report.
Outdoor Warning And Mass Notification Systems Market
Why this matters in 2026
-
Funding windows and regulation are aligning. Government grant programs and legislative initiatives are creating momentary accelerants for modernization programs; program managers who plan now will be best positioned to capture funds and de-risk rollouts.
Outdoor Warning And Mass Notification Systems Market -
Priorities have shifted from pure coverage to integration and intelligence. Agencies increasingly demand systems that support polygon-based alerting, IPAWS compatibility, and on-premise architectures for data sovereignty and operational continuity.
Outdoor Warning And Mass Notification Systems Market -
Vendor consolidation and product lifecycle events are changing procurement dynamics. Buyers face both the opportunity of integrated platforms and the complexity of managing legacy obsolescence.
Market trajectory and what it means for buyers
The market’s steady growth through 2025 and the projected acceleration through 2032 at a 7.42% CAGR reflect multiple converging drivers: capital allocation to civic resilience, regulatory mandates for interoperable alerting, and technology upgrades that enable intelligible, geo-targeted outdoor voice and siren systems. For practitioners this translates into three practical implications:
-
Timing matters. 2026 is a strategic inflection point: projects initiated this year have the best chance to align with available funding cycles and to leverage next-generation standards being embedded by regulators.
-
Integration is non-negotiable. Solutions must support multi-channel orchestration (IP, cellular, siren, giant-voice) and interface cleanly with national alerting architectures to avoid stranded investments.
-
Lifecycle planning beats reactive replacement. With several suppliers updating product roadmaps and issuing obsolescence notices, procuring agencies should adopt vendor-agnostic migration plans that prioritize backwards compatibility, encryption, and modular upgrades.
Regulatory and funding context shaping 2026 decisions
-
Grant and legislative activity has accelerated the market: for example, a major federal grant program earmarked USD 40 million for next-generation warning systems in fiscal 2025, and the SIREN Act introduced in 2026 proposes additional grant streams for siren modernization and sensor integration. These are not one-off events — they alter the sample set of fundable scope items and create windows for larger projects.
-
Standards and platform updates matter operationally: IPAWS enhancements and polygon-based alerting mandates now appear explicitly in procurement specifications, requiring systems to support finer geospatial targeting and standardized message formats.
-
Data sovereignty and cybersecurity requirements are driving on-premise deployment preferences for critical infrastructure and government agencies. Compliance frameworks (e.g., FISMA-like controls) affect architecture choices and total cost of ownership.
Technology and deployment trends — what to prioritize
-
Voice intelligibility and long-range acoustic performance remain core differentiators. Modern outdoor voice systems and long-range acoustic devices now combine power with signal processing to achieve higher message clarity in urban and complex acoustic environments.
-
Networked, encrypted siren stations are replacing isolated mechanical units. Buyers should demand end-to-end encryption, robust remote diagnostics, and the ability to perform secure group updates to avoid field rework.
-
Hybrid architectures — on-premise orchestration with cloud-enabled analytics — offer the best balance between control and capability. They allow local authorities to maintain sovereignty while tapping centralized command-and-control improvements and remote support.
-
Sensor integration and situational triggers (weather feeds, seismic sensors, industrial detectors) are increasingly being bundled into end-to-end offers, shifting value from standalone sirens to ecosystem-enabled decisioning.
Competitive landscape — read the signals, not just the logos
The market exhibits moderate concentration: the top three vendors account for a meaningful share, and the top five increase that footprint further. However, the vendor field is diverse, spanning specialist siren manufacturers, acoustic device suppliers, large industrial players, and regional niche providers. PW Consulting’s report profiles strategic behaviors and go-to-market postures across this landscape to help buyers and investors identify the right fit for their risk profile and procurement timeline.
-
Specialist acoustic and siren firms continue to lead on product performance and domain-specific innovation. Companies with deep heritage in outdoor voice, networked sirens, and encrypted deployments remain preferred for municipality and defense projects.
-
Large systems integrators and industrial players are extending into mass notification, leveraging existing relationships with critical infrastructure operators to offer bundled services and lifecycle support.
-
Regional manufacturers retain advantages in localized standards, service footprints, and faster deployment cycles for smaller jurisdictions.
Selected recent market cues illustrate the competitive and procurement dynamics that will inform 2026 decisions: notable municipal and county deployments have continued through 2025 and into 2026, specialist vendors have won orders emphasizing vocal clarity and long-range coverage, and major suppliers have issued product-line updates and obsolescence notices that will influence replacement cycles.
What the report delivers — actionable content for program leaders
PW Consulting’s full report is designed as an implementation-ready playbook for 2026. Highlights include:
-
Market sizing and conservative-to-aggressive scenario forecasts (2026–2032) to support business cases and capital planning.
-
A procurement decision framework that maps mission requirements to technology architectures and procurement modalities (capex vs. service models), including vendor shortlists by use-case.
-
Vendor scorecards and comparative matrices that evaluate acoustic performance, integration readiness, cybersecurity posture, service coverage, and lifecycle risks.
-
Deployment playbooks: installation checklists, interoperability test plans, and maintenance schedules aimed at reducing time-to-benefit and operational surprises.
-
Regulatory mapping: analysis of grant eligibility, compliance checkpoints, and message-format requirements tied to federal and international standards.
-
Total cost of ownership (TCO) models and phased-upgrade blueprints to support budget conversations and vendor negotiations.
-
Case studies and supplier sourcing templates derived from recent municipal and county projects to illustrate procurement language and risk mitigation strategies.
To preserve competitive advantage for subscribers and to respect client confidentiality, the report intentionally withholds certain granular regional and application-level splits from this public briefing. These detailed allocations, along with supplier-level financial benchmarking and downloadable procurement templates, are available in the full report.
Practical recommendations for 2026 program sponsors
-
Prioritize integration-first procurements. Solicit requirements that mandate IPAWS compatibility, polygon-targeting, and secure remote management to avoid retrofits.
-
Build migration-aware contracts. Include clauses for firmware update support, parts availability commitments, and orderly end-of-life transitions to mitigate obsolescence risk.
-
Leverage available funding windows. Align project milestones to grant cycles and legislative initiatives; structure deliverables to match funder acceptance criteria.
-
Test for operational performance, not just specifications. Include intelligibility metrics and geo-targeted scenario testing in acceptance criteria.
-
Plan for hybrid architectures. Combine on-premise control with selective cloud services for analytics and remote support while preserving sovereignty where required.
Final perspective
For executives, procurement officers, and resilience planners, 2026 represents a strategic crossroads: the market’s growth trajectory and the policy environment together create a window for durable modernization. PW Consulting’s market forecasting and playbook-style guidance translate the sector’s expansion (from USD 1,940.5 Million in 2020 to a projected USD 4,584.88 Million by 2032 at a 7.42% CAGR for the 2026–2032 period) into concrete choices about architecture, sourcing, and program timing. The full report supplies the granular intelligence — including regional and application breakdowns, vendor financials, and procurement templates — that organizations need to convert this strategic moment into resilient, cost-effective systems.
To access the complete analysis, vendor scorecards, and deployment templates referenced in this briefing, please visit PW Consulting’s report page. Our team is available for briefings and bespoke advisory engagements to adapt the study’s insights to your operational and fiscal constraints.
For detailed analysis of this topic, please visit the official page: Outdoor Warning And Mass Notification Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com