

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Desktop Hypervisor Market to Expand from USD 475.0 Million in 2025 to USD 743.0 Million by 2032 at a 6.61% CAGR — Hosted Hypervisors Lead; North America Tops with USD 200.6M (CR3 82.5%)

Desktop Hypervisor Market: Strategic Imperatives for Enterprise Leaders — PW Consulting Outlook 2026
Executive summary
PW Consulting’s latest market research on the Desktop Hypervisor Market provides a practical, decision‑ready roadmap for CIOs, CTOs, and procurement leaders preparing budgets and platform strategies for 2026 and beyond. Our bottom‑up model anchors to a 2025 baseline and projects a steady expansion through the forecast period 2026–2032 at a compounded annual growth rate (CAGR) of 6.61%. In dollar terms, the market moves from an indicative baseline in 2025 to an expected mid‑high single‑digit uplift year‑over‑year, with the market size reaching roughly USD 743.0 Million by 2032 under our central scenario.
Desktop Hypervisor Market
Two structural signals should guide enterprise planning immediately: first, the market is highly concentrated — the top three vendors account for the vast majority of revenue capture (CR3 ~82.5%), and the top five approach near‑total dominance (CR5 ~91.3%). Second, technology and policy shifts (including vendor licensing changes and new hypervisor entrants targeting specific workloads) are re‑shaping competitive dynamics faster than many IT procurement cycles can adapt. Our report synthesizes these dynamics into actionable frameworks and tools tailored for 2026 decision windows.
Desktop Hypervisor Market
Why this report is strategic for 2026 decisions
-
Stabilized growth trajectory with tactical inflection points — The projected CAGR provides a reliable macro backdrop for capital and operational planning; however, vendor behaviour and platform announcements create short windows where choices made in 2026 materially affect TCO and lock‑in over the following three to five years.
Desktop Hypervisor Market -
Concentration risk and supply‑side leverage — With a small number of vendors commanding the majority of the market, enterprises must design procurement strategies that balance strategic vendor relationships with hedges against pricing and licensing risk.
-
Security and compliance pressure — Industry standards such as NIST SP 800‑125 and PCI DSS virtualization guidance are converging on stricter expectations for hypervisor lifecycle management, logging, and hardening. These are not optional checkboxes; they materially affect architecture choices between hosted and bare‑metal approaches.
Market dynamics that will shape 2026 playbooks
-
Licensing and go‑to‑market adjustments — Recent vendor moves have reset pricing and distribution norms. Enterprises must treat licensing policy as an active variable in vendor selection, not as a sunk cost. Rapid policy changes can create immediate opportunities for cost reduction or unexpected constraints on deployment models.
-
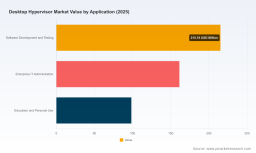
Diversification of workload targets — Desktop hypervisors continue to serve software development and testing, enterprise IT administration, and education/personal use, but we are seeing rising, specialized adoption for unified communications, virtualization of endpoint security agents, and lightweight VDI scenarios at the edge.
-
Hardware dependencies and performance ceilings — Effective desktop virtualization hinges on host hardware capabilities (e.g., CPU virtualization extensions such as Intel VT‑x or AMD‑V, second‑level address translation (SLAT), and adequate memory footprint). Absent these, nested or multi‑VM workloads experience non‑linear degradation. Our operational playbooks spotlight procurement standards that avoid these bottlenecks.
-
Regulatory and audit posture — For PCI‑relevant and other regulated environments, virtualized desktops introduce additional scanning, logging, and segmentation requirements. The report provides prescriptive controls to reduce audit remediation costs and enforceable checklists for operational teams.
Competitive landscape: what enterprises need to know
The competitive set includes established desktop hypervisor vendors and adjacent platform players. Each brings differentiated strengths and tradeoffs that matter to enterprise purchasers.
-
Broadcom (VMware) — VMware’s desktop hypervisor products remain feature‑rich for cross‑platform development and complex testing workflows. Notably, recent policy updates have materially changed the commercial calculus for some use cases, and procurement teams should reevaluate TCO models that were built on prior licensing assumptions.
-
Oracle (VirtualBox) — As a widely used open‑source option, VirtualBox offers a low‑friction path for broad compatibility across host/guest platforms. It is attractive for labs, developer sandboxes, and budget‑constrained deployments, but support SLAs and enterprise‑grade security integrations should be evaluated case‑by‑case.
-
Microsoft (Hyper‑V) — The built‑in hypervisor on mainstream Windows editions reduces deployment complexity for Windows‑centric environments and leverages operating‑system level integration for management and security. Hardware prerequisites (e.g., SLAT and VT‑x/AMD‑V) remain decisive factors for performance and feature enablement.
-
Parallels (Corel) — Parallels Desktop’s optimized support for Apple silicon and Intel Macs addresses the growing heterogeneous endpoint estate. For organizations standardizing on macOS for developer productivity or design workflows, Parallels provides a performance‑oriented, low‑friction option.
-
Citrix Systems — Historically focused on workspace virtualization, Citrix’s capabilities remain relevant where integration into VDI and managed workspace services is a priority. Enterprises should model integration costs against alternative pure desktop hypervisor strategies.
Recent vendor moves and new entrants — implications for procurement
-
Open policy shifts by major vendors can create one‑time windows for renegotiation or refactoring. Our research details how to operationalize vendor policy changes into renegotiation playbooks and migration pilots.
-
New announcements from infrastructure vendors targeting specific workloads (e.g., unified communications) indicate a trend of verticalized hypervisors. These niche entrants can be compelling for specialized workloads but require careful validation against enterprise security and manageability standards.
What’s in the PW Consulting report — practical deliverables
Beyond market sizing and high‑level trends, the report is structured to be directly useful to teams executing on virtualization strategy in 2026:
-
Decision frameworks: vendor short‑listing matrices, risk scorecards, and a procurement timeline template aligned to typical fiscal cycles.
-
TCO and ROI models: downloadable spreadsheets and scenario runs for common migration paths (lift‑and‑shift, phased refactor, hybrid hosted/bare‑metal) that feed into CAPEX/OPEX planning.
-
Security and compliance playbooks: mapping of NIST SP 800‑125 and PCI DSS virtualization guidelines to operational controls, logging standards, and audit evidence artifacts.
-
Hardware compatibility and procurement checklist: minimum host specifications, SLAT and virtualization extension requirements, and guidance for avoiding common bottlenecks when deploying multiple concurrent VMs.
-
Competitive profiles and negotiation levers: vendor posture analysis, feature tradeoff matrices, and recommended contractual clauses to mitigate concentration risk.
-
Use‑case playbooks: prescriptive deployment designs for development/testing labs, enterprise IT administration, remote learning, and niche workloads such as unified communications virtualization.
Practical first steps for 2026
-
Conduct a hardware triage across your endpoint fleet against minimum SLAT/VT‑x/AMD‑V requirements and map remediation costs into the 2026 budget. Failing to address host capability gaps is the most common cause of poor virtualization economics.
-
Revisit vendor licensing models and apply our short‑form renegotiation playbook to any contract expiring within 12–18 months. Policy changes among major suppliers have recalibrated potential savings and risks.
-
Apply our compliance mapping to any use case that touches regulated data. Early alignment to NIST and PCI expectations reduces audit remediation spend and operational downtime.
-
Run a pilot that stresses both performance and security telemetry. Use the KPI set in our report to validate vendor claims across real workloads before a broad rollout.
Conclusion — the strategic inflection is now
As the desktop hypervisor market grows steadily through the forecast horizon, the combination of concentrated vendor power, evolving licensing paradigms, and tighter security/compliance regimes means 2026 is a pivotal year for firms choosing how to virtualize endpoints. PW Consulting’s report translates the market’s macro trajectory and competitive realities into operational tools designed to reduce risk, optimize costs, and accelerate secure deployment.
For teams writing 2026 budgets, designing migration programs, or recalibrating vendor relationships, the report delivers the practical intelligence and decision engines needed to act confidently. To access the proprietary segmentation tables, granular scenario outputs, and the full set of templates and models that underpin our recommendations, please visit our official PW Consulting report page for the Desktop Hypervisor Market.
For detailed analysis of this topic, please visit the official page: Desktop Hypervisor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com