

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Si OLED Microdisplay Market to Surge from USD 1,492.45 Million in 2025 to USD 9,289.46 Million by 2032 at a 29.85% CAGR

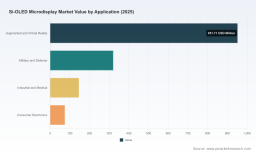
Si‑OLED Microdisplay Market: Strategic Imperatives for 2026 Decision‑Makers
PW Consulting’s latest Si‑OLED Microdisplay Market study (base year 2025; historical period 2020–2025; forecast 2026–2032) surfaces a decisive inflection for near‑eye display ecosystems. Our proprietary market model — expressed in USD Million — shows the Si‑OLED market accelerating from the low‑billion dollar range in 2025 to a multi‑billion sector by the end of the forecast, underpinned by a compound annual growth rate of 29.85% across 2026–2032. For executives making capex, partnership, M&A and product roadmap decisions this year, the pace and concentration of growth create both opportunity and risk: first mover scale matters, but so does precision in technical differentiation and supply chain design.
Si Oled Microdisplay Market
Why this report matters in 2026
-
Actionable timing: The near‑term surge in demand for silicon‑backplane OLED microdisplays (Si‑OLED / OLEDoS) compresses typical product development and qualification cycles. Our analysis identifies the time windows in which investments in capacity, optics partnerships and standards compliance must be executed to capture premium segments.
Si Oled Microdisplay Market -
Capital efficiency vs. speed to market: With three firms controlling a large share of the market and the top five commanding over four‑fifths of revenue, scale advantages are material. The report quantifies the trade‑offs between building greenfield fabs, upgrading lines, or choosing fabless/licensing models, and provides financial templates to stress‑test those choices under conservative and aggressive adoption scenarios.
Si Oled Microdisplay Market -
Risk‑aware commercialization: Regulatory, defense procurement, and IP dynamics are evolving rapidly. The study integrates scenario planning for export controls, ITAR compliance and large defence awards so commercial leaders can align sales channels and contractual clauses for high‑value customers.
What the report delivers — practical, board‑ready deliverables
-
Market model with transparent assumptions: Historical reconciliation (2020–2025) and a detailed forecast (2026–2032) in USD Million, including sensitivity tables you can drop into your financial planning tools.
-
Vendor assessment framework: Comparative scorecards across technology, capacity, quality, supply chain resilience and commercial readiness. Each scorecard is designed for rapid customization during partner selection or supplier audits.
-
Go‑to‑market playbooks: Channel strategies and pricing architectures tailored for enterprise/defense, industrial/medical and AR/VR consumer segments, with practical negotiation levers and sample contract terms.
-
Technology and IP roadmap: Evaluation of silicon‑backplane approaches, pixel architectures, high‑brightness/tandem OLED strategies, and low‑power drive techniques — and guidance on where to place R&D bets to preserve product differentiation for the next three product generations.
-
Supply chain & capex planning tools: Factory ramp models, equipment sourcing roadmaps, and an input‑output matrix for component criticality (CMOS backplanes, OLED process tooling, optics modules), with recommended mitigation strategies.
-
Executive briefings & investor materials: Board slide templates and a one‑page investment thesis for use in fundraising, stakeholder updates, and M&A diligence.
-
Methodology appendix: Full disclosure of sources, base year (2025) normalization procedures, and forecasting techniques so in‑house analysts can reproduce and extend our work.
Competitive landscape — the companies that shape outcomes
The Si‑OLED segment is characterized by a mix of long‑established optics and semiconductor incumbents, specialist microdisplay houses, and vertically integrated display majors. Key firms profiled in the report include:
-
Sony Semiconductor Solutions Corporation (Japan) : A leading supplier of high‑resolution OLEDoS products, Sony marries OLED stacks to mature silicon backplane expertise. Its SKUs range from FHD to 4K density options, and its engineering focus on pixel miniaturization and peak luminance positions it as a premium systems supplier for high‑end AR/VR optics.
-
eMagin Corporation (USA) : A U.S. pure‑play with cleanroom production, eMagin emphasizes bright, rugged devices targeted at defense and industrial applications. ITAR compliance and a track record in fielded military systems make it a partner of choice where sovereign supply chains are required.
-
SeeYA Technology (China) : A recent public entrant that has rapidly scaled silicon‑OLED manufacturing. Its IPO and stated capacity expansion underscore the strategic acceleration of volume production in Asia and provide a bellwether for pricing and availability in consumer‑oriented near‑eye systems.
-
Kopin Corporation (USA) : A diversified microdisplay supplier with extensive defense field experience and a portfolio approach to display technology, Kopin offers customization and integration expertise that is valuable to system integrators.
-
BOE Technology Group (China) : As a major panel and display manufacturer, BOE brings process scale, tandem OLED techniques and integration pathways that can depress cost curves if industrialization continues at pace.
-
MICROOLED (France), Seiko Epson (Japan), OLiGHTEK (China), OLEDWorks (USA) : Specialist vendors offering high‑contrast modules, optical engines and integrated modules for targeted segments such as smart glasses, medical optics and outdoor optics. Each company’s strategic value differs by appetite for systems integration versus component supply.
Recent inflections and what they mean
-
Public markets and capacity signals: SeeYA Technology’s IPO and announced reinvestment into silicon‑OLED production represent a watershed for scale in Asia. For Western OEMs and suppliers, this should trigger an immediate re‑examination of sourcing strategies and contractual protections around yield and quality.
-
Prototype breakthroughs: Research organizations advancing ultra‑high‑resolution or ultra‑high‑brightness prototypes (including sub‑inch, multi‑megapixel demonstrations and single‑color ultra‑nits devices) indicate the technical ceiling for near‑term product differentiation. These prototypes compress development timelines for consumer AR optics and raise the bar for power budgets in wearable systems.
-
Defense procurement acceleration: Large awards and supplier selections for head‑mounted systems in 2026 signal a multi‑year revenue tail for qualified suppliers. However, defense demand comes with compliance overhead and long certification cycles, so commercial players must weigh sales opportunity against programmatic cost and IP containment requirements.
Strategic implications for 2026 corporate decision‑making
-
Prioritize truly differentiated tech or scale: At the observed market concentration levels (top‑three players capture the majority market share, and the top five approach four‑fifths dominance), mid‑sized players must choose between investing to reach scale or focusing on niche differentiation (optics integration, low‑power drive, specialized form factors).
-
Lock down critical inputs early: Equipment for silicon backplane processing, OLED deposition tooling, and precision optics are long lead‑time items. Advance procurement and multi‑sourcing contracts reduce ramp risk and preserve margin during SKU transitions.
-
Design for regulatory realities: Defense sales require ITAR/sovereign capability. Even commercial programs must anticipate export controls and localized content rules. The report includes compliance checklists and supplier‑onboarding templates to accelerate qualification.
-
Use modular integration to shorten customer lead times: Partnering with module and optical engine specialists allows faster system integration and creates service revenue opportunities, while reducing capital intensity for display fabs.
-
Adopt scenario‑based investment gates: We recommend a two‑stage investment cadence for wafer fabs and toolsets: an initial proof‑of‑capability tranche followed by a scaled capex trigger tied to volume and yield milestones. Our financial models demonstrate how this reduces downside while preserving upside participation.
-
Prepare for M&A arbitrage: With rapid consolidation signals, acquirers can secure technology or capacity advantages by targeting specialized suppliers or optics integrators. The report provides a prioritized M&A target list and valuation ranges tied to revenue and technology readiness levels.
How to use the report in the next 90 days
-
Run the report’s stress scenarios against your product roadmap and update procurement lead times in your ERP or PLM systems.
-
Engage with our vendor scorecards to qualify 2–3 supply partners for NPI trials; use the included RFP templates to accelerate negotiations.
-
Initiate a short‑form board briefing that links chosen investment gates to the report’s financial templates and risk matrices.
-
Schedule a due diligence deep‑dive if you are exploring M&A or JV activity; the report’s annex contains a ready‑to‑use diligence checklist tailored to Si‑OLED technology and manufacturing.
PW Consulting’s Si‑OLED Microdisplay Market report is intentionally rich in modeling, playbooks and executable templates — but follows a “trailer” approach: the published briefing above demonstrates analytical depth while withholding the full set of segment tables, vendor scorecards and downloadable financial models. For the complete dataset, customizable templates, and to arrange a strategy workshop tailored to your organisation’s risk posture and growth ambitions, please visit our Si‑OLED Microdisplay Market report landing page or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Si Oled Microdisplay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com