

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
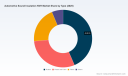
PW Consulting: Automotive Sound Insulation NVH Market to Grow at 5.85% CAGR, Rising from USD 14.19B in 2025 to USD 21.12B by 2032 — Asia Pacific Leads with USD 8.11B
By pmarketresearch, 2026-07-15
Automotive Sound Insulation NVH Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market research — the Automotive Sound Insulation NVH Market Report (base year 2025) — positions 2026 as a pivotal year for automotive original equipment manufacturers (OEMs), suppliers, and tier‑1 integrators. Drawing on a comprehensive historical review (2020–2025) and a forward forecast to 2032, the study quantifies an expanding total addressable market and maps the practical routes organizations must follow to convert regulatory pressure, electrification dynamics, and material innovation into durable competitive advantage.
Automotive Sound Insulation NVH Market
Headline macro view
Key macro takeaways from the study are unambiguous: the global sound insulation NVH market has recovered and accelerated through the early 2020s and reached an inflection at the 2025 base year. Our top‑line forecast shows the market continuing to expand through 2032 at a compound annual growth rate (CAGR) of 5.85%, reflecting a multi‑year structural upswing driven by regulatory tightening, the spread of electric vehicles, and heightened customer expectations for in‑cabin acoustic comfort. In monetary terms this growth translates into a material increase in industry revenue over the forecast horizon (reported in USD Million), underscoring both volume and value opportunities for strategically positioned players.
Automotive Sound Insulation NVH Market
Why 2026 matters: regulatory and technology accelerants
-
Regulatory inflection points. Two regulatory milestones compress timelines and compress the decision window for sound insulation investments: the EU’s phased noise limits (tied to tighter dB(A) thresholds) and the UNECE R51.03 Phase 3 update effective from July 2026, with revised urban weighting and high‑load testing. Together, these require automotive OEMs and suppliers to validate acoustic performance under more stringent and diverse test conditions — not a future consideration but an immediate procurement and design constraint for 2026 VINs.
Automotive Sound Insulation NVH Market -
Electrification alters the NVH problem set. Battery and electric drive architectures reduce engine masking and shift subjective noise drivers toward road, tire, aerodynamic and electrical tonal content. That pivot increases the relative value of passive insulation materials, tuned damping systems, and hybrid solutions (materials + architectural decoupling + targeted active control) — and expands the role of acoustics earlier in vehicle architecture programmes.
-
Sustainability and lightweighting converge with NVH. Suppliers that can deliver high acoustic performance per unit mass and demonstrate recycled‑content credentials will secure preferential design slots. This is not incremental: it materially affects supplier selection, bill‑of‑materials (BOM) economics, and crash/packaging trade‑offs in 2026 platform specifications.
Practical value of the report for 2026 corporate decisions
Clients engaging with PW Consulting will find this report is structured as an operational playbook, not an academic paper. It converts the macro trend (5.85% CAGR and the quantified market trajectory) into prioritized, executable choices across product development, sourcing, pricing, and M&A to be decided in 2026:
-
Product roadmap sequencing — which material technologies and NVH system architectures to fast‑track for 2026 platform launches versus those that can be phased for 2027–2028.
-
Procurement and supplier risk matrices — supplier concentration heatmaps, dual‑sourcing thresholds, and inbound logistics sensitivity to raw material price and recycling policy shifts.
-
Technology investment case templates — NPV and payback analyses for investments in new material lines, adhesive application systems, and active sound control integration, calibrated for 2026 regulatory compliance timing.
-
Go‑to‑market and pricing playbooks — value capture strategies for OEMs and tier‑1s seeking to monetize improved NVH packages while preserving list‑price discipline under cost pressure.
Report contents at a glance (operational modules)
-
Market sizing and growth modelling (2020–2025 historical, 2026–2032 forecast) with scenario stress tests tied to regulatory and EV adoption pathways.
-
Materials performance compendium — comparative matrices (mass, absorption/damping performance, recyclability, cost per effective dB reduction) and targeted application use cases (interiors, powertrain enclosures, underbody, cavity filling).
-
Commercial benchmarking and margin archetypes — supplier margin corridors by technology approach and integration depth.
-
Competitive intelligence dossiers — strategic profiles, recent moves, capability maps and alliance matrices for leading NVH participants.
-
Implementation toolkits — BOM optimization templates, compliance roadmaps for UNECE and EU regimes, supplier selection scorecards, and M&A diligence checklists.
-
Proprietary scenario models — run‑time decision dashboards that let teams quantify trade‑offs between weight, cost, manufacturability and acoustic performance for immediate use in 2026 programme gates.
Competitive landscape and strategic implications
The NVH supply base remains neither fragmented nor oligopolistic — a market structure where leading specialists capture meaningful value but nimble challengers can still win program content through technology or sustainability differentiation. Our report highlights the following strategic archetypes among incumbent and emerging suppliers:
-
Platform specialists (e.g., Autoneum) — firms that combine lightweight fiber‑based systems with high recycled content are consolidating their role in interior acoustic architecture. Their public showcases and conference engagements underscore a two‑pronged strategy: lift acoustic performance while advancing mono‑material and recyclable carpet systems that ease end‑of‑life recovery.
-
Materials innovators (e.g., BASF, Dow) — chemical majors are extending foam, elastomer and engineered polymer portfolios to serve chassis mounts, cavity fillers and tailored dampers. Their advantage lies in material science depth and scale‑up capabilities, enabling faster translation of lab innovations into validated OEM releases.
-
System integrators with specialty know‑how (e.g., Vibracoustic, Sumitomo Riko) — these players focus on engineered mounts, air springs and decoupling systems optimized for EV NVH signatures. Recent program wins for electric pickup trucks and premium segments highlight the premium OEM need for integrated mechanical NVH solutions beyond passive insulation alone.
-
Adjacency players (e.g., 3M, Henkel, ElringKlinger) — firms supplying acoustic adhesives, thin‑film insulations, and sealing solutions are moving up the value chain through higher‑performance laminates and application engineering capabilities, enabling faster in‑vehicle validation cycles.
Observed strategic moves during 2024–2025 demonstrate clear priorities: product showcases at major industry fora; targeted program supply for premium EVs; and the roll‑out of mono‑material and recycled‑content solutions. These moves are consistent with the broader market trajectory and the CR3/CR5 concentration dynamics we map in the report — a competitive field where scale, IP in material science, and early OEM co‑development wins translate into outsized program containment.
Operational recommendations for 2026 planning cycles
-
Accelerate acoustic targets into early architecture phases. Make NVH an explicit 1.0 requirement in 2026 platform definition rather than a later optimization task — test cases in our modelling show this reduces retrofit cost and program risk.
-
Adopt a hybrid sourcing model. Combine long‑term partnerships with material innovators for core acoustic modules and flexible spot contracts for commodity foam and adhesive supply to manage input volatility.
-
Prioritize mono‑material and recycled‑content solutions where mass and end‑of‑life policy overlap; include recyclability KPIs in supplier scorecards to align with regulatory and consumer pressures.
-
Embed regulatory compliance pathways in programme gates. With UNECE R51.03 Phase 3 and tightened EU noise limits becoming binding, acoustic validation and documentation must be completed earlier in the verification chain to avoid costly redesigns.
-
Use M&A selectively to accelerate capability — small bolt‑on acquisitions of acoustic software, measurement houses, or niche materials producers often yield quicker in‑vehicle integration than greenfield investments.
Where the report stops — and why you should read the full study
In keeping with PW Consulting’s “trailer” principle, this press briefing surfaces the strategic implications of the market trajectory and competitive dynamics while intentionally omitting granular segmentation tables and line‑item regional splits that are central to procurement and M&A modelling. The decision‑useful, proprietary segmentation (by region, material type and application), supplier share breakdowns and the downloadable scenario workbooks are available exclusively in the full report and the client portal.
For teams preparing 2026 budgets, platform specifications, or sourcing roadmaps, the full report provides the specific segmented metrics, supplier scorecards, and downloadable modelling templates you will need to move from insight to execution.
Next steps
-
Contact PW Consulting to obtain the full Automotive Sound Insulation NVH Market Report and request an executive briefing tailored to your product line or procurement exposure.
-
Book a workshop to run the report’s scenario models on your vehicle programmes — accelerate compliance planning for UNECE R51.03 Phase 3 and EU noise limits.
-
Request a supplier due diligence deep dive (including on‑site capability assessments) to validate partner claims on recyclability and acoustic performance ahead of 2026 program approvals.
PW Consulting’s team of industry strategists and acoustic engineering specialists stand ready to translate the market’s 5.85% CAGR trajectory and the 2026 regulatory inflection into prioritized actions that protect margin, speed time‑to‑market, and secure acoustic leadership in the electric era.
For detailed analysis of this topic, please visit the official page: Automotive Sound Insulation NVH Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Retort Cartons Market Set to Expand at a 7.6% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Retort Cartons Market — Strategic Outlook for 2026
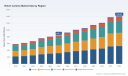
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an executive-level preview of our new Worldwide Retort Cartons Market report. Built on a robust base year (2025) and a 2026–2032 forecast horizon, the study maps a sector that is transitioning from niche alternative to mainstream packaging. The global market value expanded from roughly USD 585 million in 2020 to USD 842.5 million in 2025, and our models project continued momentum with a 7.6% compound annual growth rate (CAGR) across 2026–2032 — lifting the market toward the USD 1.4 billion range by the end of the forecast period. This briefing highlights the report’s strategic value to corporate decision-makers preparing plans, capital allocation, and product roadmaps in 2026 without disclosing the granular segment tables that are available in the full release.
Worldwide Retort Cartons Market
Why this report matters for 2026 decision cycles
-
Timing: 2026 is the inflection year for many regulatory, commercial and cost dynamics (EPR implementations and recycled content mandates) that will materially change packaging design and sourcing choices.
Worldwide Retort Cartons Market -
Capital allocation: Investors and supply-chain managers need a prioritized view of where retort carton investments will deliver the best ROI — the report translates market trajectory into actionable CAPEX scenarios.
Worldwide Retort Cartons Market -
Competitive strategy: With a highly concentrated supplier base (top-3 firms account for a dominant share and top-5 share is even higher), small strategic moves by market leaders can shift access to technology and co-manufacturing capacity; the report decodes the implications for fast movers and followers.
-
Sustainability compliance: Mandates on recyclability and recycled content will alter material selection roadmaps — the study provides compliance pathways and transition timelines tailored to corporate sustainability targets.
Key market dynamics shaping strategy
Four forces will determine winners in 2026 and beyond:
-
Regulatory acceleration: Extended Producer Responsibility (EPR) programs and EU packaging targets are accelerating demand for fiber-forward and mono-material retort solutions. Firms that align product design with anticipated recyclability rules will avoid future rework and market access costs.
-
Material and cost pressure: Recent supplier announcements and raw-material volatility have pushed paperboard and polymer cost considerations to the forefront of procurement discussions. Expect procurement-led initiatives — including hedging, long-term contracting, and secondary sourcing — to become table stakes.
-
Technology evolution: Innovations are converging on two tracks — high-barrier multi-layer laminates that preserve shelf-life and mono-material structures that simplify recycling. Thermoformable and retort-compatible polymer developments (including mono-PP solutions) create tactical choices between recyclability and barrier performance.
-
Consolidated supply base: The sector is structurally concentrated (CR3 and CR5 levels indicate a strong oligopoly). This creates both stability in technology roadmaps and the risk of constrained co-manufacturing capacity for newcomers or niche SKUs.
Competitive landscape — what to watch from the major players
Our competitive analysis profiles leading manufacturers and suppliers and distils their strategic playbooks. Below are distilled, actionable takeaways for boards and commercial leaders.
-
Tetra Pak (Pully, Switzerland) — A dominant innovator with established retort carton technology (Recart), filling systems and a clear sustainability narrative (high renewable paperboard content). Strategic takeaway: partners and buyers should evaluate Tetra Pak’s integrated offering for high-volume conversions from cans/jars, and consider licensing or co-manufacturing models to accelerate time-to-market.
-
Amcor (Zürich, Switzerland) — Focused on high-barrier materials and recently active in novel small-format retort bottles. Strategic takeaway: Amcor is strengthening solutions for low-acid beverages and ready-to-eat products; commercial teams should test joint product development pilots to capture first-mover shelf-space gains.
-
SIG Combibloc (Neuhausen, Switzerland) — Supplies integrated retort-capable systems for foods and beverages that need thermal processing. Strategic takeaway: evaluate SIG for vertically integrated fill-and-pack solutions when committing to new filling lines or formats.
-
Mondi (Weybridge, UK) — Expanding sustainable retort offerings and mono-material laminates. Strategic takeaway: Mondi’s portfolio supports compliance-heavy markets; prioritize discussions on lifecycle assessment tools and regulatory-ready formats.
-
Huhtamaki (Espoo, Finland) — Emphasizes fiber-based and mono-material approaches aligned with recyclability goals. Strategic takeaway: best positioned for customers prioritizing recyclability over absolute barrier performance.
-
Sonoco Products (Hartsville, SC, USA) — Offers both carton and flexible retort formats and maintains strong manufacturing presence. Strategic takeaway: Sonoco can be a strategic production partner for North American rollouts where proximity matters.
-
ProAmpac (Cincinnati, OH, USA) — Innovates in high-barrier flexible and carton hybrids for ready meals and pet food. Strategic takeaway: recommended for CPGs seeking flexible format experiments with lower capital intensity than full carton lines.
-
Constantia Flexibles (Vienna, Austria) — Developing mono-PP retort laminates and expanding eco portfolios. Strategic takeaway: offers technology paths that materially lower end-of-life complexity.
-
Coveris (Vienna, Austria) — Provides flexible and rigid retort formats suitable for thermal processing. Strategic takeaway: suitable for format diversification strategies and contract packaging pilots.
-
NaturPak Pet (Janesville, WI, USA) — Co-manufacturer leveraging Recart technology for premium pet food; positions itself on small-format, high-margin products. Strategic takeaway: attractive co-pack partner for brands testing small-batch premium segments without owning retort-capable assets.
Operational playbook — actions leaders should consider in 1–18 months
-
Portfolio prioritization: Segment your SKU base by barrier and recyclability needs; prioritize conversion candidates (products with clear cost and shelf-life advantage versus existing cans/jars) and pilot mono-material options in regulated markets.
-
Supply-chain resilience: Create multi-source strategies for paperboard and barrier films, negotiate volume-flexible contracts, and build material escalation clauses tied to transparent indices. Consider strategic buffer inventory or near-shore manufacturing for time-sensitive SKUs.
-
Manufacturing posture: Evaluate co-manufacturing vs. in-house conversion with a three-way IRR comparison (capex for lines, co-manufacturing margin, and time-to-market benefits). Short pilots with established co-packers can sharply reduce adoption risk.
-
Sustainability & compliance: Map EPR and recyclability timelines to product roadmaps. Use the report’s regulatory impact models to quantify compliance costs under alternative design choices and identify low-regret material changes.
-
Commercial go-to-market: Use small-format innovations for premiumization and sampling campaigns; employ barrier-first formats for long-shelf-life SKUs where logistics cost-offsets justify packaging premium.
-
M&A and Partnerships: Given market concentration, selective M&A or long-term alliances with technology leaders can secure capacity and proprietary formats. The report provides an M&A playbook with financial thresholds and negotiation checkpoints.
What’s inside the full report (high level)
-
Top-line market sizing and year-by-year forecasts across 2020–2032 with scenario sensitivity for regulatory and raw-material risk.
-
Competitive profiles and capability maps for all major suppliers, including technology roadmaps and co-manufacturing footprints.
-
Regulatory impact assessments for EPR and recyclability mandates, with transition cost estimates and compliance timelines.
-
Supply-chain risk matrix covering raw materials, price volatility, and logistical constraints, plus recommended mitigation actions.
-
Commercial and manufacturing playbooks with CAPEX/ROI templates, pilot checklists, and negotiation guides for converters and co-packers.
-
Appendices with technical notes on retort-compatible structures, material layer options, and lifecycle assessment methodologies.
We intentionally present a strategic preview here: detailed segment breakdowns, region-level splits, application-level revenue tables, and company-level revenue estimates are excluded from this release to preserve the report’s actionable intelligence. Those datasets and the underlying assumptions are available in the full report package for purchasers, along with downloadable financial models and scenario workbooks.
Immediate implications for executive agendas in 2026
-
Boards should require packaging roadmaps that reconcile sustainability commitments with product-level barrier requirements and margin targets.
-
Procurement leads must lock in dialogues with dual suppliers, and finance teams should run sensitivity analyses for material-price shocks during budgeting cycles.
-
R&D and commercial teams should agree on a pilot slate for at least two retort formats (one barrier-first and one recyclability-first) to de-risk supplier selection and market entry.
For companies evaluating investments or strategic pivots in the retort cartons space, the next 12 months are decisive. Our full Worldwide Retort Cartons Market report delivers the granular forecasting, supplier-level intelligence and operational tools required to prioritize actions, justify investments and negotiate from a position of knowledge. To access the complete dataset, segmented analyses, and executable playbooks, please visit the report page on the PW Consulting portal or contact your account representative to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Retort Cartons Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide JAK Inhibitors Market to Hit USD 40,565.2 Million by 2032, Growing at a 14.01% CAGR
By pmarketresearch, 2026-07-15
PW Consulting Strategic Brief: Worldwide Janus Kinase (JAK) Inhibitors Market — A 2026 Playbook for Executives
Executive snapshot
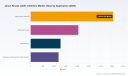
The JAK inhibitors sector is entering a decisive chapter. Our new Worldwide Janus Kinase (JAK) Inhibitors Market report (base year 2025, forecast period 2026–2032) maps the pathway for commercial, R&D, and M&A decisions that will define winners and laggards over the next strategic horizon. The market reached an estimated USD 16,200 Million in 2025 and is projected to expand at a robust compound annual growth rate (CAGR) of approximately 14.0% through 2032 — reaching a market size in excess of USD 40 billion by the end of the forecast window. This trajectory underscores attractive upside, but the route is uneven: concentrated competition, regulatory headwinds, patent cliffs, and supply vulnerabilities mean that timing and tactical choices in 2026 will materially affect long-term positioning.
Worldwide Janus Kinase (JAK) Inhibitors Market
Why this report matters for 2026 planning
-
Actionable foresight: Our models translate the macro growth trajectory into decision-ready scenarios — from conservative reimbursement outcomes to accelerated label expansions — enabling CFOs and BD teams to establish near-term investment thresholds.
Worldwide Janus Kinase (JAK) Inhibitors Market -
Competitive clarity: The market is highly concentrated among a handful of global players. Incumbents with established brands and broad indications maintain scale advantages, while specialty players and newer entrants pursue niche differentiation through selectivity profiles and adjunct targets. Understanding relative competitive moats and vulnerability windows is essential to craft either defensive or disruptive moves.
Worldwide Janus Kinase (JAK) Inhibitors Market -
Risk calibration: The market’s upside is coupled with discrete downside events that can rapidly reshuffle value — patent expiries, regulatory safety advisories, API supply shocks, and payer policy shifts. Our scenario matrices quantify potential revenue and margin impacts across these vectors, enabling stress-tested 2026 budgets.
-
Commercial playbooks: For 2026 launches and label expansions, the report supplies go-to-market playbooks that align clinical positioning, pricing, and patient support to payer pathways — including Medicare Part D dynamics — to optimize uptake under constrained access environments.
What the report contains — practical intelligence for immediate use
-
Market sizing and forecast engine (2020–2032) with base-year reconciliation and sensitivity toggles for key drivers such as indication uptake, pricing erosion, and biosimilar/generic entry timing.
-
Concentration and competitive landscape assessment, including an evidence-backed view of incumbent strengths, pipeline vectors, and white-space opportunities for selective JAK agents versus broader pan-JAK compounds.
-
Regulatory and safety scenario planning that models the commercial impact of label revisions, boxed warnings, and country-specific reimbursement policies.
-
Clinical and pipeline mapping tied to commercial potential — trial attrition profiles, expected approval windows, and prioritization matrices for indications with the highest near-term commercial leverage.
-
Supply-chain risk heatmaps and mitigation playbooks: API concentration analysis, dual-sourcing strategies, and inventory management protocols for 2026 continuity.
-
M&A and partnership blueprints: valuation frameworks for licensing, bolt-on acquisitions, and co-development deals that reflect time-to-market and incremental revenue accretion under multiple regulatory scenarios.
-
Payer engagement templates and real-world evidence (RWE) approaches designed to offset safety concerns and secure formulary access in priority markets.
Competitive dynamics — who matters and why
The competitive field is dominated by established Big Pharma and specialized biotech players that have converted clinical assets into commercial franchises. Key firms play different strategic roles:
-
Pfizer: An incumbent with a broad indication footprint and recent pediatric label expansion activity. Approaches to lifecycle management, especially as core patents approach expiration, will be pivotal to sustaining revenue density.
-
Incyte: Notable for products targeting hematologic and dermatologic niches; recent approvals of topical and cutaneous formulations demonstrate a strategy of expanding route-of-administration options to capture incremental patient cohorts.
-
Eli Lilly: Leveraging cross-indication approvals and pediatric label extensions to broaden the commercial runway for selective JAK agents; R&D synergies and scale commercialization are central to its playbook.
-
AbbVie: Driving rapid indication expansion into inflammatory bowel disease and pediatric populations; ability to combine clinical breadth with payer contracting strength is a differentiator.
-
Gilead (through partnerships): Access to selected markets via strategic alliances underscores a playbook that mixes partnership economics with targeted commercial deployment.
-
Conatus/Roivant: Represents the innovation frontier — next-generation selective molecules and combination approaches that, if clinical outcomes validate, could reshape therapeutic differentiation.
Recent regulatory and label events through 2024–2025 (including pediatric expansions and topical approvals) have created short-term commercial inflection points. Yet they exist alongside enduring safety constraints — the industry continues to operate under enhanced boxed safety warnings established in recent years — which means clinical differentiation and robust risk mitigation strategies remain central to market success.
Market structure and concentration
The sector exhibits significant concentration: a small set of global firms capture the lion’s share of market revenues, creating a marketplace characterized by scale advantages in distribution, contracting, and clinical evidence generation. This concentration creates both barriers and openings — incumbents can leverage scale to defend pricing and access, while agile challengers can win by offering compelling differentiation (e.g., improved selectivity, superior safety profile, or novel delivery formats).
Key strategic imperatives for 2026
-
Prioritize lifecycle management before patent cliffs: With major brands facing patent expiration pressures, firms should accelerate authorized generic strategies, portfolio extensions (route, indication, pediatric filings), and licensing deals to slow revenue erosion.
-
Invest in safety-driven evidence: Robust post-marketing safety programs and RWE that contextualize cardiovascular, malignancy, and thrombotic risks will be decisive for formulary positioning and patient confidence.
-
De-risk supply chains now: API sourcing concentration has led to episodic shortages; dual-sourcing, strategic inventory buffers, and supplier co-investment are practical mitigations that should be budgeted in 2026 operating plans.
-
Segment commercial approaches by selectivity profile: Distinct clinical and payer messaging is required for JAK1-selective agents versus broader-spectrum molecules; sales and medical affairs teams must be retooled accordingly.
-
Explore targeted M&A and alliances: For companies lacking scale, bolt-on assets that close clinical gaps or add differentiated delivery platforms can accelerate access; for incumbents, divestiture and partnering can optimize capital allocation.
-
Embed dynamic pricing models: Scenario-based pricing that ties to real-world outcomes and indication-specific value will help balance access with margin preservation as competitive entry increases.
Risk scenarios to model in your 2026 plan
-
Accelerated generic or biosimilar erosion following patent expiry in key markets — model up-front revenue loss vs. retained franchise value via authorized generics/licensing.
-
Regulatory tightening or expanded safety labeling — quantify the impact on penetration rates and payer mix across plausible severities.
-
Supply disruptions leading to temporary shortages — simulate revenue disruption at country and channel levels, and the cost of mitigation strategies.
-
Faster-than-anticipated adoption of next-generation selective agents — estimate share-shift timelines and required commercial investments to defend incumbent positions.
How companies should use the report
-
Corporate strategy teams: Use the forecast engine to set revenue targets, allocate R&D budgets, and evaluate divestiture or acquisition candidates.
-
Commercial leaders: Translate indication-level adoption curves and payor scenarios into salesforce sizing, promotional mix, and patient-support investments for 2026 launches or expansions.
-
Business development and licensing: Leverage our valuation frameworks to price deals, structure milestone payments, and negotiate co-commercialization terms that reflect regulatory risk and time-to-market.
-
Supply-chain and operations: Apply our supplier risk scores and mitigation playbooks to secure continuity and minimize fulfillment-related revenue leakage.
Conclusion — the 2026 imperative
The JAK inhibitors market offers compelling growth, with an expected market value moving from the mid-teens (USD Million) in 2025 to north of USD 40 billion by 2032, underpinned by accelerating adoption across multiple indications and ongoing product innovation. Yet the path to capture this upside is neither simple nor linear. 2026 is a window for decisive actions: fortify supply, shore up lifecycle strategies ahead of patent expiries, invest in safety evidence, and pursue targeted partnerships. Firms that implement a calibrated mix of defensive and selective offensive moves will convert the favorable macro growth into sustainable competitive advantage.
Access the full analysis
This briefing highlights the strategic implications of our findings while intentionally omitting detailed subsegment tables and granular regional/application splits to encourage direct access to the full report. PW Consulting’s Worldwide Janus Kinase (JAK) Inhibitors Market report provides the complete dataset, downloadable models, and bespoke scenario toolkits to operationalize the recommendations above. For inquiries and to obtain the full report, contact PW Consulting’s life sciences practice or visit our website.
For detailed analysis of this topic, please visit the official page: Worldwide Janus Kinase (JAK) Inhibitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
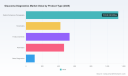
PW Consulting: Worldwide Glaucoma Diagnostics Market valued at USD 2,674.0 Million in 2025, set to reach USD 3,765.1 Million by 2032 at a 5.01% CAGR — OCT leads with USD 1,135.96 Million
By pmarketresearch, 2026-07-15
Worldwide Glaucoma Diagnostics Market — Strategic Imperatives for 2026
PW Consulting today releases a strategic briefing drawn from our forthcoming Worldwide Glaucoma Diagnostics Market report (base year 2025, historical window 2020–2025, forecast 2026–2032). The market crossed an important threshold in 2025, reaching approximately USD 2,674 Million, and is projected to expand at a compound annual growth rate (CAGR) of 5.01% through the 2026–2032 forecast horizon. These high‑level dynamics mask differentiated opportunity pockets and risk vectors that will determine winners and laggards in the next strategic planning cycle — the analysis below explains why 2026 is the year to act and what capabilities matter most.
Worldwide Glaucoma Diagnostics Market
Why this report matters for 2026 decision-makers
Executives setting 2026 budgets face a convergence of forces: sustainably rising demand driven by demographic and screening tailwinds; rapid software and AI maturation that changes product value propositions; tighter regulatory and reimbursement controls for device classes; and selective consolidation among leading suppliers. Our report translates those macro realities into operational choices: where to prioritize R&D, which product adjacencies to pursue (hardware, software, service), how to design field trials and pilots that accelerate payer acceptance, and what inorganic moves will unlock scale without destroying margins.
Worldwide Glaucoma Diagnostics Market
What the report contains — practical, executable intelligence
- Proprietary market forecast model (2026–2032) with scenario sensitivity — base, upside, and downside — calibrated to observed demand elasticities and technology substitution rates.
- Multi‑axis segmentation (by geography, product family, and end‑user) with demand drivers, adoption curves and friction points for each cell. Note: headline totals and growth rates are published here; detailed cell-level values are reserved for the full report to preserve the strategic “teaser” intent.
- Competitive landscaping and benchmarking including CR3 and CR5 concentration metrics, supplier positioning maps, and capability heatmaps for clinical accuracy, peripheral enablement (connectivity/telehealth), and service economics.
- Regulatory and reimbursement playbooks tied to product classes (including device classification impacts and CPT‑level implications), plus a standardized checklist to accelerate 510(k)/CE/other filings.
- Commercial GTM (go‑to‑market) blueprints for incumbent OEMs, software-first entrants, and private equity acquirers — including channel strategies, pricing archetypes, and pilot design templates for payer engagement.
- M&A and partnership scorecards identifying target archetypes, expected value creation levers, and integration risk factors.
- Field‑tested buyer persona profiles and procurement flows for ophthalmic clinics, hospitals, and diagnostic centers, together with decision‑criteria matrices used by buyers during capital allocations.
- Implementation and change management playbooks for deploying hybrid diagnostic stacks (device + AI + cloud) in real-world clinical operations.
Strategic implications: six priorities for 2026
- Make software a first-class product pillar. Hardware alone increasingly commoditizes. Clinical AI modules and analytics platforms that materially shorten the diagnostic pathway or improve longitudinal monitoring create differentiation and recurring revenue potential.
- Invest selectively in home and remote monitoring capabilities. Clinical studies and product launches over the last 24 months validate home tonometry and portable fundus imaging as credible extensions of practice workflows. Building robust connectivity, data governance and reimbursement playbooks now will accelerate adoption.
- Design trials for payers, not just regulators. Regulatory clearance ensures market access; payer acceptance secures reimbursement. Trials that quantify clinical‑economic value (e.g., avoided sight‑loss events, clinic visit offsets) unlock scale in institutional channels.
- Prioritize interoperability and lifecycle service economics. Buyers increasingly evaluate total cost of ownership (TCO). Modular, upgradeable platforms with clear service and consumable economics win in procurement competitions.
- Use M&A as capability shortcut, not revenue shortcut. Acquirers should target gaps in analytics, data orchestration, or channel presence rather than incremental device portfolios that amplify integration complexity.
- Embed regulatory change monitoring into product roadmaps. Device class reclassifications and standard updates materially affect time to market and cost of compliance. A proactive regulatory intelligence function reduces surprise delays.
Competitive landscape — who’s shaping the market
The diagnostic ecosystem is a mix of legacy optical OEMs, specialty device makers, and agile digital entrants. Market concentration is meaningful: the top three suppliers capture a near‑majority share of industry revenue, and the top five approach two‑thirds of the market by revenue — a structure that favors scale and integrated product bundles. Below we summarize the strategic roles of core incumbents and recent moves to watch in 2024–2025.
Worldwide Glaucoma Diagnostics Market
- Zeiss (Germany) — A leader in OCT platforms and integrated measurement systems, with continued investment in analytics. In late 2025 the company refreshed its OCT family with enhanced glaucoma analytics, signaling an ongoing shift toward bundled hardware‑software propositions. (See Zeiss Meditec for product details.)
- Heidelberg Engineering (Germany) — Recognized for retinal imaging and OCT platforms with focused glaucoma modules; recent software updates emphasize longitudinal progression detection, strengthening clinician workflows for follow‑up and triage.
- Topcon (Japan) — Multi‑modal portfolio including swept‑source OCT and visual field analyzers; regulatory milestones such as recent FDA 510(k) clearances for AI‑enabled visual field devices broaden market access in major geographies.
- Nidek (Japan) and Haag‑Streit (Switzerland) — Strong presence in tonometry and perimetry respectively; engineering depth in clinical ergonomics and instrument reliability remains their competitive mooring.
- Reichert Technologies (USA), Canon Medical Systems (Japan), Kowa (Japan), iCare (Finland) — Each brings differentiated strengths: corneal biomechanics, non‑contact tonometry, fundus imaging, and home monitoring solutions respectively. Notably, clinical validation and wireless connectivity innovations have been prominent in their recent product updates.
- Carelon Medical Technologies (USA) — A representative of camera + AI entrants with portable fundus imaging solutions designed for decentralized screening and community care models.
Recent public developments underscore strategic vectors to watch: software refreshes that embed AI‑driven progression analytics; FDA clearances that lower regulatory friction for AI‑enabled visual field products; wireless and home‑monitoring device launches; and clinical studies that validate remote IOP monitoring. Collectively, these moves compress time‑to‑value for analytics layers and alter purchasing criteria in 2026.
Regulatory and reimbursement dynamics that will determine adoption speed
- Regulatory classification matters: non‑contact tonometers are regulated as Class II devices in the U.S., requiring 510(k) premarket notification — an important gating factor for device roadmaps targeting ambulatory settings.
- Reimbursement archetypes remain fragmented but actionable. Representative CPT pathways exist for optic nerve imaging and visual field testing; navigating the local reimbursement landscape — and constructing cost‑offset narratives for payers — materially accelerates deployment.
- Standards such as ISO 8619:2019 for Goldmann‑type applanation tonometers set performance baselines that procurement committees use to shortlist technology vendors.
How leading buyers should use this intelligence in 2026
- Health system CMOs and purchasing directors: use the report to map supplier bundles against your patient volume and longitudinal follow‑up needs; prioritize contracts that reduce clinic visit burden through validated remote monitoring.
- Device OEMs and software companies: overlay your product roadmap against the report’s adoption curves to time product launches, pilot geographies and reimbursement dossiers.
- Private equity and corporate development teams: apply the M&A scoreboard and valuation sensitivity tables to shortlist targets where synergies in distribution or analytics materially compress payback periods.
- Regulatory and reimbursement teams: use the regulatory checklists and payer trial templates to design studies that generate both clearance documents and payer‑facing economic dossiers.
Why PW Consulting’s analysis is distinct
Our methodology combines bottom‑up device shipment modeling, clinician and procurement interviews across major healthcare systems, hands‑on evaluation of device performance claims, and reimbursement scenario testing. We validate forecasts through multi‑disciplinary triangulation — clinical, economic and regulatory — and produce a downloadable financial model that lets clients stress‑test strategic options. In keeping with the “prequel” ethos, this briefing highlights findings that are immediately actionable while reserving the full cell‑level datasets and proprietary vendor scoring matrices for report subscribers.
Next steps — where to get the full intelligence
For C‑suite teams, product leads and investors preparing 2026 strategies, the full report provides the granular market splits, country‑level demand curves, vendor revenue and share estimates, and a ready‑to‑use financial model. Those materials are designed to be plugged directly into board materials and investment memos to shorten decision cycles. Visit PW Consulting’s report page to access the full dataset, annexes, and licensing options for our interactive forecasting model.
In a market growing at a steady mid‑single digit CAGR, 2026 will favor organizations that pair clinical credibility with software economics, and that can translate regulatory clearances into payer‑backed, scalable care pathways. The moment to align strategy with execution is now; our full report shows exactly how.
For detailed analysis of this topic, please visit the official page: Worldwide Glaucoma Diagnostics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Non‑Thermal Food Processing Market Poised to Expand at a Robust 10% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Non‑Thermal Food Processing Market: Strategic Preview for 2026 Decisions
Executive snapshot
PW Consulting’s latest market study on Worldwide Non‑Thermal Food Processing (base year 2025) delivers a decision‑grade briefing designed to orient C‑suite leaders, corporate strategists, and capital allocators as they set priorities for 2026. The non‑thermal processing market has shown sustained expansion through the 2020–2025 historical window and is projected to grow at a compound annual growth rate (CAGR) of approximately 10.0% over our 2026–2032 forecast horizon. Underpinning this trajectory is an accelerating commercialization of High Pressure Processing (HPP), Pulsed Electric Fields (PEF), ultrasound and plasma solutions, and an increasingly tight interplay among regulation, ingredient sourcing and packaging innovation.
Worldwide Non-Thermal Food Processing Market
Why 2026 is the inflection point
-
Operational scaling is now the dominant challenge. Early adopters validated product quality and shelf‑life improvements; the next wave must prove cost‑efficient scale while meeting stringent food‑safety and cross‑border compliance requirements.
Worldwide Non-Thermal Food Processing Market -
Regulatory equivalence and acceptance have matured into a commercial enabler. Notably, regulatory frameworks in major markets have clarified that select non‑thermal modalities can meet pasteurization and microbial reduction standards, removing a prior source of ambiguity for exporters and brand owners.
Worldwide Non-Thermal Food Processing Market -
Supply‑chain pressure and input volatility are increasing the value of technologies that both minimize waste and preserve yield — creating differentiated ROI profiles across product categories and processing lines.
Market trajectory — what the headline numbers tell you
The market has moved from early validation to robust growth: after several years of compound expansion in the early 2020s, our base‑year analysis for 2025 shows a materially larger market relative to 2020, and our forecast to 2032 anticipates the market roughly doubling over the forecast window (currency: USD, revenue unit: Million). This scale and a projected ~10% CAGR mean that by 2026 leadership teams must pivot from small‑scale testing to investment planning for multi‑line integration and distributed processing footprints.
Strategic implications for 2026 planning
-
Reframe investment criteria from technology novelty to unit‑economics at scale. Capital planners should model full production lines (including upstream packaging and downstream cold‑chain) rather than isolated equipment purchases.
-
Prioritize regulatory and market access mapping early. Where export routes or premium channels are material to your plan, compliance roadmaps (including country‑specific validations) need to be in place prior to commissioning.
-
Introduce modular deployment pilots that preserve optionality. Pilot cells that can be redeployed between SKUs and sites reduce execution risk as demand patterns shift.
-
Embed ingredient and yield sensitivity in business cases. Technologies that reduce spoilage or increase extractable yield change the unit economics materially — these must be stress‑tested under volatile raw‑material scenarios.
-
Align commercial launches with supply‑chain capability. Marketing timelines and retailer listing agreements should be conditioned on validated throughput and packaging compatibility to avoid launch delays.
Competitive landscape — who matters and why
The non‑thermal equipment and systems market is concentrated, with a clear set of global leaders and a cluster of specialized innovators. Our competitive concentration metrics indicate a market that has meaningful incumbency advantage at the top, while room remains for niche challengers focused on product‑specific value propositions.
-
Hiperbaric (Burgos, Spain) — A global leader in HPP equipment. Hiperbaric’s product pipeline and recent launches emphasize yield optimization and throughput improvements tailored to juice and protein segments. Their engineering cadence and installed base create a high‑barrier to entry for commoditized HPP units.
-
JBT FoodTech (Chaska, Minnesota, USA) — Broad systems integrator offering industrial HPP systems and end‑to‑end non‑thermal lines. JBT’s strategy emphasizes scale and geographic footprint, evidenced by recent manufacturing expansions aimed at reducing lead times in high‑growth regions.
-
Multivac Group (Wolfertschwenden, Germany) — Provides integrated HPP with packaging systems, positioning itself where equipment and primary packaging converge. This integrated play appeals to processors seeking single‑vendor SLAs for sterilization and primary‑pack integrity.
-
Elea Technology GmbH (Quakenbrück, Germany) — A specialist in PEF systems for cell‑disruption applications. Elea’s demonstrations at major trade shows underscore the modality’s commercial traction in starch‑ and vegetable‑processing workflows.
-
Pulsemaster (Ochten, Netherlands) — Focused on PEF solutions that enhance extraction and shelf stability, often partnering with ingredient processors and co‑packers to validate incremental yield gains.
-
Steriflow (Thyssenkrupp) (Quimper, France) — Offers both autoclave and HPP systems, representing a bridge between established thermal processes and non‑thermal adoption for food manufacturers seeking dual‑mode capabilities.
Recent vendor activities in the last 24 months — product launches, trade‑show demonstrations and strategic manufacturing expansions — indicate a race to capture installed‑base growth rather than to redefine the technology roadmap. Market entrants should therefore evaluate acquisition and partnership pathways as a faster route to scale than organic equipment development.
Regulation, input risk and cross‑border trade — the non‑technical constraints
Regulatory clarity is a tailwind: authorities in several major markets now treat certain non‑thermal interventions as compliant with pasteurization and pathogen reduction standards, which reduces market entry friction for exporters. However, regulatory equivalence does not remove the need for documented validation and country‑specific declarations — exporters must maintain a compliance playbook for each target market.
Supply‑side risks remain material. Ingredient price volatility and labor cost dynamics change the optimal technology choice for processors: a modality that preserves yield or reduces manual handling can deliver outsized returns in high‑cost labor markets, whereas in other contexts the decision will be driven by throughput and CapEx intensity. Trade frictions and novel‑food rules in some jurisdictions introduce additional time‑to‑market considerations that must be modeled into any 2026 rollout plan.
What PW Consulting’s report delivers — practical, not academic
This study is designed to be operationally usable at the board and plant level. Deliverables include:
-
Executive decision matrices that map technology choice to ROI under multiple demand and input‑cost scenarios, with ready‑to‑use sensitivity tables for CFOs.
-
Integration blueprints for moving from pilot lines to full cellular manufacturing, including recommended CapEx staging, bottleneck analysis and typical commissioning timelines.
-
Vendor scorecards and supplier negotiation playbooks that translate technical claims into commercial warrantied outcomes, helping procurement teams reduce acquisition and lifecycle risk.
-
Regulatory pathways and documentation checklists per major trade corridor to shorten market‑access timelines and avoid costly rework.
-
Operational KPIs and control charts for plant managers to monitor product integrity, yield and energy intensity of non‑thermal lines.
-
Case studies and investment teasers that illustrate three archetypal 2026 investment plays — retrofit, brownfield expansion and greenfield hub — with annotated P&L impacts and payback ranges.
How to use this preview to act in 2026
-
Use the headline market trajectory and concentration indicators to benchmark your competitive positioning: leaders are scaling capacity while challengers are carving niches around SKU‑level economics and service models.
-
Prioritize cross‑functional trials (operations, quality, procurement and commercial) that close the gap between laboratory claims and full‑line economics. Insist on trials that emulate commercial cycle times and packaging formats.
-
Lock regulatory and export questions early. If export premium channels form part of the strategy, build the compliance timeline into launch gating criteria.
-
Design procurement RFIs to capture total cost of ownership — include spare parts, service SLAs, training and decommissioning costs to avoid downstream surprises.
Final perspective
The non‑thermal processing market is entering a new phase where technology choice is inseparable from supply‑chain reality, regulatory positioning and commercial go‑to‑market design. Our analysis confirms that the winners in 2026 will be those who move beyond equipment selection to integrate legal, operational and commercial strategies into a single roadmap — and who can execute modular scale‑ups that preserve strategic optionality.
For procurement teams, operational leaders and investors preparing budgets and roadmaps for 2026, PW Consulting’s full report provides the granular models, vendor benchmarks and scenario P&L tools required to make defensible commitments. This preview outlines the strategic stakes; the complete study contains the underlying segment tables, vendor rankings and financial models necessary to finalize capital allocations and implementation timelines.
Next steps
Contact PW Consulting or visit our report page to access the full Worldwide Non‑Thermal Food Processing Market study, which includes the comprehensive appendices, data tables and executable templates referenced in this release. The detailed subsegment matrices and vendor financial models are available exclusively in the full report and are intended to support binding 2026 investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Non-Thermal Food Processing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Oyster Shell Calcium Market to Hit USD 772.93 Million by 2032 at 6.02% CAGR — Asia‑Pacific Leads with USD 203.1M
By pmarketresearch, 2026-07-15
Worldwide Oyster Shell Calcium Market: Strategic Imperatives for 2026 — A PW Consulting Preview
PW Consulting today releases a strategic preview of its in-depth market research report on the Worldwide Oyster Shell Calcium Market (base year 2025, forecast 2026–2032). As companies position for growth and resilience in 2026, this briefing explains why oyster shell calcium is moving from niche commodity to strategic ingredient — and how executives should translate macro market trajectories and competitive structure into actionable decisions. The full report contains the granular segmentation, pricing curves, and proprietary datasets that corporate strategists, M&A teams, and procurement leads will need to execute effectively.
Worldwide Oyster Shell Calcium Market
Why 2026 Is a Pivotal Year
After a steady expansion through the early 2020s, the oyster shell calcium market demonstrated renewed momentum in 2024–2025. Our market model estimates a global market size of approximately USD 513 million in 2025 and projects a compound annual growth rate (CAGR) of roughly 6.02% across the 2026–2032 forecast window, with the market approaching the high hundreds of millions by the end of the period.
Worldwide Oyster Shell Calcium Market
For 2026, three converging dynamics make timely, well-informed action essential:
Worldwide Oyster Shell Calcium Market
- Ingredient substitution and formulation innovation in dietary supplements and functional foods are increasing demand for high-purity, sustainably sourced calcium inputs.
- Animal nutrition and agricultural uses are driving volume demand while creating bifurcated requirements for quality and processing (e.g., powder vs. granular formats).
- Sustainability considerations — circular economy strategies that valorize shell waste — are reshaping sourcing strategies, regulatory expectations, and branding opportunities.
High-level Market Dynamics and Strategic Implications
Key macro signals from our analysis that should shape 2026 strategy include:
- Moderate, predictable growth: The market’s mid-single-digit CAGR enables multi-year planning for capacity investments and supply agreements without the distortions of hypergrowth. Firms can adopt staged capacity expansions and long-term offtake contracts rather than speculative build-outs.
- Fragmentation with concentration at the top: Market concentration metrics indicate a landscape where a limited set of larger players command a meaningful share, but there remains room for specialized suppliers and regional champions — a structure that supports both consolidation plays and niche differentiation strategies.
- Format- and application-driven premiums: Different forms and technical grades command divergent value propositions. Producers investing in higher-purity processing and certification (pharmaceutical, food-grade) can capture margin and strategic customers; commodity-grade volumes remain important for feed and bulk agricultural uses.
- Sustainability as competitive advantage: Buyers increasingly evaluate carbon intensity, traceability, and circularity in supplier selection. Firms that can credibly demonstrate shell-byproduct utilization and low-impact logistics can leverage ESG as a differentiator in B2B negotiations and consumer-facing channels.
What the Report Contains — Practical, Transaction-Ready Intelligence
PW Consulting’s full report is structured to move decision-makers from insight to action. The institutional deliverables include:
- Executive synthesis with scenario-tailored recommendations for procurement, R&D, and product management teams.
- Historical market sizing (2020–2025) and a detailed forecasting engine for 2026–2032, enabling sensitivity testing under alternative demand and raw-material scenarios.
- Segmented demand analysis by form, application, and region — with dynamic maps of trade flows and interregional arbitrage opportunities. (Note: segmentation tables and unit-price curves are accessible in the full report.)
- Competitive intelligence dossiers covering leading producers, innovators, and potential disruptors, plus a quantified concentration assessment and M&A watchlist.
- Regulatory and quality-matrix by jurisdiction, including pathways for food, supplement, and pharmaceutical approvals and recommended compliance workflows.
- Commercial playbooks: supplier selection scorecards, contract templates for long-term offtake, and recommended capex sequencing aligned to price-cycle scenarios.
- Primary research appendix: interviews with key buyers, processors, and export intermediaries plus methodology and data sources for replication.
This practical mix of strategic frameworks and transaction-level tools is designed to shorten time-to-decision for teams gearing up in 2026.
Competitive Landscape — Strategic Reads on Core Players
The industry shows a mix of highly specialized producers and regional bulk suppliers. Below we profile three influential firms and extract strategic implications for potential partners, competitors, and acquirers.
-
Carich Biotechnology Co., Ltd. (Taichung, Taiwan)
Profile: Carich has positioned itself as a premium supplier, producing high-purity oyster shell calcium carbonate powder targeted at dietary supplements and pharmaceutical applications. Its technical capabilities to achieve very high CaCO3 content enable downstream formulators to meet strict regulatory and labeling requirements.
Strategic lens: Carich represents the archetype for margin-focused, quality-driven plays. Companies seeking to secure pharma- or supplement-grade supply should evaluate partnerships, white-label opportunities, or minority equity investments to lock in certified capacities. In a consolidating market, Carich’s technical bar may also make it an attractive target for ingredient houses aiming to expand into certified supplement inputs.
-
Viet Delta Industrial Co., Ltd. (Ho Chi Minh City, Vietnam)
Profile: Viet Delta is oriented toward ground oyster shell powder exports, serving animal feed, agricultural, and general nutrition markets. Its scale and cost-competitive sourcing model support volume contracts and commodity sales.
Strategic lens: Viet Delta illustrates the advantage of competitive cost structures and export-led growth. Buyers prioritizing volume and cost efficiency — for instance, feed formulators or agricultural distributors — should intensify supplier qualification processes in Vietnam and similar sourcing hubs. Conversely, premium producers may look to differentiate via technical services and certification to reduce direct exposure to price cycles that primarily affect commodity suppliers.
-
Eiwa Chemical Industrial Co., Ltd. (Osaka, Japan)
Profile: Eiwa supplies processed oyster shell calcium tailored for food supplements and functional material applications. Its product mix suggests a balance between technical quality and commercial versatility.
Strategic lens: Eiwa’s position offers a playbook for mid-sized firms that aim to capture both food-grade and functional-materials demand. For global ingredient distributors, companies like Eiwa are attractive alliance partners to broaden product portfolios while maintaining consistent quality standards across markets with strict hygiene and traceability demands.
Strategic Recommendations for 2026
Based on the market trajectory and competitive dynamics, we recommend the following priority actions for leadership teams preparing annual planning cycles and 2026 capital allocation:
- Segment your route-to-market by value proposition: Create parallel GTM tracks: (1) premium certified supply for supplement/pharma customers with service-level commitments; (2) cost-competitive bulk channels for feed/agriculture. Distinct commercial KPIs and contract structures should govern each track.
- Lock in mid-term supply with optionality: Use flexible offtake agreements with volume bands and price collars to manage raw material and shipping volatility. Consider toll-processing or JV models near shell-rich coasts to reduce logistics and raw-material waste.
- Invest selectively in processing that enables upward migration: Upgrading purification and particle control yields disproportionate margin expansion in supplement and pharmaceutical channels. Evaluate retrofits versus greenfield on an NPV basis using the report’s scenario engine.
- Leverage sustainability as a commercial lever: Pursue shell-waste traceability, third-party certification, and lifecycle communication to unlock premium channels and reduce procurement pushback in ESG-conscious buyers.
- Monitor consolidation opportunities: Given measured market concentration, acquisitive strategies should prioritize capabilities (e.g., pharma-grade processing) or regional access rather than chasing pure-volume targets.
Risks and Contingencies
Executives should incorporate the following risk vectors into 2026 plans:
- Feedstock supply shocks: Localized ecological events, regulatory harvest restrictions, or changes in seafood processing practices can constrict shell supply in certain sourcing geographies.
- Quality and compliance escalations: Evolving food and pharmaceutical standards may increase certification costs and time-to-market for new suppliers.
- Price pressure in commodity channels: Bulk segments remain exposed to cyclical pricing and logistics cost swings. Hedging and contract design are essential mitigants.
- Technology and substitution risk: Alternative calcium sources and synthetic materials could disrupt lower-end demand if they offer comparable cost or performance advantages.
How PW Consulting’s Report Supports Decision Execution
Our full report provides the quantitative backbone and playbooks to act on the recommendations above. Highlights that help 2026 execution include scenario-driven capex models, supplier scorecards, a regulatory pathway matrix, and an M&A readiness checklist. For procurement and corporate development teams, the report’s primary-sourced interview evidence and the forecast engine enable rapid evaluation of deal economics and supplier diversification strategies.
Next Steps — Where to Find the Complete Analysis
This preview summarizes the strategic contours and immediate implications from PW Consulting’s Worldwide Oyster Shell Calcium Market study. To access the granular segmentation tables, region- and application-level forecasts, unit-price curves, and the full competitive dossiers (including contactable intelligence and due-diligence checklists), please consult the full report on PW Consulting’s website. The detailed annexes and the forecast model are provided with licensed access to support corporate planning cycles and transaction diligence in 2026.
For organizations preparing supplier strategies, R&D roadmaps, or M&A pipelines in 2026, the full PW Consulting study is designed to reduce execution risk and accelerate time-to-opportunity.
If you would like a tailored briefing of how the report’s insights apply to your business, contact PW Consulting’s industry desk to schedule a 60-minute strategic workshop and scenario walk-through.
For detailed analysis of this topic, please visit the official page: Worldwide Oyster Shell Calcium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Adult Ventricular Assist Device Market Set to Expand at a 5.81% CAGR During 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Adult Ventricular Assist Device Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As healthcare systems and medtech players confront mounting clinical demand and evolving regulatory and reimbursement pressures, the Worldwide Adult Ventricular Assist Device (VAD) market is entering a phase where strategic clarity will determine winners and losers. PW Consulting’s new market study — built on a 2025 base year and a 2026–2032 forecast horizon — synthesizes longitudinal market dynamics and forward-looking scenario analysis to equip executives with the insights required to make high-consequence decisions in 2026.
Worldwide Adult Ventricular Assist Device Market
Quick take: where the market stands
The adult VAD market demonstrated steady expansion through the first half of the 2020s, rising from approximately USD 1.39 billion in 2020 to about USD 1.85 billion in 2025. Our forecastity framework projects a compound annual growth rate (CAGR) of 5.81% across 2026–2032, reaching roughly USD 2.74 billion by 2032 under the central scenario. Two implications are immediate: the market is large enough to sustain differentiated clinical platforms and service models, yet not commoditized — leading to structural concentration among established incumbents.
Worldwide Adult Ventricular Assist Device Market
Why this matters for 2026 corporate planning
-
Capital allocation. The mid-single-digit CAGR signals predictable baseline demand, but growth pockets are concentrated around product innovation, extended indications, and post-market service. Capital deployment going into 2026 must balance continued core-LVAD support with targeted investments in next-generation device development and digital service offerings.
Worldwide Adult Ventricular Assist Device Market -
Risk-adjusted R&D prioritization. Clinical and regulatory hurdles for adult VADs remain high (Class III device pathways in key markets). Firms should prioritize projects with clear de-risking milestones — e.g., design controls that address stroke and hemocompatibility endpoints — and allocate resources to robust real-world evidence generation alongside randomized data where feasible.
-
M&A and partnership timing. High market concentration and durable incumbent advantages mean that acquisitive strategies should be surgical: target gap-filling capabilities (control systems, battery tech, remote monitoring) and regional market access enablers rather than broad portfolio buyouts.
Market structure and competitive dynamics
The adult VAD market remains highly concentrated: the top three companies account for the overwhelming majority of global revenue, with the top five collectively representing well over 90% market share. This concentration produces both stability and high barriers to entry — incumbent clinical evidence, hospital relationships, and comprehensive service networks are meaningful competitive moats.
Key competitive themes for 2026:
-
Evidence as a differentiator. Recent long-term clinical data — including five-year outcomes from leading LVAD trials — are being used to justify premium pricing and broaden indications. Companies that can pair favorable clinical performance with lower total cost of care will have the strongest uptake in destination therapy populations.
-
Service and life-cycle revenue. As devices mature, hospitals and health systems place greater value on predictable consumables, controller upgrades, and remote monitoring services. Firms that convert devices into multi-year service relationships expand their TAM beyond the implant event.
-
Regulatory and recall dynamics. Past device advisories and long lead times for approvals shape hospital procurement behavior. Players that can demonstrate strong post-market surveillance, transparent corrective action plans, and rapid training capabilities gain trust in procurement committees.
Company-level positioning: a tactical read for 2026
-
Abbott Laboratories. Abbott’s HeartMate family remains a reference standard in adult LVAD therapy. Recent long-term trial results published by Abbott reinforce durable outcomes that support both bridge-to-transplant and destination therapy positioning. For Abbott, the 2026 playbook centers on extending system-level services and optimizing cost-per-quality-adjusted-life-year narratives to fortify reimbursement talks.
-
Medtronic. The ongoing implications of prior HVAD advisory actions continue to influence Medtronic’s strategic posture. The company’s pathway to reestablish a centrifugal-flow presence in certain markets will depend on demonstrable engineering and post-market governance improvements; partnerships to rebuild clinician trust are likely to be a near-term priority.
-
LivaNova PLC. LivaNova’s recent CE Mark activities for its next-generation centrifugal platform position it as a credible challenger in Europe. Expect an aggressive commercialization phase in 2026 focused on clinician training programs and real-world registries to accelerate adoption.
-
Berlin Heart GmbH. With renewed controller platforms and incremental improvements in usability and battery performance, Berlin Heart is focused on servicing distinct clinical niches, including biventricular support and shorter-term external systems. Their value proposition in Europe is anchored on modular support and rapid deployment for acute care centers.
-
Syncardia Systems. The Total Artificial Heart remains a specialized alternative for biventricular failure patients ineligible for VADs. Syncardia’s commercialization strategy hinges on targeted referral networks and reinforced transplant center partnerships to maintain relevance in a narrow but clinically critical segment.
Regulatory and reimbursement tailwinds and headwinds
Adult VADs are regulated as high-risk Class III devices in major markets, requiring rigorous premarket and post-market strategies. The European MDR framework and FDA PMA expectations continue to raise the bar for clinical and post-market evidence. Simultaneously, reimbursement policy updates are reshaping hospital economics: coding and payment reforms in 2024–2025 (including procedural code updates and DRG-level payment clarity) affect per-case economics and may change the attractiveness of destination therapy pathways versus transplantation.
For 2026 planning, companies must integrate regulatory timelines and payer engagement early in program design. Tactical actions include building targeted HEOR dossiers tied to specific DRG and CPT updates, preparing value dossiers for payers that quantify downstream savings, and designing post-market surveillance to satisfy Notified Body and FDA expectations while capturing real-world effectiveness.
What PW Consulting’s report delivers to decision-makers
Our study is intentionally built to be operational. Key deliverables include:
-
Market sizing and three-scenario forecasts (conservative, base, and aggressive) covering 2026–2032 with sensitivity analyses for pricing, utilization, and reimbursement shocks.
-
Hospital adoption modeling that links clinical pathway shifts (bridge-to-transplant vs. destination therapy) to procedure volumes and service revenue potential, with downloadable calculators for scenario testing.
-
Competitive landscaping that profiles incumbent and challenger strategies, including clinical assets, regulatory status, supply-chain dependencies, and potential consolidation targets.
-
Regulatory and reimbursement playbooks tailored for the U.S. and EU, mapping PMA/Notified Body timelines, real-world evidence requirements, DRG/CPT implications, and payer negotiation tactics.
-
Go-to-market roadmaps and implementation checklists for 12–24 month horizons, focused on clinician training, hospital procurement cycles, service deployment, and post-market surveillance.
-
Risk-and-opportunity heatmaps that quantify likelihood and impact across clinical, regulatory, reimbursement, and supply-chain axes to prioritize mitigation investments.
How to use the report in 2026 decision cycles
-
Board-level strategy: Use the concentration metrics and scenario forecasts to arbitrate between organic R&D and targeted M&A — the report quantifies payback periods under multiple uptake curves.
-
Commercial planning: Align launch sequencing with payer negotiation windows; leverage our cost-of-care models to demonstrate value in destination therapy populations to hospital formulary committees.
-
Regulatory sequencing: Build incremental evidence-generation plans that synchronize with PMA/CE timelines to avoid market-entry gaps and shorten time-to-reimbursement.
-
Operations and supply chain: Prioritize supplier dual-sourcing and controller battery life improvements; our operational stress tests reveal where shortfalls are most likely during scaled commercialization.
Why PW Consulting’s market intelligence is different
We combine proprietary procedure-level models with primary interviews across implanting centers, payer gatekeepers, and clinical opinion leaders. Our approach blends clinical outcomes data, device-level lifecycle economics, and regulatory pathway stress-testing into a single decision-grade package. Importantly, the report’s appendices include de-identified hospital-level adoption curves and a reproducible model that clients can adapt to their internal assumptions.
Signal summary and next steps
The adult VAD market in 2026 is neither a high-growth breakout nor a static fixture — it is a mature, concentrated market with discrete opportunities for differentiation through clinical evidence, lifecycle services, and payer-aligned value propositions. Companies that invest in targeted innovation, reinforce regulatory and post-market infrastructure, and translate clinical performance into hospital and payer value will command disproportionate returns.
PW Consulting’s full Worldwide Adult Ventricular Assist Device Market report contains the granular segmentation, regional deployment models, and executable playbooks omitted here to preserve the report’s commercial integrity. To access the complete intelligence package — including the full segmentation tables, downloadable scenario models, and a prioritized M&A target list — contact PW Consulting or visit our report page to download the executive package.
For detailed analysis of this topic, please visit the official page: Worldwide Adult Ventricular Assist Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Used & Refurbished Telehandler Market Valued at USD 3,185.5 Million in 2025; Strong Growth Outlook to 2032
By pmarketresearch, 2026-07-15
PW Consulting Releases Strategic Preview: Worldwide Used and Refurbished Telehandler Market Report — Critical Intelligence for 2026 Decision-Making
PW Consulting today publishes an executive preview of its forthcoming Worldwide Used and Refurbished Telehandler Market report — a practitioner-focused study produced to inform capital allocation, channel strategy, and operational priorities through the 2026 planning window and beyond. Built from a five-year historical base and a seven-year forecast horizon, the research translates durable market trends, competitive dynamics, and regulatory pressure points into concrete choices executives must make in 2026.
Worldwide Used and Refurbished Telehandler Market
Why this report matters in 2026
The used and refurbished telehandler market is moving from a fragmented, transaction-driven sector toward increasingly formalized lifecycle management across manufacturers, dealers, and independent refurbishers. Our analysis shows the market expanding at a compound annual growth rate (CAGR) of 5.81% across the 2026–2032 forecast period. From a 2025 baseline of approximately USD 3.19 billion, PW Consulting projects steady expansion through 2032 as operators prioritize cost-efficiency, rental flexibility, and low-carbon upgrade pathways.
Worldwide Used and Refurbished Telehandler Market
For executives setting 2026 budgets, three realities should guide decisions now: 1) used/refurbished inventory and rental options are becoming core competitive levers, 2) component and regulatory headwinds will reshape total cost of ownership assumptions, and 3) value capture is shifting toward those who own the end-to-end refurbishment capability or build proprietary lifecycle services with digital provenance.
Worldwide Used and Refurbished Telehandler Market
Market snapshot — growth, concentration and momentum
-
Historical momentum: The market expanded materially between 2020 and 2025, reflecting both new-equipment cycles and a growing preference for refurbished units in cost-sensitive sectors.
-
2025 baseline and outlook: The market size in 2025 is an estimated USD 3,185.5 million. Under PW Consulting’s base case the market reaches approximately USD 4,730 million by 2032, driven by steady demand for mid-life equipment and increasing OEM-sponsored certified pre-owned programs.
-
Market structure: Concentration remains moderate. The top three players account for roughly one-third of market share while the top five approach the mid-forties, indicating meaningful room for regional specialists and independent refurbishers to create niche advantage.
What the report contains — practical, decision-ready deliverables
PW Consulting’s full report is intentionally operational. It is built to be used by strategy teams, M&A groups, dealer networks, and refurbishing operators. Highlights include:
-
Proprietary market-sizing model with historical reconciliations (2020–2025) and granular scenario projections for 2026–2032.
-
Actionable go-to-market playbooks for OEMs, dealers, and independent refurbishers — including margin archetypes, refurbishment cost buckets, and recommended warranty and certification thresholds that materially affect resale pricing and uptake.
-
Channel economics toolkit that quantifies trade-offs among sale, rental, and certified pre-owned programs (CPO), with sensitivity to utilization and cycle time assumptions.
-
Regulatory and input-cost risk matrix, linking steel and component price scenarios, tariff exposures, and operator training/compliance forces to balance sheet and P&L outcomes.
-
Competitive benchmarking: our qualitative and quantitative assessment of leading firms and their strategic posture in used and refurbished telehandlers.
Near-term dynamics influencing 2026 planning
Executives need to integrate near-term market signals into their 2026 plans rather than treat them as one-off events. Three dynamics are especially material:
-
Input-cost volatility and tariff risk: Steel price stabilization in 2025 reduced one source of uncertainty, but tariff actions and regional supply constraints have reintroduced cost risk. Those who internalize refurbishment cost structures, source locally where possible, or hedge component supply gain a competitive edge.
-
Regulatory tightening around operator certification and documentation: Recent regulatory updates increase the compliance burden for sellers of used and refurbished telehandlers. Digital provenance — recording service history, inspection checklists, and training compliance — is rapidly becoming a purchase criterion for large contractors.
-
Rental and access-over-ownership demand: Rental models continue to grow as contractors seek to reduce fixed capital. Our research finds rental and subscription offerings materially alter lifecycle profitability and accelerate fleet refresh cycles, creating opportunities for refurbishers to secure high-quality feedstock.
Competitive landscape — who matters and why
Incumbent OEMs and large equipment groups are both consolidating aftermarket channels and scaling certified programs. Our competitive review profiles key industry players, how they source and certify used inventory, and the strategic implications for market participants:
-
JCB (Rocester, UK): Deep dealer networks that convert trade-ins into certified units; strong positioning in construction and agriculture through established refurbishment pathways.
-
Caterpillar Inc. (Irving, TX): Institutionalized used-equipment programs with global dealer oversight — a benchmark for warranty-backed refurb models and macro-scale parts logistics.
-
Manitou Group (Ancenis, France): Focus on platform harmonization and regional inventory rotation to match cross-border demand streams.
-
JLG Industries / Oshkosh Corporation (PA): Rental-fleet insights and compact model specialization create resilience in cyclical North American markets.
-
Merlo, Dieci, Terex (Genie), Bobcat/Doosan, Liebherr, CNH Industrial, Wacker Neuson, Haulotte and CLAAS: Each brings differentiated strengths — from rotating telehandler expertise to integrated agricultural offerings — shaping diverse competitive plays in refurbishment, certification, and resale channels.
Across these players, three strategic moves repeat: control of the parts ecosystem, investments in digital inspection and certification, and the commercialization of rental/CPO bundles that lock customers into service-led recurring revenue.
Scenarios and strategic implications for 2026
PW Consulting develops three plausible scenarios in the full study to stress-test strategies for 2026. Executives should use these to prioritize near-term investments:
-
Efficiency-driven consolidation: OEMs and large dealers scale certified refurbishment to achieve higher resale yields; independent refurbishers focus on specialization and regional speed-to-market.
-
Regulation-and-cost squeeze: Elevated tariffs and certification costs compress margins for low-trust sellers; digital provenance and warranty-backed sales become the differentiator.
-
Rental-first substitution: Greater customer preference for access over ownership accelerates fleet churn, creating predictable feedstock for refurbishment but increasing pressure on turn times and logistics capability.
Practical moves for each stakeholder
-
OEMs: Prioritize standardized inspection protocols, invest in certification branding, and develop trade-in guarantees to capture upstream feedstock and downstream aftermarket margin.
-
Dealers: Optimize inventory velocity through blended rental/CPO offerings; implement digital inspection and service histories to support premium pricing.
-
Independent refurbishers: Specialize in rapid turn and customized refurb packages; negotiate long-term feedstock agreements with rental houses and contractors.
-
Rental companies and fleet operators: Use predictive-maintenance data to maximize lifecycle value and generate higher-quality used inventory for resale or certified programs.
Data-driven signals you can act on now
From our proprietary modeling and interviews with OEMs, dealers and refurbishment operators, PW Consulting recommends three immediate steps for 2026 planning:
-
Build a primary-feedstock strategy: Secure sources (trade-ins, rental de-fleets, lease returns) with contractual clarity on condition standards and delivery timing.
-
Invest in digital provenance and compliance workflows: With operator certification and inspection scrutiny increasing, buyers will pay a premium for verifiable histories.
-
Model rental-led scenarios explicitly in capital allocation: The rental expansion trend changes asset-utilization math and the required working capital for holding inventory.
About assumptions, risks and where to find the details
Our baseline assumes continued demand for used/refurbished telehandlers across construction, agriculture, and industrial logistics, tempered by input-cost fluctuations and regulatory tightening. Key risk vectors include raw-material tariff shifts, accelerated depreciation pressures during a rental surge, and rapid adoption of electrification or alternative drivetrains not yet standardized in the secondary market.
PW Consulting’s “trailer” approach: this press release highlights the strategic insights and structural takeaways executives need to assess 2026 choices. The full report contains the complete segmentation matrices, granular regional and application-level forecasts, refurbishment-cost curves, warranty-sensitivity analyses, and proprietary demand elasticities — all the detailed inputs you’ll need to implement the strategies summarized here.
How to use this intelligence for 2026
Senior leaders should incorporate the report into three immediate processes: annual planning (budget allocations to refurbishment and certification), M&A screening (target scorecards for refurbishers and rental portfolios), and channel redesign (dealer incentives for certified resale and trade-in guarantees). In fast-moving market windows, the ability to translate used-equipment flows into predictable, warranty-backed revenue defines who wins aftermarket economics.
Call to action
To access the full Worldwide Used and Refurbished Telehandler Market report — including detailed tables, model files, and the competitive scorecards referenced above — visit our report page. PW Consulting’s research team is also available for bespoke briefings to translate these findings into tailored 2026 strategies, scenario workshops, and implementation roadmaps.
For detailed analysis of this topic, please visit the official page: Worldwide Used and Refurbished Telehandler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com