

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide JAK Inhibitors Market to Hit USD 40,565.2 Million by 2032, Growing at a 14.01% CAGR

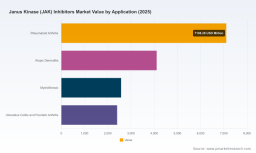
PW Consulting Strategic Brief: Worldwide Janus Kinase (JAK) Inhibitors Market — A 2026 Playbook for Executives
Executive snapshot
The JAK inhibitors sector is entering a decisive chapter. Our new Worldwide Janus Kinase (JAK) Inhibitors Market report (base year 2025, forecast period 2026–2032) maps the pathway for commercial, R&D, and M&A decisions that will define winners and laggards over the next strategic horizon. The market reached an estimated USD 16,200 Million in 2025 and is projected to expand at a robust compound annual growth rate (CAGR) of approximately 14.0% through 2032 — reaching a market size in excess of USD 40 billion by the end of the forecast window. This trajectory underscores attractive upside, but the route is uneven: concentrated competition, regulatory headwinds, patent cliffs, and supply vulnerabilities mean that timing and tactical choices in 2026 will materially affect long-term positioning.
Worldwide Janus Kinase (JAK) Inhibitors Market
Why this report matters for 2026 planning
-
Actionable foresight: Our models translate the macro growth trajectory into decision-ready scenarios — from conservative reimbursement outcomes to accelerated label expansions — enabling CFOs and BD teams to establish near-term investment thresholds.
Worldwide Janus Kinase (JAK) Inhibitors Market -
Competitive clarity: The market is highly concentrated among a handful of global players. Incumbents with established brands and broad indications maintain scale advantages, while specialty players and newer entrants pursue niche differentiation through selectivity profiles and adjunct targets. Understanding relative competitive moats and vulnerability windows is essential to craft either defensive or disruptive moves.
Worldwide Janus Kinase (JAK) Inhibitors Market -
Risk calibration: The market’s upside is coupled with discrete downside events that can rapidly reshuffle value — patent expiries, regulatory safety advisories, API supply shocks, and payer policy shifts. Our scenario matrices quantify potential revenue and margin impacts across these vectors, enabling stress-tested 2026 budgets.
-
Commercial playbooks: For 2026 launches and label expansions, the report supplies go-to-market playbooks that align clinical positioning, pricing, and patient support to payer pathways — including Medicare Part D dynamics — to optimize uptake under constrained access environments.
What the report contains — practical intelligence for immediate use
-
Market sizing and forecast engine (2020–2032) with base-year reconciliation and sensitivity toggles for key drivers such as indication uptake, pricing erosion, and biosimilar/generic entry timing.
-
Concentration and competitive landscape assessment, including an evidence-backed view of incumbent strengths, pipeline vectors, and white-space opportunities for selective JAK agents versus broader pan-JAK compounds.
-
Regulatory and safety scenario planning that models the commercial impact of label revisions, boxed warnings, and country-specific reimbursement policies.
-
Clinical and pipeline mapping tied to commercial potential — trial attrition profiles, expected approval windows, and prioritization matrices for indications with the highest near-term commercial leverage.
-
Supply-chain risk heatmaps and mitigation playbooks: API concentration analysis, dual-sourcing strategies, and inventory management protocols for 2026 continuity.
-
M&A and partnership blueprints: valuation frameworks for licensing, bolt-on acquisitions, and co-development deals that reflect time-to-market and incremental revenue accretion under multiple regulatory scenarios.
-
Payer engagement templates and real-world evidence (RWE) approaches designed to offset safety concerns and secure formulary access in priority markets.
Competitive dynamics — who matters and why
The competitive field is dominated by established Big Pharma and specialized biotech players that have converted clinical assets into commercial franchises. Key firms play different strategic roles:
-
Pfizer: An incumbent with a broad indication footprint and recent pediatric label expansion activity. Approaches to lifecycle management, especially as core patents approach expiration, will be pivotal to sustaining revenue density.
-
Incyte: Notable for products targeting hematologic and dermatologic niches; recent approvals of topical and cutaneous formulations demonstrate a strategy of expanding route-of-administration options to capture incremental patient cohorts.
-
Eli Lilly: Leveraging cross-indication approvals and pediatric label extensions to broaden the commercial runway for selective JAK agents; R&D synergies and scale commercialization are central to its playbook.
-
AbbVie: Driving rapid indication expansion into inflammatory bowel disease and pediatric populations; ability to combine clinical breadth with payer contracting strength is a differentiator.
-
Gilead (through partnerships): Access to selected markets via strategic alliances underscores a playbook that mixes partnership economics with targeted commercial deployment.
-
Conatus/Roivant: Represents the innovation frontier — next-generation selective molecules and combination approaches that, if clinical outcomes validate, could reshape therapeutic differentiation.
Recent regulatory and label events through 2024–2025 (including pediatric expansions and topical approvals) have created short-term commercial inflection points. Yet they exist alongside enduring safety constraints — the industry continues to operate under enhanced boxed safety warnings established in recent years — which means clinical differentiation and robust risk mitigation strategies remain central to market success.
Market structure and concentration
The sector exhibits significant concentration: a small set of global firms capture the lion’s share of market revenues, creating a marketplace characterized by scale advantages in distribution, contracting, and clinical evidence generation. This concentration creates both barriers and openings — incumbents can leverage scale to defend pricing and access, while agile challengers can win by offering compelling differentiation (e.g., improved selectivity, superior safety profile, or novel delivery formats).
Key strategic imperatives for 2026
-
Prioritize lifecycle management before patent cliffs: With major brands facing patent expiration pressures, firms should accelerate authorized generic strategies, portfolio extensions (route, indication, pediatric filings), and licensing deals to slow revenue erosion.
-
Invest in safety-driven evidence: Robust post-marketing safety programs and RWE that contextualize cardiovascular, malignancy, and thrombotic risks will be decisive for formulary positioning and patient confidence.
-
De-risk supply chains now: API sourcing concentration has led to episodic shortages; dual-sourcing, strategic inventory buffers, and supplier co-investment are practical mitigations that should be budgeted in 2026 operating plans.
-
Segment commercial approaches by selectivity profile: Distinct clinical and payer messaging is required for JAK1-selective agents versus broader-spectrum molecules; sales and medical affairs teams must be retooled accordingly.
-
Explore targeted M&A and alliances: For companies lacking scale, bolt-on assets that close clinical gaps or add differentiated delivery platforms can accelerate access; for incumbents, divestiture and partnering can optimize capital allocation.
-
Embed dynamic pricing models: Scenario-based pricing that ties to real-world outcomes and indication-specific value will help balance access with margin preservation as competitive entry increases.
Risk scenarios to model in your 2026 plan
-
Accelerated generic or biosimilar erosion following patent expiry in key markets — model up-front revenue loss vs. retained franchise value via authorized generics/licensing.
-
Regulatory tightening or expanded safety labeling — quantify the impact on penetration rates and payer mix across plausible severities.
-
Supply disruptions leading to temporary shortages — simulate revenue disruption at country and channel levels, and the cost of mitigation strategies.
-
Faster-than-anticipated adoption of next-generation selective agents — estimate share-shift timelines and required commercial investments to defend incumbent positions.
How companies should use the report
-
Corporate strategy teams: Use the forecast engine to set revenue targets, allocate R&D budgets, and evaluate divestiture or acquisition candidates.
-
Commercial leaders: Translate indication-level adoption curves and payor scenarios into salesforce sizing, promotional mix, and patient-support investments for 2026 launches or expansions.
-
Business development and licensing: Leverage our valuation frameworks to price deals, structure milestone payments, and negotiate co-commercialization terms that reflect regulatory risk and time-to-market.
-
Supply-chain and operations: Apply our supplier risk scores and mitigation playbooks to secure continuity and minimize fulfillment-related revenue leakage.
Conclusion — the 2026 imperative
The JAK inhibitors market offers compelling growth, with an expected market value moving from the mid-teens (USD Million) in 2025 to north of USD 40 billion by 2032, underpinned by accelerating adoption across multiple indications and ongoing product innovation. Yet the path to capture this upside is neither simple nor linear. 2026 is a window for decisive actions: fortify supply, shore up lifecycle strategies ahead of patent expiries, invest in safety evidence, and pursue targeted partnerships. Firms that implement a calibrated mix of defensive and selective offensive moves will convert the favorable macro growth into sustainable competitive advantage.
Access the full analysis
This briefing highlights the strategic implications of our findings while intentionally omitting detailed subsegment tables and granular regional/application splits to encourage direct access to the full report. PW Consulting’s Worldwide Janus Kinase (JAK) Inhibitors Market report provides the complete dataset, downloadable models, and bespoke scenario toolkits to operationalize the recommendations above. For inquiries and to obtain the full report, contact PW Consulting’s life sciences practice or visit our website.
For detailed analysis of this topic, please visit the official page: Worldwide Janus Kinase (JAK) Inhibitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com