

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Glaucoma Diagnostics Market valued at USD 2,674.0 Million in 2025, set to reach USD 3,765.1 Million by 2032 at a 5.01% CAGR — OCT leads with USD 1,135.96 Million

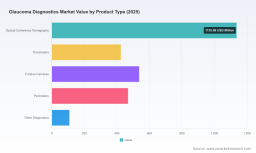
Worldwide Glaucoma Diagnostics Market — Strategic Imperatives for 2026
PW Consulting today releases a strategic briefing drawn from our forthcoming Worldwide Glaucoma Diagnostics Market report (base year 2025, historical window 2020–2025, forecast 2026–2032). The market crossed an important threshold in 2025, reaching approximately USD 2,674 Million, and is projected to expand at a compound annual growth rate (CAGR) of 5.01% through the 2026–2032 forecast horizon. These high‑level dynamics mask differentiated opportunity pockets and risk vectors that will determine winners and laggards in the next strategic planning cycle — the analysis below explains why 2026 is the year to act and what capabilities matter most.
Worldwide Glaucoma Diagnostics Market
Why this report matters for 2026 decision-makers
Executives setting 2026 budgets face a convergence of forces: sustainably rising demand driven by demographic and screening tailwinds; rapid software and AI maturation that changes product value propositions; tighter regulatory and reimbursement controls for device classes; and selective consolidation among leading suppliers. Our report translates those macro realities into operational choices: where to prioritize R&D, which product adjacencies to pursue (hardware, software, service), how to design field trials and pilots that accelerate payer acceptance, and what inorganic moves will unlock scale without destroying margins.
Worldwide Glaucoma Diagnostics Market
What the report contains — practical, executable intelligence
- Proprietary market forecast model (2026–2032) with scenario sensitivity — base, upside, and downside — calibrated to observed demand elasticities and technology substitution rates.
- Multi‑axis segmentation (by geography, product family, and end‑user) with demand drivers, adoption curves and friction points for each cell. Note: headline totals and growth rates are published here; detailed cell-level values are reserved for the full report to preserve the strategic “teaser” intent.
- Competitive landscaping and benchmarking including CR3 and CR5 concentration metrics, supplier positioning maps, and capability heatmaps for clinical accuracy, peripheral enablement (connectivity/telehealth), and service economics.
- Regulatory and reimbursement playbooks tied to product classes (including device classification impacts and CPT‑level implications), plus a standardized checklist to accelerate 510(k)/CE/other filings.
- Commercial GTM (go‑to‑market) blueprints for incumbent OEMs, software-first entrants, and private equity acquirers — including channel strategies, pricing archetypes, and pilot design templates for payer engagement.
- M&A and partnership scorecards identifying target archetypes, expected value creation levers, and integration risk factors.
- Field‑tested buyer persona profiles and procurement flows for ophthalmic clinics, hospitals, and diagnostic centers, together with decision‑criteria matrices used by buyers during capital allocations.
- Implementation and change management playbooks for deploying hybrid diagnostic stacks (device + AI + cloud) in real-world clinical operations.
Strategic implications: six priorities for 2026
- Make software a first-class product pillar. Hardware alone increasingly commoditizes. Clinical AI modules and analytics platforms that materially shorten the diagnostic pathway or improve longitudinal monitoring create differentiation and recurring revenue potential.
- Invest selectively in home and remote monitoring capabilities. Clinical studies and product launches over the last 24 months validate home tonometry and portable fundus imaging as credible extensions of practice workflows. Building robust connectivity, data governance and reimbursement playbooks now will accelerate adoption.
- Design trials for payers, not just regulators. Regulatory clearance ensures market access; payer acceptance secures reimbursement. Trials that quantify clinical‑economic value (e.g., avoided sight‑loss events, clinic visit offsets) unlock scale in institutional channels.
- Prioritize interoperability and lifecycle service economics. Buyers increasingly evaluate total cost of ownership (TCO). Modular, upgradeable platforms with clear service and consumable economics win in procurement competitions.
- Use M&A as capability shortcut, not revenue shortcut. Acquirers should target gaps in analytics, data orchestration, or channel presence rather than incremental device portfolios that amplify integration complexity.
- Embed regulatory change monitoring into product roadmaps. Device class reclassifications and standard updates materially affect time to market and cost of compliance. A proactive regulatory intelligence function reduces surprise delays.
Competitive landscape — who’s shaping the market
The diagnostic ecosystem is a mix of legacy optical OEMs, specialty device makers, and agile digital entrants. Market concentration is meaningful: the top three suppliers capture a near‑majority share of industry revenue, and the top five approach two‑thirds of the market by revenue — a structure that favors scale and integrated product bundles. Below we summarize the strategic roles of core incumbents and recent moves to watch in 2024–2025.
Worldwide Glaucoma Diagnostics Market
- Zeiss (Germany) — A leader in OCT platforms and integrated measurement systems, with continued investment in analytics. In late 2025 the company refreshed its OCT family with enhanced glaucoma analytics, signaling an ongoing shift toward bundled hardware‑software propositions. (See Zeiss Meditec for product details.)
- Heidelberg Engineering (Germany) — Recognized for retinal imaging and OCT platforms with focused glaucoma modules; recent software updates emphasize longitudinal progression detection, strengthening clinician workflows for follow‑up and triage.
- Topcon (Japan) — Multi‑modal portfolio including swept‑source OCT and visual field analyzers; regulatory milestones such as recent FDA 510(k) clearances for AI‑enabled visual field devices broaden market access in major geographies.
- Nidek (Japan) and Haag‑Streit (Switzerland) — Strong presence in tonometry and perimetry respectively; engineering depth in clinical ergonomics and instrument reliability remains their competitive mooring.
- Reichert Technologies (USA), Canon Medical Systems (Japan), Kowa (Japan), iCare (Finland) — Each brings differentiated strengths: corneal biomechanics, non‑contact tonometry, fundus imaging, and home monitoring solutions respectively. Notably, clinical validation and wireless connectivity innovations have been prominent in their recent product updates.
- Carelon Medical Technologies (USA) — A representative of camera + AI entrants with portable fundus imaging solutions designed for decentralized screening and community care models.
Recent public developments underscore strategic vectors to watch: software refreshes that embed AI‑driven progression analytics; FDA clearances that lower regulatory friction for AI‑enabled visual field products; wireless and home‑monitoring device launches; and clinical studies that validate remote IOP monitoring. Collectively, these moves compress time‑to‑value for analytics layers and alter purchasing criteria in 2026.
Regulatory and reimbursement dynamics that will determine adoption speed
- Regulatory classification matters: non‑contact tonometers are regulated as Class II devices in the U.S., requiring 510(k) premarket notification — an important gating factor for device roadmaps targeting ambulatory settings.
- Reimbursement archetypes remain fragmented but actionable. Representative CPT pathways exist for optic nerve imaging and visual field testing; navigating the local reimbursement landscape — and constructing cost‑offset narratives for payers — materially accelerates deployment.
- Standards such as ISO 8619:2019 for Goldmann‑type applanation tonometers set performance baselines that procurement committees use to shortlist technology vendors.
How leading buyers should use this intelligence in 2026
- Health system CMOs and purchasing directors: use the report to map supplier bundles against your patient volume and longitudinal follow‑up needs; prioritize contracts that reduce clinic visit burden through validated remote monitoring.
- Device OEMs and software companies: overlay your product roadmap against the report’s adoption curves to time product launches, pilot geographies and reimbursement dossiers.
- Private equity and corporate development teams: apply the M&A scoreboard and valuation sensitivity tables to shortlist targets where synergies in distribution or analytics materially compress payback periods.
- Regulatory and reimbursement teams: use the regulatory checklists and payer trial templates to design studies that generate both clearance documents and payer‑facing economic dossiers.
Why PW Consulting’s analysis is distinct
Our methodology combines bottom‑up device shipment modeling, clinician and procurement interviews across major healthcare systems, hands‑on evaluation of device performance claims, and reimbursement scenario testing. We validate forecasts through multi‑disciplinary triangulation — clinical, economic and regulatory — and produce a downloadable financial model that lets clients stress‑test strategic options. In keeping with the “prequel” ethos, this briefing highlights findings that are immediately actionable while reserving the full cell‑level datasets and proprietary vendor scoring matrices for report subscribers.
Next steps — where to get the full intelligence
For C‑suite teams, product leads and investors preparing 2026 strategies, the full report provides the granular market splits, country‑level demand curves, vendor revenue and share estimates, and a ready‑to‑use financial model. Those materials are designed to be plugged directly into board materials and investment memos to shorten decision cycles. Visit PW Consulting’s report page to access the full dataset, annexes, and licensing options for our interactive forecasting model.
In a market growing at a steady mid‑single digit CAGR, 2026 will favor organizations that pair clinical credibility with software economics, and that can translate regulatory clearances into payer‑backed, scalable care pathways. The moment to align strategy with execution is now; our full report shows exactly how.
For detailed analysis of this topic, please visit the official page: Worldwide Glaucoma Diagnostics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com