

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Used & Refurbished Telehandler Market Valued at USD 3,185.5 Million in 2025; Strong Growth Outlook to 2032

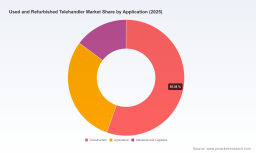
PW Consulting Releases Strategic Preview: Worldwide Used and Refurbished Telehandler Market Report — Critical Intelligence for 2026 Decision-Making
PW Consulting today publishes an executive preview of its forthcoming Worldwide Used and Refurbished Telehandler Market report — a practitioner-focused study produced to inform capital allocation, channel strategy, and operational priorities through the 2026 planning window and beyond. Built from a five-year historical base and a seven-year forecast horizon, the research translates durable market trends, competitive dynamics, and regulatory pressure points into concrete choices executives must make in 2026.
Worldwide Used and Refurbished Telehandler Market
Why this report matters in 2026
The used and refurbished telehandler market is moving from a fragmented, transaction-driven sector toward increasingly formalized lifecycle management across manufacturers, dealers, and independent refurbishers. Our analysis shows the market expanding at a compound annual growth rate (CAGR) of 5.81% across the 2026–2032 forecast period. From a 2025 baseline of approximately USD 3.19 billion, PW Consulting projects steady expansion through 2032 as operators prioritize cost-efficiency, rental flexibility, and low-carbon upgrade pathways.
Worldwide Used and Refurbished Telehandler Market
For executives setting 2026 budgets, three realities should guide decisions now: 1) used/refurbished inventory and rental options are becoming core competitive levers, 2) component and regulatory headwinds will reshape total cost of ownership assumptions, and 3) value capture is shifting toward those who own the end-to-end refurbishment capability or build proprietary lifecycle services with digital provenance.
Worldwide Used and Refurbished Telehandler Market
Market snapshot — growth, concentration and momentum
-
Historical momentum: The market expanded materially between 2020 and 2025, reflecting both new-equipment cycles and a growing preference for refurbished units in cost-sensitive sectors.
-
2025 baseline and outlook: The market size in 2025 is an estimated USD 3,185.5 million. Under PW Consulting’s base case the market reaches approximately USD 4,730 million by 2032, driven by steady demand for mid-life equipment and increasing OEM-sponsored certified pre-owned programs.
-
Market structure: Concentration remains moderate. The top three players account for roughly one-third of market share while the top five approach the mid-forties, indicating meaningful room for regional specialists and independent refurbishers to create niche advantage.
What the report contains — practical, decision-ready deliverables
PW Consulting’s full report is intentionally operational. It is built to be used by strategy teams, M&A groups, dealer networks, and refurbishing operators. Highlights include:
-
Proprietary market-sizing model with historical reconciliations (2020–2025) and granular scenario projections for 2026–2032.
-
Actionable go-to-market playbooks for OEMs, dealers, and independent refurbishers — including margin archetypes, refurbishment cost buckets, and recommended warranty and certification thresholds that materially affect resale pricing and uptake.
-
Channel economics toolkit that quantifies trade-offs among sale, rental, and certified pre-owned programs (CPO), with sensitivity to utilization and cycle time assumptions.
-
Regulatory and input-cost risk matrix, linking steel and component price scenarios, tariff exposures, and operator training/compliance forces to balance sheet and P&L outcomes.
-
Competitive benchmarking: our qualitative and quantitative assessment of leading firms and their strategic posture in used and refurbished telehandlers.
Near-term dynamics influencing 2026 planning
Executives need to integrate near-term market signals into their 2026 plans rather than treat them as one-off events. Three dynamics are especially material:
-
Input-cost volatility and tariff risk: Steel price stabilization in 2025 reduced one source of uncertainty, but tariff actions and regional supply constraints have reintroduced cost risk. Those who internalize refurbishment cost structures, source locally where possible, or hedge component supply gain a competitive edge.
-
Regulatory tightening around operator certification and documentation: Recent regulatory updates increase the compliance burden for sellers of used and refurbished telehandlers. Digital provenance — recording service history, inspection checklists, and training compliance — is rapidly becoming a purchase criterion for large contractors.
-
Rental and access-over-ownership demand: Rental models continue to grow as contractors seek to reduce fixed capital. Our research finds rental and subscription offerings materially alter lifecycle profitability and accelerate fleet refresh cycles, creating opportunities for refurbishers to secure high-quality feedstock.
Competitive landscape — who matters and why
Incumbent OEMs and large equipment groups are both consolidating aftermarket channels and scaling certified programs. Our competitive review profiles key industry players, how they source and certify used inventory, and the strategic implications for market participants:
-
JCB (Rocester, UK): Deep dealer networks that convert trade-ins into certified units; strong positioning in construction and agriculture through established refurbishment pathways.
-
Caterpillar Inc. (Irving, TX): Institutionalized used-equipment programs with global dealer oversight — a benchmark for warranty-backed refurb models and macro-scale parts logistics.
-
Manitou Group (Ancenis, France): Focus on platform harmonization and regional inventory rotation to match cross-border demand streams.
-
JLG Industries / Oshkosh Corporation (PA): Rental-fleet insights and compact model specialization create resilience in cyclical North American markets.
-
Merlo, Dieci, Terex (Genie), Bobcat/Doosan, Liebherr, CNH Industrial, Wacker Neuson, Haulotte and CLAAS: Each brings differentiated strengths — from rotating telehandler expertise to integrated agricultural offerings — shaping diverse competitive plays in refurbishment, certification, and resale channels.
Across these players, three strategic moves repeat: control of the parts ecosystem, investments in digital inspection and certification, and the commercialization of rental/CPO bundles that lock customers into service-led recurring revenue.
Scenarios and strategic implications for 2026
PW Consulting develops three plausible scenarios in the full study to stress-test strategies for 2026. Executives should use these to prioritize near-term investments:
-
Efficiency-driven consolidation: OEMs and large dealers scale certified refurbishment to achieve higher resale yields; independent refurbishers focus on specialization and regional speed-to-market.
-
Regulation-and-cost squeeze: Elevated tariffs and certification costs compress margins for low-trust sellers; digital provenance and warranty-backed sales become the differentiator.
-
Rental-first substitution: Greater customer preference for access over ownership accelerates fleet churn, creating predictable feedstock for refurbishment but increasing pressure on turn times and logistics capability.
Practical moves for each stakeholder
-
OEMs: Prioritize standardized inspection protocols, invest in certification branding, and develop trade-in guarantees to capture upstream feedstock and downstream aftermarket margin.
-
Dealers: Optimize inventory velocity through blended rental/CPO offerings; implement digital inspection and service histories to support premium pricing.
-
Independent refurbishers: Specialize in rapid turn and customized refurb packages; negotiate long-term feedstock agreements with rental houses and contractors.
-
Rental companies and fleet operators: Use predictive-maintenance data to maximize lifecycle value and generate higher-quality used inventory for resale or certified programs.
Data-driven signals you can act on now
From our proprietary modeling and interviews with OEMs, dealers and refurbishment operators, PW Consulting recommends three immediate steps for 2026 planning:
-
Build a primary-feedstock strategy: Secure sources (trade-ins, rental de-fleets, lease returns) with contractual clarity on condition standards and delivery timing.
-
Invest in digital provenance and compliance workflows: With operator certification and inspection scrutiny increasing, buyers will pay a premium for verifiable histories.
-
Model rental-led scenarios explicitly in capital allocation: The rental expansion trend changes asset-utilization math and the required working capital for holding inventory.
About assumptions, risks and where to find the details
Our baseline assumes continued demand for used/refurbished telehandlers across construction, agriculture, and industrial logistics, tempered by input-cost fluctuations and regulatory tightening. Key risk vectors include raw-material tariff shifts, accelerated depreciation pressures during a rental surge, and rapid adoption of electrification or alternative drivetrains not yet standardized in the secondary market.
PW Consulting’s “trailer” approach: this press release highlights the strategic insights and structural takeaways executives need to assess 2026 choices. The full report contains the complete segmentation matrices, granular regional and application-level forecasts, refurbishment-cost curves, warranty-sensitivity analyses, and proprietary demand elasticities — all the detailed inputs you’ll need to implement the strategies summarized here.
How to use this intelligence for 2026
Senior leaders should incorporate the report into three immediate processes: annual planning (budget allocations to refurbishment and certification), M&A screening (target scorecards for refurbishers and rental portfolios), and channel redesign (dealer incentives for certified resale and trade-in guarantees). In fast-moving market windows, the ability to translate used-equipment flows into predictable, warranty-backed revenue defines who wins aftermarket economics.
Call to action
To access the full Worldwide Used and Refurbished Telehandler Market report — including detailed tables, model files, and the competitive scorecards referenced above — visit our report page. PW Consulting’s research team is also available for bespoke briefings to translate these findings into tailored 2026 strategies, scenario workshops, and implementation roadmaps.
For detailed analysis of this topic, please visit the official page: Worldwide Used and Refurbished Telehandler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com