

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Non‑Thermal Food Processing Market Poised to Expand at a Robust 10% CAGR Through 2032

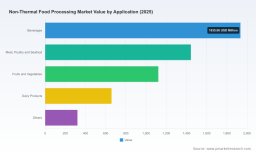
Worldwide Non‑Thermal Food Processing Market: Strategic Preview for 2026 Decisions
Executive snapshot
PW Consulting’s latest market study on Worldwide Non‑Thermal Food Processing (base year 2025) delivers a decision‑grade briefing designed to orient C‑suite leaders, corporate strategists, and capital allocators as they set priorities for 2026. The non‑thermal processing market has shown sustained expansion through the 2020–2025 historical window and is projected to grow at a compound annual growth rate (CAGR) of approximately 10.0% over our 2026–2032 forecast horizon. Underpinning this trajectory is an accelerating commercialization of High Pressure Processing (HPP), Pulsed Electric Fields (PEF), ultrasound and plasma solutions, and an increasingly tight interplay among regulation, ingredient sourcing and packaging innovation.
Worldwide Non-Thermal Food Processing Market
Why 2026 is the inflection point
-
Operational scaling is now the dominant challenge. Early adopters validated product quality and shelf‑life improvements; the next wave must prove cost‑efficient scale while meeting stringent food‑safety and cross‑border compliance requirements.
Worldwide Non-Thermal Food Processing Market -
Regulatory equivalence and acceptance have matured into a commercial enabler. Notably, regulatory frameworks in major markets have clarified that select non‑thermal modalities can meet pasteurization and microbial reduction standards, removing a prior source of ambiguity for exporters and brand owners.
Worldwide Non-Thermal Food Processing Market -
Supply‑chain pressure and input volatility are increasing the value of technologies that both minimize waste and preserve yield — creating differentiated ROI profiles across product categories and processing lines.
Market trajectory — what the headline numbers tell you
The market has moved from early validation to robust growth: after several years of compound expansion in the early 2020s, our base‑year analysis for 2025 shows a materially larger market relative to 2020, and our forecast to 2032 anticipates the market roughly doubling over the forecast window (currency: USD, revenue unit: Million). This scale and a projected ~10% CAGR mean that by 2026 leadership teams must pivot from small‑scale testing to investment planning for multi‑line integration and distributed processing footprints.
Strategic implications for 2026 planning
-
Reframe investment criteria from technology novelty to unit‑economics at scale. Capital planners should model full production lines (including upstream packaging and downstream cold‑chain) rather than isolated equipment purchases.
-
Prioritize regulatory and market access mapping early. Where export routes or premium channels are material to your plan, compliance roadmaps (including country‑specific validations) need to be in place prior to commissioning.
-
Introduce modular deployment pilots that preserve optionality. Pilot cells that can be redeployed between SKUs and sites reduce execution risk as demand patterns shift.
-
Embed ingredient and yield sensitivity in business cases. Technologies that reduce spoilage or increase extractable yield change the unit economics materially — these must be stress‑tested under volatile raw‑material scenarios.
-
Align commercial launches with supply‑chain capability. Marketing timelines and retailer listing agreements should be conditioned on validated throughput and packaging compatibility to avoid launch delays.
Competitive landscape — who matters and why
The non‑thermal equipment and systems market is concentrated, with a clear set of global leaders and a cluster of specialized innovators. Our competitive concentration metrics indicate a market that has meaningful incumbency advantage at the top, while room remains for niche challengers focused on product‑specific value propositions.
-
Hiperbaric (Burgos, Spain) — A global leader in HPP equipment. Hiperbaric’s product pipeline and recent launches emphasize yield optimization and throughput improvements tailored to juice and protein segments. Their engineering cadence and installed base create a high‑barrier to entry for commoditized HPP units.
-
JBT FoodTech (Chaska, Minnesota, USA) — Broad systems integrator offering industrial HPP systems and end‑to‑end non‑thermal lines. JBT’s strategy emphasizes scale and geographic footprint, evidenced by recent manufacturing expansions aimed at reducing lead times in high‑growth regions.
-
Multivac Group (Wolfertschwenden, Germany) — Provides integrated HPP with packaging systems, positioning itself where equipment and primary packaging converge. This integrated play appeals to processors seeking single‑vendor SLAs for sterilization and primary‑pack integrity.
-
Elea Technology GmbH (Quakenbrück, Germany) — A specialist in PEF systems for cell‑disruption applications. Elea’s demonstrations at major trade shows underscore the modality’s commercial traction in starch‑ and vegetable‑processing workflows.
-
Pulsemaster (Ochten, Netherlands) — Focused on PEF solutions that enhance extraction and shelf stability, often partnering with ingredient processors and co‑packers to validate incremental yield gains.
-
Steriflow (Thyssenkrupp) (Quimper, France) — Offers both autoclave and HPP systems, representing a bridge between established thermal processes and non‑thermal adoption for food manufacturers seeking dual‑mode capabilities.
Recent vendor activities in the last 24 months — product launches, trade‑show demonstrations and strategic manufacturing expansions — indicate a race to capture installed‑base growth rather than to redefine the technology roadmap. Market entrants should therefore evaluate acquisition and partnership pathways as a faster route to scale than organic equipment development.
Regulation, input risk and cross‑border trade — the non‑technical constraints
Regulatory clarity is a tailwind: authorities in several major markets now treat certain non‑thermal interventions as compliant with pasteurization and pathogen reduction standards, which reduces market entry friction for exporters. However, regulatory equivalence does not remove the need for documented validation and country‑specific declarations — exporters must maintain a compliance playbook for each target market.
Supply‑side risks remain material. Ingredient price volatility and labor cost dynamics change the optimal technology choice for processors: a modality that preserves yield or reduces manual handling can deliver outsized returns in high‑cost labor markets, whereas in other contexts the decision will be driven by throughput and CapEx intensity. Trade frictions and novel‑food rules in some jurisdictions introduce additional time‑to‑market considerations that must be modeled into any 2026 rollout plan.
What PW Consulting’s report delivers — practical, not academic
This study is designed to be operationally usable at the board and plant level. Deliverables include:
-
Executive decision matrices that map technology choice to ROI under multiple demand and input‑cost scenarios, with ready‑to‑use sensitivity tables for CFOs.
-
Integration blueprints for moving from pilot lines to full cellular manufacturing, including recommended CapEx staging, bottleneck analysis and typical commissioning timelines.
-
Vendor scorecards and supplier negotiation playbooks that translate technical claims into commercial warrantied outcomes, helping procurement teams reduce acquisition and lifecycle risk.
-
Regulatory pathways and documentation checklists per major trade corridor to shorten market‑access timelines and avoid costly rework.
-
Operational KPIs and control charts for plant managers to monitor product integrity, yield and energy intensity of non‑thermal lines.
-
Case studies and investment teasers that illustrate three archetypal 2026 investment plays — retrofit, brownfield expansion and greenfield hub — with annotated P&L impacts and payback ranges.
How to use this preview to act in 2026
-
Use the headline market trajectory and concentration indicators to benchmark your competitive positioning: leaders are scaling capacity while challengers are carving niches around SKU‑level economics and service models.
-
Prioritize cross‑functional trials (operations, quality, procurement and commercial) that close the gap between laboratory claims and full‑line economics. Insist on trials that emulate commercial cycle times and packaging formats.
-
Lock regulatory and export questions early. If export premium channels form part of the strategy, build the compliance timeline into launch gating criteria.
-
Design procurement RFIs to capture total cost of ownership — include spare parts, service SLAs, training and decommissioning costs to avoid downstream surprises.
Final perspective
The non‑thermal processing market is entering a new phase where technology choice is inseparable from supply‑chain reality, regulatory positioning and commercial go‑to‑market design. Our analysis confirms that the winners in 2026 will be those who move beyond equipment selection to integrate legal, operational and commercial strategies into a single roadmap — and who can execute modular scale‑ups that preserve strategic optionality.
For procurement teams, operational leaders and investors preparing budgets and roadmaps for 2026, PW Consulting’s full report provides the granular models, vendor benchmarks and scenario P&L tools required to make defensible commitments. This preview outlines the strategic stakes; the complete study contains the underlying segment tables, vendor rankings and financial models necessary to finalize capital allocations and implementation timelines.
Next steps
Contact PW Consulting or visit our report page to access the full Worldwide Non‑Thermal Food Processing Market study, which includes the comprehensive appendices, data tables and executable templates referenced in this release. The detailed subsegment matrices and vendor financial models are available exclusively in the full report and are intended to support binding 2026 investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Non-Thermal Food Processing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com