

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide 5G‑Advanced Chip Market Set to Surge from USD 3,850 Million in 2025 to USD 41,506.3 Million by 2032 at a 40.45% CAGR
By pmarketresearch, 2026-07-15
Worldwide 5G-Advanced Chip Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s newest market study, Worldwide 5G-Advanced Chip Market (base year 2025; forecast 2026–2032), frames a defining moment for semiconductor strategy and telco ecosystem planning. With the market accelerating from early commercialization to a broad-scale deployment phase, our analysis equips executives to translate technical standards, supplier moves, and manufacturing capacity into defensible commercial choices for 2026 and beyond.
Worldwide 5G-Advanced Chip Market
Executive summary — why this matters now
5G-Advanced is shifting from standards and demonstrations to revenue-generating architectures. Our market model shows the total 5G‑Advanced chip market jumping materially by 2026 and compounding at a very high rate across the forecast window (CAGR ~40.45% for 2026–2032). This creates a finite strategic window in 2026 when choices about vendor partnerships, node investments, and product roadmaps will determine market share and margin trajectories through 2030 and into the era that bridges toward 6G.
Worldwide 5G-Advanced Chip Market
For leaders in device OEMs, infrastructure suppliers, auto telematics, industrial automation, and chipset IP licensing, the immediate questions are operational: which silicon partners to prioritize for sampling and qualification; where to allocate R&D and packaging budgets; how to reconfigure manufacturing and procurement to capture the early-adopter premium while avoiding overcommitment to single-node dependencies. Our report does not merely map opportunity — it prescribes decision paths aligned to business models and time horizons.
Worldwide 5G-Advanced Chip Market
Market trajectory: the macro picture
After a rapid commercialization ramp in 2023–2025, the total market value that underpins 5G‑Advanced chipsets shows a pronounced expansion in 2026 as Release 18 implementations broaden. The model projects a dramatic expansion across the forecast period, underscoring both scale potential and the imperative for timely execution. Equally important, industry concentration is pronounced: the top three suppliers account for a dominant share of the market (CR3 ~72.4%), and the top five approach near-total dominance (CR5 ~88.2%).
These structural facts — high growth and high concentration — create a bifurcated strategic environment: suppliers who secure early design wins and preferred foundry/packaging arrangements can capture outsized margins; late entrants face either niche specialization or acquisition as the primary route to scale.
Dynamics shaping 2026 decisions
- Standards and device readiness: 3GPP Release 18 crystallizes the technical baseline for 5G‑Advanced, introducing advanced MIMO, energy-efficient network constructs, evolved duplexing, and expanded positioning capabilities. Device and infrastructure timelines are now tightly coupled to Release 18 maturations.
- Manufacturing and packaging: Advanced node and advanced packaging capacity (including investments enabled by national semiconductor initiatives) are central to delivering power‑efficient, high‑performance modems and RF front-ends at scale. Decisions about node roadmaps and packaging partnerships will determine tactical time-to-market.
- RF and material shifts: Wide adoption of GaN in RF subsystems for mmWave amplification is remapping supply chains — from material sourcing through thermal/packaging engineering — and creating new supplier gating functions for systems integrators.
- Device ecosystems and platform plays: Platforms that combine modem, RF, AI acceleration, and power management are emerging as differentiators. The interplay between platform breadth and ecosystem support (software, modem stacks, and certification) will be a make-or-break factor in 2026 procurements.
Competitive landscape — who to watch
Our competitive review synthesizes supplier positioning, recent product milestones, and strategic signals that matter to procurement and product teams in 2026.
- Qualcomm Technologies, Inc. — Continues to lead on integrated modem‑RF platforms and early Release 18/19 readiness. Recent launches and sampling programs indicate Qualcomm’s strategy of marrying feature parity with OEM scale, making it a default partner for many smartphone and FWA players.
- MediaTek Inc. — Aggressively pursuing a platform and CPE-focused strategy with variants optimized for FWA and telematics. MediaTek’s emphasis on multi‑antenna RF gains and embedded AI shows a clear play to capture non-smartphone segments where differentiation is rapidly valued.
- Samsung Electronics Co., Ltd. — Advances in process and packaging allow Samsung to play both as an internal integrator (for its mobile business) and as a competitive foundry/customer for external modem projects. Expect Samsung to leverage transistor and memory innovations to create performance/per-watt advantages.
- Broadcom Inc. — Focused on infrastructure-grade SoCs for massive MIMO and wideband radio systems, with strategic FPGA and interoperability collaborations to enable scalable beamforming and AI-assisted signal processing.
- GCT Semiconductor — An example of rapid commercialization from a fabless designer to commercial shipments, signaling that smaller suppliers can capture specific verticals (e.g., air-to-ground) through focused qualification pipelines.
- Sequans Communications — Targeting the IoT and RedCap evolution in 5G‑Advanced, with low-power connectivity platforms that appeal to industrial and metered applications where cost and energy efficiency dominate.
- Huawei Technologies Co., Ltd. — Continues to execute in infrastructure and vertical implementations (robotics, healthcare), leveraging systems integration to offset component-level competition.
- Intel Corporation — Emphasizing infrastructure and edge compute integrations where network processors and modem platforms intersect with edge workloads, offering differentiated value to cloud and carrier partners.
Recent vendor moves in early 2026 — commercial sampling of Release 19‑capable modems, first commercial shipments from niche fabless players, and cross-company interoperability tests — are the operational signals procurement teams must track. These events will shape qualification schedules and OEM design freezes through H2 2026.
Strategic implications by value chain node
- Chip design and IP: Prioritize modular designs and licenseable IP blocks to shorten pathway to revenue when standards evolve. Licensing strategies and patent exposure must be reconciled with partner roadmaps.
- Foundry and packaging: Secure multi-node options and advanced packaging slots early. Contingency planning across foundries — and alignment with national subsidy programs — will reduce supply risk and cost volatility.
- RF subsystem and materials: Integrate RF material strategies (e.g., GaN) into system roadmaps; thermal and power design trade-offs will drive differentiation in mmWave devices and infrastructure radios.
- Software and platform certification: Software stacks, modem validation, and certification timelines are equally critical; allocate resources to interoperability testing and operator acceptance early in 2026.
What the PW Consulting report delivers — practical content
Our report is designed for executives who need to act in 2026. It blends forecast modeling with operational playbooks and includes:
- Scenario-driven market models and sensitivity analysis to map risk/reward across different adoption timelines;
- Supplier benchmarking that evaluates technical readiness, commercial terms, ecosystem support, and integration risk;
- Manufacturing and packaging heat maps identifying critical node bottlenecks and strategic contract-placement recommendations;
- Go-to-market playbooks for OEMs, infrastructure vendors, Tier‑1 integrators, and component suppliers aligned to three time-horizon archetypes (fast-follow, platform leader, and niche specialist);
- Due‑diligence and M&A frameworks tailored to de‑risk acquisitions in a high‑concentration market;
- Operational checklists for cross-functional teams (product, procurement, legal, and regulatory) to accelerate qualification while preserving negotiating leverage.
Importantly, the report omits line‑by‑line segment share tables in this public preview — a deliberate choice to ensure readers and clients engage with the full dataset and supplier breakdowns in the paid report. Those granular insights are essential for procurement negotiations and are provided under our standard client licensing terms.
Actionable recommendations for 2026
- Immediately initiate multi-vendor qualification lanes: Run parallel qualification with at least two platform suppliers for high-volume products to preserve time-to-market and bargaining leverage.
- Lock strategic foundry/packaging options: Secure advanced packaging slots and node allocations conditional on fall-back clauses tied to qualification milestones.
- Reassess IP and licensing posture: Build cross-license contingency plans and incorporate IP warranty/indemnity terms early in supplier contracts.
- Prioritize interoperability testing: Begin operator and ecosystem interoperability tests before design freeze to avoid schedule slips driven by Release 18/19 nuances.
- Align product roadmaps with regulatory and material shifts: Factor GaN adoption and national semiconductor initiatives into procurement and supplier development plans.
How PW Consulting’s analysis supports board-level decisions
Boards and C-suites need concise scenarios that translate technical standards and supplier events into balance-sheet and market-share outcomes. Our study provides translated impact metrics — revenue sensitivity, margin scenarios, and strategic option payoffs — that feed directly into capital allocation, M&A screening, and partnership commitments. The combination of a rigorous market model (showing the pronounced expansion beginning 2026 and a high multi-year CAGR) and supplier-level intelligence yields an execution roadmap you can act on this fiscal year.
Next steps — where to get the full intelligence
This public briefing highlights the strategic contours of the 5G‑Advanced chip market while preserving the full segmentation table and supplier-specific scorecards for our subscription clients and report purchasers. To access the detailed breakdowns, supplier scorecards, and the complete downloadable dataset that supports procurement and investment decisions, please visit the PW Consulting report page or contact our advisory team for a tailored briefing.
In an industry defined by both high growth and concentrated power, 2026 will be the year companies decide whether to lead, follow, or niche. PW Consulting’s Worldwide 5G‑Advanced Chip Market report is designed to make that choice a defensible, data‑driven decision.
For detailed analysis of this topic, please visit the official page: Worldwide 5G-Advanced Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Porcine Fibrin Sealant Market Poised to Grow at a 7.2% CAGR Through 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Porcine Fibrin Sealant (PFS) Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s latest market study on the Worldwide Porcine Fibrin Sealant (PFS) market delivers a forward-looking, actionable view tailored for senior executives, corporate development teams, and clinical-commercial leaders preparing strategic moves in 2026. This briefing highlights the report’s strategic value, synthesizes the high‑level market trajectory, and outlines the practical playbook elements that decision-makers will need — while preserving gated, granular segment-level data to incentivize access to the full deliverable.
Worldwide Porcine Fibrin Sealant (PFS) Market
High-level market trajectory: what every executive must internalize
- The PFS market has matured steadily through the early 2020s, expanding from roughly USD 220.2 Million in 2020 to about USD 310.5 Million in 2025 (base year), reflecting broadening clinical adoption and earlier regulatory approvals in key markets.
- Our forecast for the 2026–2032 period projects a continued compound annual growth rate (CAGR) of 7.2%, with global market value moving from an estimated USD 340.8 Million for 2026 toward approximately USD 505.2 Million by 2032 under the base-case scenario.
- Market concentration is meaningful: the top three players control a dominant share of the market (CR3 ≈ 68.5%), and the top five increase that concentration further (CR5 ≈ 84.2%). This structure creates both entry barriers and arbitrage opportunities for differentiated entrants or M&A players.
Why 2026 is a strategic inflection point
Several converging dynamics will make 2026 a pivotal year for firms active in, or entering, the PFS space:
Worldwide Porcine Fibrin Sealant (PFS) Market
- Market access and reimbursement levers are evolving. Regions that implement expedited cataloging or “green channel” mechanisms for novel medical devices materially shorten hospital adoption cycles; this changes the calculus for commercialization investment and partnership timing.
- Regulatory expectations are tightening around pathogen safety and validated virus‑inactivation of xenogeneic plasma‑derived products. Compliance investments and documented manufacturing controls are now preconditions for broader hospital procurement and cross-border distribution.
- Raw‑material and supply‑chain considerations favor players who can secure consistent, traceable porcine plasma sourcing and scale virus‑inactivation capacity. Cost and reliability advantages will drive price competition in established, cost‑sensitive markets while clinical differentiation will be more important in premium segments.
- Clinical evidence and indicated uses continue to diversify — from general hemostasis to high-value applications such as cardiovascular and neurosurgical adjuncts. The balance between broad off‑label adoption and targeted, label‑backed premium positioning will influence margin outcomes.
What the PW Consulting report delivers (practical, transaction‑grade content)
Our research is built to support executable decisions — not just to inform. Highlights of the deliverable include:
Worldwide Porcine Fibrin Sealant (PFS) Market
- Robust market sizing and validated forecasting models (2020–2032) with sensitivity analyses and three investment scenarios (base, accelerated uptake, downside shock).
- Regulatory and reimbursement playbooks for major markets, including step‑by‑step timelines, dossier checklists, and a matrix of common inspection findings related to virus‑inactivation processes.
- Clinical evidence matrix mapping the current level of evidence by surgical application and recommended trial designs to upgrade indication value (e.g., randomized controlled trials, registry endpoints, health‑economic outcomes).
- Commercial readiness assessments: go‑to‑market pathways for direct sales, distributor models, and hospital formulary inclusion; pricing and contracting templates aligned with national procurement strategies.
- Supply‑chain and manufacturing due diligence frameworks focused on plasma sourcing, virus‑inactivation capacity, cold chain logistics, and quality management systems required for scale.
- Competitive benchmarking and valuation ranges, including deal‑screen frameworks for bolt‑on acquisitions and cross‑border partnership scoring (technology fit, regulatory footprint, commercial traction).
- Risk heat maps (regulatory, clinical, reputational, raw material) and mitigation plans prioritized by expected impact on 24–36 month value delivery.
Competitive landscape: from incumbents to regional challengers
The competitive picture in porcine fibrin sealants combines established manufacturers, recent M&A activity, and fast-moving regional challengers. Key themes:
- Local champions with product approvals and hospital‑level inclusion programs have shown they can accelerate adoption rapidly where market‑access opportunities exist. Early catalog inclusion and public hospital access channels materially shorten time‑to‑revenue for these players.
- International strategic acquirers are active in the segment, reflecting its strategic fit with broader hemostasis and surgical portfolio plays. Such transactions facilitate technology transfer, standardization of manufacturing controls, and expanded distribution.
- Smaller manufacturers continue to focus on clinical niches (e.g., intestinal anastomosis sealing, single‑port laparoscopy hemostasis), and some are leveraging combination‑therapy positioning (sealant + adjunct device) to escape commodity dynamics.
Representative profiles (select examples):
- Manufacturers that launched porcine fibrin sealant products recently have combined regulatory wins and targeted hospital catalog inclusion to secure early adoption in local networks; these commercial wins validate the “fast lane” access strategy for novel devices.
- Acquisition by a global surgical/medical devices conglomerate has occurred in the space, signaling strategic intent to integrate PFS solutions within broader hemostasis and surgical platforms — expect increased benchmarking on quality systems and evidence requirements from such players.
- Other regional firms remain active across general surgery and specialty niches, reinforcing a dual‑track competitive structure: large consolidated players competing on scale and breadth, and smaller specialists competing on cost, agility, and tight clinical workflows.
Strategic implications and recommended actions for 2026
For executives evaluating investments, partnerships, or product launches in PFS, we recommend a prioritized set of actions for 2026:
- Accelerate market‑access initiatives in target regions that offer expedited cataloging or hospital‑tier prioritization. Align regulatory filings and health‑economic dossiers to local payer expectations before launch.
- Invest early in validated virus‑inactivation and QA capabilities. These are now table stakes for cross‑market commercialization and materially reduce transaction risk for potential acquirers or partners.
- Design clinical programs that move beyond simple hemostasis endpoints to demonstrate patient‑level outcomes and cost offsets in high‑value surgical specialties. This enables premium pricing and stronger reimbursement negotiations.
- Secure diversified raw‑material channels and scalable manufacturing to avoid single‑source vulnerabilities; consider contract‑manufacturing partnerships with validated suppliers as a near‑term scalability strategy.
- Explore targeted M&A or licensing to fill gaps quickly — particularly for companies seeking rapid scale in distribution or to obtain complementary clinical evidence packages.
Regulatory & safety FAQ — quick reference
- Are porcine fibrin sealants regulated differently than human‑plasma products? Yes — porcine plasma‑derived products are subject to pathogen safety requirements and typically require validated virus‑inactivation steps as part of regulatory submissions in major markets.
- Do expedited hospital access pathways exist? Yes — some jurisdictions maintain cataloging mechanisms or “new quality device” lists that create a green channel to public hospitals and facilitate earlier payer engagement. Securing placement on these lists is a high‑leverage commercial objective.
How PW Consulting can accelerate your 2026 outcomes
Our advisory services are structured to move clients from strategy to execution within 6–12 months. Core offerings include:
- Commercial due diligence and full financial model stress‑testing for targets or new product launches.
- Regulatory pathway mapping and dossier preparation support focused on virus‑inactivation evidence and manufacturing validation.
- Clinical evidence strategy: protocol design, endpoint selection, and payer‑facing value dossiers.
- Market access playbook execution: hospital catalog engagement, procurement tender support, and reimbursement negotiation templates.
- M&A advisory: target screening, valuation ranges, and integration planning for manufacturing and quality systems.
Closing: an executive call-to-action
Porcine fibrin sealants present a compelling growth opportunity — predictable, clinically meaningful, and structurally shaped by regulatory and market‑access interventions. The market’s disciplined CAGR and observed concentration dynamics favor players who can pair regulatory rigor with rapid hospital access and differentiated clinical evidence.
PW Consulting’s full Worldwide Porcine Fibrin Sealant (PFS) Market report contains the underlying segment tables, detailed regional and application breakouts, company financials, and the transaction-model toolkit needed to convert insight into action. For teams preparing strategic moves in 2026, the report functions as both a market map and an operational playbook — contact PW Consulting to obtain the full report and unlock the gated models that underpin these recommendations.
For detailed analysis of this topic, please visit the official page: Worldwide Porcine Fibrin Sealant (PFS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Battery Manufacturing Software Market to Rise from USD 1,127.29 Million in 2025 to USD 3,642.24 Million by 2032 at 18.24% CAGR; EV Batteries (USD 710.19 Million) and Asia‑Pacific (USD 538.91 Million) Drive Growth
By pmarketresearch, 2026-07-15
Worldwide Battery Manufacturing Software Market — Strategic Preview for 2026 Decision Makers
PW Consulting today releases the executive trailer for our forthcoming market study, "Worldwide Battery Manufacturing Software Market." This briefing summarizes the report’s strategic value for corporate leadership and investors preparing decisions in 2026. It highlights why the battery-software layer has become a board-level issue, how the market is evolving at scale, and what practical guidance our full report delivers — while intentionally reserving granular segment-level tables and forecasts for subscribers.
Worldwide Battery Manufacturing Software Market
Why battery-manufacturing software will shape 2026
Battery manufacturing is no longer a pure electrochemical or automation play; it is an information and software challenge. Our analysis shows the addressable market for software that orchestrates, monitors, and optimizes battery cell and pack production has expanded rapidly over the past five years and is poised for sustained double‑digit growth. On a compound basis, the market is projected to grow at a CAGR of 18.24% over the forecast horizon beginning from the 2026 baseline. Historical traction (2020–2025) and near-term forecasts (2026–2032) demonstrate both the replacement and greenfield demand dynamics — from gigafactory digitalization to traceability, analytics, and integrated MES/MOM deployments.
Worldwide Battery Manufacturing Software Market
Key takeaways for executive teams: software is now a primary lever for yield improvement, compliance readiness (traceability, passporting), and capital-efficiency in factory ramp-ups. The speed and scale of software adoption — not only the choice of platform — will determine which manufacturers realize projected margin expansion and faster time-to-market in 2026.
Worldwide Battery Manufacturing Software Market
Macro trajectory at a glance
-
Historical growth (2020–2025) shows consistent year-over-year expansion as manufacturers moved from pilots to production-scale deployments.
-
The market base year for our analysis is 2025. From that base, our forecast period extends from 2026 through 2032 and includes scenario modelling for conservative, base, and accelerated demand pathways.
-
By modeling technology adoption curves, regulatory drivers, and factory ramp cycles, PW Consulting estimates the market will continue to expand meaningfully through 2032 under the base scenario (CAGR 18.24%).
-
Market concentration is moderate: the top three vendors account for roughly a third of market revenues (CR3 ≈ 34.2%), while the top five approach half of the market (CR5 ≈ 48.15%). This mix indicates room for both established industrial software providers and focused analytics specialists to capture opportunity through differentiation and partnerships.
What the research contains — practical, transaction-ready deliverables
Our full report is designed as an operational playbook for procurement committees, digital transformation leads, and corporate strategy teams evaluating investments in 2026. Highlights include:
-
Market size model and revenue waterfall: an auditable time series across the historical window and multi-year forecast, with clear assumptions and sensitivity endpoints.
-
Vendor landscaping and capability matrices: comparative scorecards on MES/MOM, quality management, simulation & design, asset performance, and data/AI platforms — emphasizing integration risk and scalability for gigafactories.
-
Use‑case ROI templates: pre-configured calculators for yield improvement, energy optimization, labor reduction, and ramp time compression — enabling CFOs to quantify payback over 12–36 months.
-
Implementation playbooks: staged roadmaps for pilots → scale, including data architecture patterns, cybersecurity controls, change management milestones, and vendor selection checklists.
-
Regulatory and compliance annexes: requirements mapping (including battery passport readiness), traceability architectures, and recommended audit controls for 2026 compliance schedules.
-
Scenario stress tests: impact analyses of policy interventions, energy cost shocks, and differing rate-of-ramp assumptions on software demand and vendor revenue streams.
Competitive landscape — winners, challengers, and partners
The vendor universe spans global industrial-software incumbents, automation leaders, and niche analytics specialists. In the report we profile strategic and execution differences among them and identify where partnerships and M&A will be decisive for scale.
-
Industrial incumbents with broad digital-thread portfolios — companies such as GE Vernova, Siemens, Rockwell Automation, ABB — bring deep MES/MOM expertise and plant-level automation integration. Their strategic advantage lies in end-to-end operational continuity, field-proven scalability, and existing relationships with OEMs and gigafactories.
-
Automation and software convergence plays — exemplified by Panasonic Connect’s recent launch of an end-to-end MES designed for EV battery lines — show how traditional manufacturers are building platform offerings to accelerate customer digital transformation and onshore capacity expansions.
-
Emerging analytics specialists — companies such as Voltaiq, Energsoft, and PDF Solutions — compete on depth of battery-domain analytics, flexible deployment models, and R&D-to-production data continuity. These firms often command premium valuations when they prove the ability to shift insights into measurable yield and quality outcomes.
-
New product introductions (e.g., Honeywell’s Battery MXP in mid-2024) underline a shift: vendors emphasize AI-enabled operations that claim significant reductions in startup scrap and ramp time compression, positioning software as a critical source of competitive differentiation for factory operators.
Regulatory, operational, and cost drivers — what accelerates adoption in 2026
-
Regulatory pressure: Mandatory requirements around traceability and carbon-footprint declarations (e.g., upcoming battery passport regimes) are forcing manufacturers to deploy software that guarantees provenance and auditable lifecycle data.
-
Onshoring and policy stimulus: Recent policy incentives have driven dramatic capacity growth in some industries; software integration and cross-border data sovereignty considerations are material procurement factors.
-
Labor and energy economics: In a baseline 40 GWh/a lithium-ion facility, labor represents a measurable share of operating cost — and digitalization can deliver incremental staff reductions and process automation. Separately, energy‑tracking and optimization use cases have potential for nearly double‑digit reductions in energy consumption for high-intensity stages of production. The combined effect materially improves per‑kWh cost curves and shortens payback windows for software investments.
-
Cybersecurity and standards: Compliance with standards such as ISO 21434 and IEC 62443, and implementation of end-to-end encryption (e.g., AES‑256, TLS 1.3) are no longer optional for connected manufacturing environments; they are procurement gatekeepers for enterprise buyers.
Strategic recommendations for 2026 planning
-
For battery manufacturers: Treat software procurement as capital investment. Use PW Consulting’s ROI templates to benchmark vendor claims, prioritizing projects that improve yield, reduce scrap, and compress ramp time. Reserve 20–30% of digital transformation budgets for data‑ops and cybersecurity hardening.
-
For software vendors: Differentiate on outcome-focused integrations — demonstrate validated yield improvements and clear compliance mappings. Consider flexible commercial models (subscription + performance‑share) to lower adoption barriers at scale.
-
For systems integrators and consultants: Build industry-specific accelerators (pre-built data models, traceability modules, cybersecurity baselines) to shorten time-to-value for customers and capture upstream advisory margins tied to plant commissioning.
-
For investors and M&A teams: Target assets that combine domain analytics with validated production deployments. Our market concentration analysis suggests consolidation potential where vertical integration of MES and analytics creates defensible bundles.
-
For policymakers and regulators: Collaborate with industry to design data‑sharing architectures that meet traceability goals without creating export‑blocking data‑sovereignty constraints; adopt phased compliance thresholds to avoid creating retrofit liabilities for nascent factories.
How PW Consulting’s report helps you act in 2026
If your roadmap for 2026 includes factory expansions, vendor selection, or investment allocation in battery manufacturing software, this report turns market rhetoric into actionable decisions. It combines a transparent financial model, vendor scorecards, implementation playbooks, and scenario analyses that allow procurement committees and executive teams to stress-test choices under specific ramp and regulatory timelines. Importantly, the full report contains the granular segmentation tables, regional and end‑use splits, and vendor revenue estimates — information that is intentionally embargoed here to preserve independent subscriber value.
Next steps and how to access the full analysis
PW Consulting’s full "Worldwide Battery Manufacturing Software Market" report is structured to be adoption-ready: it includes executable checklists, contract negotiation playbooks, and CFO‑grade ROI memos tailored to 2026 budgeting cycles. For teams preparing capital approvals or negotiating vendor pilots this year, the report provides the evidence base to move from pilots to plant-scale deployments with confidence.
To obtain the complete dataset, vendor profiles, and the segmented forecast tables that support scenario modelling, please visit our report subscription page or contact PW Consulting’s industry research desk. Our advisory team is available to run bespoke workshops that apply the report’s models to your specific production and regulatory context.
PW Consulting — providing the strategic intelligence that lets leaders turn software investment into factory advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Battery Manufacturing Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Email Address Verification Service Market to Reach USD 4,305.78 Million by 2032, Expanding at a 13.45% CAGR
By pmarketresearch, 2026-07-15
Worldwide Email Address Verification Service Market — Strategic Outlook for 2026
PW Consulting's latest market study, "Worldwide Email Address Verification Service Market," delivers a decision-grade briefing for executives planning growth, procurement, and risk management initiatives in 2026. Grounded in a comprehensive historical review (2020–2025) and a forward-looking forecast (2026–2032), the report synthesizes macro trajectories, competitive positioning, regulatory pressure points, and executable playbooks that senior leaders can act on immediately. Below we summarize the report's strategic value while intentionally withholding core segmentation figures — a deliberate "trailer" to demonstrate our depth while directing readers to the full report for the detailed intelligence they need to execute.
Worldwide Email Address Verification Service Market
Market scale and trajectory — what the topline means for enterprise strategies
The market for email address verification services has transitioned from a niche hygiene function into a strategic infrastructure component for digital customer engagement and risk management. On a topline basis, PW Consulting measures the global market at USD Million scale, with recent base-year comparatives and a robust growth outlook through our forecast period. From 2023 to the base year (2025) the market expanded materially, and our 2026–2032 forecast models a compounded annual growth rate (CAGR) of 13.45%. Under this trajectory, the market more than doubles in the forecast window, signaling continued demand from marketing, fraud prevention, identity verification, and data quality programs.
Worldwide Email Address Verification Service Market
For decision-makers, the implication is clear: email verification is no longer a low-cost add-on; it is a scalable service class that materially affects lifetime value, deliverability, and regulatory risk. Companies that delay investing in verification capabilities risk higher operational costs from deliverability failures, inflated campaign spend, and potential compliance exposure as privacy regimes tighten.
Worldwide Email Address Verification Service Market
Dynamics shaping vendor selection in 2026
-
Regulatory tightening and compliance as a procurement filter. Heightened enforcement under GDPR and enhanced CCPA/CPPA regimes means verification providers must prove lawful processing, robust security controls, and transparent data handling. The report documents how recent regulatory shifts — including increased monetary penalties and expanded cybersecurity audit requirements — raise the bar for vendor due diligence and contract terms.
-
Accuracy vs. latency trade-offs. Real-time API verification and bulk verification continue to coexist, but buyer requirements increasingly demand hybrid capabilities: millisecond-level checks for sign-up flows, combined with deep bulk hygiene for retention and segmentation. Our benchmarking approach evaluates providers not only on accuracy but on latency, throughput, and failure-mode behavior under real-world workloads.
-
AI and predictive deliverability scoring. Advanced providers are embedding machine learning to infer deliverability risk and forecast bounce propensity — a development that shifts the value proposition from raw list cleaning to predictive inbox placement. Our fieldwork assesses how recent AI feature releases change expected ROI for enterprise buyers.
-
Concentration and market structure. The market shows a moderate level of concentration; the top providers account for a meaningful share of revenue, but there remains a long tail of specialized and regional players. This structure creates opportunities for strategic partnerships and for incumbents to differentiate on compliance, vertical specialization, or platform integration.
Competitive landscape — profiles and positioning
Our competitive review evaluates vendors across technical performance, integration maturity, compliance posture, pricing transparency, and go-to-market fit for enterprise vs. SMB buyers. Notable providers include:
-
ZeroBounce — strong in real-time validation APIs and deliverability analytics tailored to marketing and sales teams; valuable for organizations prioritizing inbox placement insights.
-
Bouncer — EU-based operator with a compliance-forward narrative, emphasizing ISO 27001 and catch-all detection; a sensible choice for privacy-conscious buyers operating under GDPR.
-
Hunter.io — combines email discovery with verification, positioning itself for B2B lead generation workflows where enrichment and verification are bundled.
-
NeverBounce (by ZoomInfo) — integrated data-hygiene and CRM connectivity that appeals to agencies and enterprises running large-scale campaigns through established martech stacks.
-
Kickbox — known for ESP integrations and pay-as-you-go pricing, strong where operational flexibility and ESP alignment matter.
-
Clearout — aggressive AI capability expansion; recent machine-learning enhancements improve risk detection and predictive scoring, raising the bar for bulk verification accuracy.
-
Verifalia, MillionVerifier, Emailable, EmailListVerify — a set of providers that collectively address SDK support, high-volume economics, spreadsheet-friendly workflows, and cost-sensitive bulk cleaning needs.
Recent competitive moves — including AI feature rollouts, independent benchmark publications, and renewed emphasis on certifications — underscore a market where feature velocity and trust credentials increasingly determine buyer choice. PW Consulting’s vendor matrix in the full report provides a granular view across more than a dozen performance and governance criteria to support RFP short-listing.
What the PW Consulting report delivers — practical, action-ready assets
-
Tactical procurement tools: scoring templates and an RFP checklist calibrated to accuracy, latency, integration effort, and compliance controls so procurement teams can isolate vendors that match enterprise risk appetites.
-
Implementation playbooks: step-by-step guidance for integrating verification into customer onboarding, CRM hygiene, and marketing automation flows — including rollback plans and parallel validation strategies to minimize disruption.
-
Financial models and ROI calculators: pre-built templates that capture key levers (deliverability lift, spam trap avoidance, funnel conversion improvements, and cost per validation) to produce a multi-year TCO and payback timeline.
-
Compliance and contractual templates: clauses for data processing addenda, security attestations, and audit rights that reflect evolving CCPA/GDPR requirements and the latest CPPA guidance on audits and automated decision-making.
-
Market maps and adoption scenarios: demand-side segmentation frameworks and three enterprise adoption archetypes (conservative, pragmatic, and aggressive) that help leaders choose timing and scope for pilots and rollouts.
Strategic implications for 2026 planning
-
Prioritize verification in digital transformation roadmaps. Verification is an enabling technology for customer identity quality, deliverability assurance, fraud reduction, and consent management. Treat it as infrastructure: align ownership with product and security, not just with marketing.
-
Shortlist vendors against compliance posture first. With heightened fines and expanded cybersecurity audit requirements, the initial screen must focus on lawful basis for processing, breach controls, and certifications — because technical performance cannot compensate for regulatory failures.
-
Design for hybrid deployment. Combine real-time API checks for onboarding with scheduled bulk hygiene and ML-based risk scoring to optimize cost and performance across the customer lifecycle.
-
Measure beyond bounces. Expand KPIs to include engagement lift, spam-folder avoidance, deliverability delta, and downstream CRM decay. Our ROI templates show how small percentage improvements compound into significant lifetime value gains.
-
Plan for vendor lock-in and exit costs. Ensure data portability, credits, and export pathways are contractually clear; the market's moderate concentration means switching costs can be material for enterprises that integrate verification deeply into upstream and downstream systems.
How to use this report in Q1–Q3 2026
For 2026 planning cycles, the report is best used in three ways: (1) accelerate procurement by using our RFP and scoring templates to reduce evaluation time and avoid costly blind spots; (2) align legal and security teams early using our compliance checklist to prevent last-minute procurement stalls; and (3) run an eight-week pilot with KPI triggers defined by our ROI model to validate vendor claims in your environment before committing to enterprise contracts.
Why the full intelligence matters
PW Consulting’s public summary demonstrates the directional forces and recommended actions executive teams should consider in 2026. However, operational success depends on the granular details — supplier-level accuracy matrices, latency distributions under peak loads, region-specific compliance mappings, and exact market-split analytics — all of which are intentionally held in the full report to preserve client value and enable tailored guidance. We designed the report to be directly operational: buyers can extract vendor shortlists, legal attachments, and pilot templates without further consultancy, while strategic teams can use our forecasts to model multi-year budgets and M&A scenarios.
To obtain the complete dataset, vendor scorecards, and the downloadable implementation assets referenced above, consult the PW Consulting report landing page. The full deliverable provides the actionable detail procurement, security, and marketing leaders need to convert the market’s growth into measurable business outcomes in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Email Address Verification Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Areca Nut Market Hits USD 1,008.0 Million in 2025 — Growth Momentum Ahead
By pmarketresearch, 2026-07-15
Worldwide Areca Nut Market — Strategic Outlook for 2026 Decision‑Makers
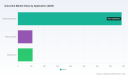
PW Consulting today releases its authoritative market brief — Worldwide Areca Nut Market — built to translate a complex mix of trade policy shifts, supply‑side pressures, and regulatory headwinds into operationally actionable intelligence for executives planning through 2026 and beyond. Anchored on a 2025 base year and a detailed forecast covering 2026–2032, our analysis shows the global areca nut market at USD 1,008.0 Million in 2025, growing at a compound annual growth rate (CAGR) of 3.88% across the forecast window. This release is a strategic “trailer”: it demonstrates the depth of our analytics and practical frameworks while guiding readers to the full report and datasets for transaction‑grade decision support.
Worldwide Areca Nut Market
Why this report matters for 2026 strategy
-
Trade and regulatory regimes are in flux. Exporters and buyers face evolving compliance demands (including heightened scrutiny from major food safety regulators) that directly affect market access and distribution economics.
Worldwide Areca Nut Market -
Supply fundamentals are changing. Input inflation, localized mechanization programs and new processing capacity are altering cost curves and the structure of competitiveness at farm and processor levels.
Worldwide Areca Nut Market -
Market concentration and vertical strategies are reshaping value capture. A modestly concentrated producer/processor pool creates both opportunities for scale plays and niches for premium positioning.
What’s inside the PW Consulting report (operational content highlights)
-
Transparent market sizing and demand scenarios — baseline, downside (regulatory shock), and upside (value‑added adoption) — with an integrated financial model for commercial diligence.
-
Supply chain mapping down to farmgate economics, post‑harvest loss vectors, and processing cost drivers so procurement managers can quantify sourcing risk and redesign supplier agreements.
-
Regulatory risk matrix and mitigation playbook covering export compliance, labeling and ingredient restrictions, and jurisdictional bans, including trigger points for immediate supply diversification.
-
Competitive landscaping and company dossiers — proprietary profiles and capability matrices for the leading cooperatives, processors, traders and exporters in key origin countries.
-
Operational toolkits: margin ladders, capex sizing templates for processing upgrades, mechanization adoption calculators, and RFP checklists for sorting/packaging lines and traceability systems.
-
Scenario‑based M&A playbooks, including target archetypes, valuation sensitives and integration checklists tailored to strategic buyers and financial sponsors.
Macro takeaways you can act on now
-
Measured growth with pockets of disruption. The 3.88% CAGR embedded in our forecast reflects steady global demand tempered by regulatory pressures and trade volatility. Executives should expect portfolio‑level growth rather than uniform expansion across channels.
-
Geography still matters. Market volume and processing capacity are concentrated in a handful of origin regions, with newer clusters emerging due to targeted public investment and private plant commissioning. This creates asymmetric risk — and asymmetric opportunities — for agile players.
-
Scale versus specialization trade‑offs. The market’s concentration metrics (CR3: 42.3%; CR5: 58.15%) point to a competitive landscape where scale buys reach and bargaining power, while specialized processors can win premium margins via quality control, certification and downstream integration.
Competitive landscape: who is shaping the market
The sector is populated by a mix of farmer cooperatives, regional processors, export houses and trader‑specialists. Cooperative aggregators focused on membership procurement and value addition are consolidating buying power and improving traceability, while private processors and exporters continuously upgrade sorting, hygienic handling and packaging to meet stricter buyer specifications. Notable operational movements in early 2026 illustrate these dynamics: a large cooperative broke ground on an expanded warehousing and procurement hub to strengthen farmer linkages; a state government rolled out subsidized processing cluster initiatives to reduce post‑harvest loss; exporters commissioned optical sorting and hygienic packaging lines to satisfy international buyers; and new high‑capacity processing plants were inaugurated in under‑served production belts to support regional cultivation expansion.
These developments underscore two strategic threads: (1) incumbents are investing to defend export channels and quality premiums; (2) local public investment is accelerating capital intensity at origin, changing the basis of competition from raw supply to processed, compliant throughput.
Regulatory and trade dynamics that will shape 2026 outcomes
-
Heightened import scrutiny in principal markets requires exporters to invest in documented quality systems. Ongoing import alerts and detention protocols maintained by major food safety authorities mean that non‑compliant shipments face material time‑to‑market and cost penalties.
-
Protectionist trade instruments in origin markets — including recent minimum import pricing and tariff adjustments — are influencing trade flows and filter directly into sourcing and pricing strategies for downstream buyers.
-
Persisting public health classifications have led to municipal restrictions, mandatory warnings and, in some instances, product bans. Companies must run jurisdictional regulatory heat maps and include litigation/regulatory risk premiums in long‑term planning.
Operational and raw‑material pressures
Farmers and processors are contending with rising agricultural input costs and localized labor constraints. Input inflation — in part driven by global fertilizer and agrochemical price moves — is increasing smallholder production costs by approximately one digit percentage in affected origins. That trend amplifies the value of aggregation, input financing solutions and productivity‑enhancing investments (e.g., mechanized harvest support and improved post‑harvest handling) to compress total landed cost.
Strategic playbook for 2026 decision‑makers
-
De‑risk export exposure: implement a compliance assurance program (certifications, pre‑shipment testing, documented chain of custody) and diversify market channels to reduce single‑market dependency.
-
Upgrade processing to capture premium margins: prioritize investments in optical sorting, hygienic packaging and traceable supply chains where modelled payback is within three–five years under our baseline case.
-
Partner with cooperatives and cluster programs: structured off‑take and input support contracts reduce procurement volatility and create scalable raw material pipelines.
-
Adopt scenario planning as governance routine: board‑level stress tests should include acute regulatory shock and sustained demand contraction scenarios; set contingent KPIs and liquidity buffers accordingly.
-
Reconfigure sourcing agreements: move from spot buying to hybrid contracts (indexed base price + quality premium) tied to recognized quality metrics and compliance milestones.
M&A and partnership implications
Given the sector’s middling concentration, there is strategic logic for both horizontal consolidation and bolt‑on deals that expand processing capacity or buyer access. Buyers should prioritize targets that (a) demonstrate documented quality controls and export compliance, (b) have access to farmer networks or cooperative relationships, and (c) possess processing upgrades that materially improve yield and reduce rejection rates. Our acquisition assessment matrix in the full report quantifies integration cost, expected margin uplift and time‑to‑value against regulatory and market risk scenarios.
How PW Consulting supports implementation
Our full engagement package includes granular market models, a live Excel toolkit for scenario and sensitivity analysis, on‑the‑ground supplier benchmarking templates, and downloadable due‑diligence checklists tailored for strategic and financial buyers. We also provide bespoke workshops to operationalize the report’s playbook — from capex prioritization for processing lines to drafting export compliance SOPs and supplier scorecards.
Final note — the trailer and next steps
This briefing highlights the high‑value insights contained in PW Consulting’s Worldwide Areca Nut Market study and explains why 2026 is a pivotal year for strategic repositioning. We intentionally present top‑level sizing and directional analytics here, while preserving the full modeling, sub‑segment outputs, and transaction‑grade datasets for the complete report. To obtain the full study, access the downloadable models, or commission an executive briefing tailored to your organization’s strategic questions, please visit our report page.
Leaders who act in 2026 with disciplined compliance programs, targeted processing investments, and pragmatic sourcing partnerships will convert a market characterized by steady growth and elevated risk into a durable source of competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Areca Nut Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 5.85% CAGR for Worldwide Non‑Filtering Cloth Vacuum Filters Market During 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Non-Filtering Cloth Vacuum Filters Market: Strategic Imperatives for 2026 Decision‑Makers
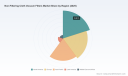
As industrial supply chains recalibrate and capital allocation priorities shift, executives and procurement leaders face a narrow window in 2026 to lock in durable competitive advantage in the non‑filtering cloth vacuum filters market. PW Consulting’s latest market study synthesizes seven years of historical trends and a detailed seven‑year forecast to translate industry noise into boardroom‑ready implications. The headline: the market has moved from a modest base in 2020 to a materially larger, more attractively growing sector by 2025, and our base‑case projection shows a compound annual growth rate (CAGR) of 5.85% across the 2026–2032 planning horizon. Corporates that adopt a targeted mix of product, procurement and service strategies in 2026 will capture disproportionate share of value as demand patterns and product complexity evolve.
Worldwide Non-Filtering Cloth Vacuum Filters Market
Market trajectory and what it means for corporate strategy
Our analysis demonstrates that the overall market has expanded steadily through 2020–2025 and that this positive momentum is expected to continue into the early 2030s. For strategy teams, the critical implications are threefold:
Worldwide Non-Filtering Cloth Vacuum Filters Market
- Predictability: The mid‑single‑digit CAGR provides a stable growth envelope suitable for multi‑year investments in manufacturing capacity, R&D and aftermarket service capabilities, without assuming hyper‑cyclical volatility.
- Differentiation Premiums: As upstream materials and downstream process requirements become more specialized, premium engineered cloths and bespoke belts command improving margins relative to commodity offerings—presenting opportunities for both incumbents and well‑capitalized challengers.
- Timing: Capital projects and supplier requalification cycles typically span 12–24 months. Decisions made in 2026 on supplier selection, materials strategy, and retrofit roadmaps will still be unfolding across the forecast window, making this year an inflection point for long‑term positioning.
Drivers reshaping demand
Three structural forces are driving the market’s growth and altering the competitive map:
Worldwide Non-Filtering Cloth Vacuum Filters Market
- Process intensification in heavy industries. Mining, mineral processing and wastewater treatment are investing to raise throughput and reduce water consumption; advanced vacuum cloths that improve cake dryness and uptime are direct beneficiaries.
- Materials and performance innovation. Polypropylene, polyester and other synthetic yarns remain the dominant feedstocks, but engineered monofilament and multifilament constructions are enabling wider, more stable belts and superior abrasive resistance—unlocking new applications and retrofit opportunities.
- Regulatory and hygiene requirements. Where food processing and high‑purity chemical streams are concerned, compliance with food‑grade certifications and hygiene standards (e.g., FDA and CE frameworks) is increasingly non‑negotiable, shifting supplier selection toward vendors with certified processes and traceable supply chains.
These drivers interact: process intensification raises the bar for materials, which in turn tightens regulatory scrutiny and increases the value of supplier capabilities beyond mere fabric supply.
Competitive structure and what concentration means for buyers
The market exhibits a concentrated core at the top and a fragmented long tail. Our concentration metrics indicate a market where the three largest firms hold a notable share of aggregate revenues and the top five firms control a majority slice of industry sales. That structure creates both strategic risk and opportunity:
- For buyers: concentration reduces the pool of suppliers able to deliver validated, scale solutions quickly, increasing the importance of robust supplier risk management, dual‑sourcing strategies and contractual service guarantees.
- For suppliers: scale provides bargaining power on raw materials and aftermarket service penetration, but differentiation—through material science, installation and lifecycle services—remains the primary route to margin expansion.
Competitive landscape: capabilities that matter in 2026
Our proprietary company assessments highlight several archetypes among market participants: custom engineered filtration groups, vertically integrated manufacturers, and specialized fabric innovators. Five firms exemplify the competitive vectors you should monitor closely:
- Micronics Engineered Filtration Group (part of Cleanova): A U.S.‑based specialist in custom‑engineered filter media and cloths for a wide range of vacuum filtration equipment. Their strength is deep application engineering for complex liquid‑solid separation tasks—an attractive partner for OEMs and end‑users facing unique process constraints.
- Bolian Filtration Solutions Co., Ltd. (Liaoning Bolian): A Chinese woven cloth manufacturer that has broadened its profile into emerging end markets such as battery manufacturing and desulfurization. Recent trade show activity and supplier awards reflect an export‑oriented growth strategy combined with active engagement in filtration industry exhibitions and customer recognition programs.
- GKD Group (GKD Gebr. Kufferath AG): A European supplier known for integrated vacuum belt systems and in‑house spare manufacturing, with engineered solutions that optimize wash‑water reuse and vacuum box design—positioning them where process optimization and total cost of ownership are prioritized.
- Testori S.p.A.: An Italian filtration media provider that emphasizes material variety and tailored cake‑discharge concepts, making them a go‑to for customers requiring polymer‑specific cloths and application‑matched designs.
- K2TEC: A French manufacturer focused on a wide material palette and mechanical innovations such as patented closures and edge reinforcements, targeting clients that demand dimensional stability and abrasion resistance across broad width belts.
Across these profiles, three capabilities consistently separate winners from laggards in 2026: application engineering, validated supply‑chain traceability, and lifecycle services (installation, testing, scheduled replacements, and digital condition monitoring).
What the PW Consulting report delivers to practitioners
Beyond headline market sizing and a modeled forecast, our report is structured to enable immediate, executable decisions by plant managers, procurement leads and corporate strategy teams. Key practical deliverables include:
- Decision playbooks for supplier selection and qualification, covering technical acceptance tests, site validation protocols and contractual service level constructs.
- Material selection matrices that map process conditions (abrasion, temperature, chemical exposure) to recommended cloth families and construction types.
- CapEx and retrofit scenario models that quantify payback timelines under conservative, base and accelerated adoption cases—enabling finance teams to stress‑test investment proposals.
- Supplier scorecards and market positioning maps that balance capability, capacity, geographic risk and compliance credentials.
- Operational readiness checklists and recommended KPIs for aftermarket programs, from cake dryness and wear rates to wash‑water recovery and downtime metrics.
Importantly, the full report embeds our proprietary datasets and scenario engines that translate macro projections into site‑level forecasts—information we deliberately preview here in qualitative form to protect the actionable granularity available only in the source report.
Tactical recommendations for 2026
Based on our integrated analysis, PW Consulting recommends that corporate teams prioritize the following actions within 2026 planning cycles:
- Lock in strategic supply agreements with clearly defined performance KPIs and escalation paths. Given the market’s concentration profile, securing prioritized access to premium materials and production slots reduces project execution risk.
- Pursue a two‑track product strategy: a baseline line‑item of proven, cost‑efficient cloths for routine applications, and a parallel investment stream in high‑performance or application‑specific cloths where differentiation and margin are higher.
- Invest in aftermarket and predictive maintenance capabilities. Condition monitoring and scheduled replacements materially reduce unplanned downtime and can be structured as subscription revenue for suppliers.
- Validate raw material strategies. Polypropylene and polyester remain central, but long‑lead items and quality variability suggest hedging across suppliers and, where feasible, establishing secured inventory or consignment models.
- Embed compliance and traceability into procurement requirements for regulated end markets. Certifications and documented process control are increasingly entry‑barriers to food and pharmaceutical applications.
Where to focus for differentiation
For suppliers, differentiation should center on three bets: process engineering tools that reduce total cost of ownership, demonstrable material science that improves service life, and packaged lifecycle services that convert single‑sale transactions into recurring revenue streams. For buyers, the leverage lies in integrating performance guarantees with payment terms tied to availability and process outcomes.
Conclusion and how to access the full intelligence
The non‑filtering cloth vacuum filters market is maturing into a segment where technical capability, supply‑chain resilience and service delivery will increasingly determine competitive outcomes. With a steady mid‑single‑digit growth trajectory and clear demand drivers across heavy industry and regulated applications, 2026 represents a strategic moment for operators to convert market momentum into durable advantage.
PW Consulting’s full Worldwide Non‑Filtering Cloth Vacuum Filters Market report contains the complete numerical breakdowns, regional and application segmentation, supplier benchmarking, and downloadable scenario models that underpin the recommendations summarized here. If your 2026 strategy depends on precise supplier scorecards, validated cost models, or site‑level adoption forecasts, the full report provides the rigor and actionable datasets required to move from planning to execution.
For detailed analysis of this topic, please visit the official page: Worldwide Non-Filtering Cloth Vacuum Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Twist-Dispensing Closure Market Hits USD 480.5 Million in 2025, Poised for 5.06% CAGR to USD 678.8 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Twist Dispensing Closure Market: Strategic Imperatives for 2026 — PW Consulting Insights
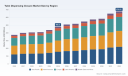
As manufacturers, brand owners, and investors prepare decisions for 2026, the Worldwide Twist Dispensing Closure market is entering a period that demands both operational rigor and strategic foresight. Our latest PW Consulting market study — anchored to a 2025 base year and projecting through 2032 — positions stakeholders to act with confidence. The market expanded from under USD 380 million in 2020 to roughly USD 480 million in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of approximately 5.06% across 2026–2032, reaching an estimated mid-to-high six‑hundred million dollar range by the end of the forecast window. These macro trajectories mask important inflection points that will determine winners and laggards in the coming 18–36 months.
Worldwide Twist Dispensing Closure Market
Why this report matters for 2026 decision-makers
-
Actionable foresight: Growth is steady but non-linear. The 5.06% CAGR reflects a market driven by regulatory impetus, sustainability transitions, and product convenience trends rather than simple volume expansion. Companies that treat 2026 as “more of the same” risk being overtaken by competitors that integrate compliance, circularity, and user experience into product roadmaps.
Worldwide Twist Dispensing Closure Market -
Regulatory and design convergence: Mandates for tethered closures, extended producer responsibility (EPR) programs, and heightened recyclability requirements are accelerating material and design changes. These changes translate into technical requirement shifts for tooling, line speeds, and material sourcing that are immediate and tangible for packaging operations.
Worldwide Twist Dispensing Closure Market -
Margin pressure and premiumization co-exist: While raw material volatility and recycling integration increase cost-to-serve for commodity closures, premium-end personal care and specialized pharmaceutical dispensing formats continue to offer margin expansion. The strategic choice — invest in higher-value product platforms or optimize for low-cost scale — must be evidence-based and timed to 2026 market realities.
What PW Consulting’s study delivers (practical, transaction-ready content)
-
Consolidated market sizing and seven-year forecast (2026–2032) with scenario analysis that isolates the impact of regulatory compliance costs, PCR adoption curves, and resin-price volatility.
-
Competitive benchmark suite: technology capability maps, manufacturing footprint overlays, and a proprietary scoring model for go-to-market readiness across dispensing formats.
-
Supply-chain and cost-sensitivity tools: index-driven models that translate resin price moves and conversion efficiency into gross-margin impacts at the SKU level.
-
Commercial playbooks for brand owners: prioritized product feature sets, recommended testing protocols, and phased transition timelines for mono-material and tethered closure adoption.
-
M&A and partnership intelligence: targets and alliance archetypes grounded in concentration metrics, capability gaps, and integration complexity assessments.
Competitive landscape — who to watch and why
The twist dispensing closure market is characterized by a mix of global platform players, regional specialists, and niche innovators. Market concentration is meaningful but far from monopolistic: the top three and top five manufacturers together account for a material slice of the market, leaving room for agile challengers and specialized entrants. This balance creates distinct strategic plays for incumbents and new entrants alike.
-
Large-platform manufacturers (Silgan Holdings, AptarGroup, Berry Global, Amcor): These firms combine global manufacturing scale with broad product portfolios that span consumer goods and pharmaceutical channels. Their strengths include high-speed application compatibility, extensive liner and sealing technology, and the ability to finance capital-intensive transitions such as mono-material tooling. Expect them to lead in large-volume tenders and rapid compliance roll-outs.
-
Specialists and system integrators (Closure Systems International, Mold‑Rite Plastics / Weatherchem & Stull lines, TriMas Packaging): These players win on customization, rapid prototyping, and close alignment with OEM fill-line requirements. Their nimbleness is an asset for brand owners seeking differentiated dispensing functions — e.g., child-resistant mechanisms or low-friction dispensing for viscous formulas.
-
Distribution and service-centric providers (O.Berk, regional converters, and family-owned manufacturers): These firms capitalize on customer intimacy and aftermarket services, such as rapid color matching, regional inventory support, and specialty cap finishes that matter to CPG customers with complex SKUs.
-
European technology leaders (BERICAP, Guala Closures): With deep experience in tamper-evidence, safety closures, and compliance-driven formats, these companies are often first movers on regulatory-driven designs, particularly tethered and long-term recyclability solutions.
Recent product activity underscores this competitive dynamic: Aptar’s 2024 launch of a child‑resistant, eco-conscious twist dispensing closure for personal care is emblematic of the “sustainability + safety” innovation vector. Similarly, new two-part designs that pair PCR-compatible overcaps with engineered seals — introduced in 2026 — demonstrate how material science and modular design are converging to meet both regulatory and performance targets.
Market dynamics shaping 2026 actions
-
Materials and cost pressures: Twist dispensers remain dominated by polypropylene (PP) and high-density polyethylene (HDPE) in design and production. Regional feedstock pricing differentials and intermittent supply constraints will continue to influence sourcing strategies. Companies should treat resin-market dynamics as an operational risk that can rapidly affect product-level margins.
-
Regulatory catalysts: EPR schemes in Europe and expanding rules in North America, combined with the EU’s single-use plastics mandate for tethered beverage closures, have crystallized timelines for design changes. These external deadlines compress R&D and line-conversion timetables, necessitating early decisions on retrofit vs. greenfield investments.
-
Recyclability and PCR integration: The dual pressures of compliance and retailer sustainability programs are pushing manufacturers toward mono-material formats and validated PCR content. Adoption is uneven by segment — but by 2026, PCR readiness will be a procurement pre-requisite for many blue‑chip customers.
-
Technology and line-speed trade-offs: Design choices that improve recyclability or add functions (tethering, child resistance) often affect fill-line cycle times. The cost calculus must compare incremental part cost and capex for conversion against customer willingness to pay or contractual compliance requirements.
Strategic recommendations for 2026
-
Prioritize product-platform bifurcation: Define “commodity” and “premium/regulatory” product families with separate roadmaps. For commodity closures, optimize cost and supply resilience. For regulated or premium formats, invest in design-for-recyclability and feature differentiation (e.g., child-resistance, dosing accuracy).
-
Accelerate supplier and resin diversification: Establish multi-sourcing arrangements and regional hedges for PP/HDPE. Negotiate formulaic contracts that share resin risk between converter and brand owner where possible.
-
Invest in conversion flexibility: Where justified by customer mix, prioritize modular tooling and adaptable application heads that can accommodate tethered, mono-material, and hybrid sealing technologies without full line replacement.
-
Use M&A and partnerships selectively: Given moderate market concentration, M&A can be a fast route to capability acquisition — particularly for niche technology (e.g., advanced child-resistant systems) or for expanding into premium personal-care dispensing. Alternatively, strategic licensing and co-development can de‑risk technical adoption.
-
Embed regulatory scenarios in commercial planning: Treat EPR and mandatory tethering not as one-off compliance costs but as multi-year strategic drivers that will reshape SKUs, packaging specs, and supplier selection criteria.
-
Leverage the PW Consulting toolkit: Use our cost-sensitivity models and supplier maps to quantify the P&L impact of design choices and to create defensible pricing proposals for customers during 2026 negotiations.
How to use this insight — and where to find the withheld details
The narrative above outlines the strategic contours every executive should consider in 2026. The full PW Consulting report contains the granular segmentation, regional and end-use breakdowns, and SKU-level price and volume tables that underpin these conclusions. We have intentionally presented deep strategic context while withholding the core segmented datasets — including detailed regional and application splits and proprietary share tables — to encourage direct engagement with the full research package. For procurement managers, R&D leads, and corporate development teams, those datasets are the working files for scenario planning, supplier negotiations, and transaction due diligence.
In short: the market is growing at a steady mid-single-digit rate, driven more by regulatory and sustainability mandates, product differentiation, and changing material economics than by sheer volume growth alone. Companies that align product architecture, sourcing strategies, and go‑to‑market models to these forces in 2026 will capture the outsized opportunities embedded in the broader market expansion.
To access the comprehensive data tables, scenario models, and supplier benchmarking that support these insights, please consult the full PW Consulting report available on our website. The detailed segment-level intelligence and downloadable decision-support tools are provided exclusively in the full report.
For detailed analysis of this topic, please visit the official page: Worldwide Twist Dispensing Closure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Portable Chromatography Systems Market Set to Expand at 5.86% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Portable Chromatography Systems Market — Strategic Briefing for 2026 Decisions
As organizations plan capital allocation, R&D prioritization, and M&A activity for 2026, portable chromatography systems are moving from niche field instruments to mission-critical assets across environmental monitoring, public safety, food safety, and decentralized clinical testing. PW Consulting’s latest market study — anchored on 2025 as the base year and projecting through 2032 — provides the actionable intelligence executives need to translate growing demand into defensible growth strategies.
Worldwide Portable Chromatography Systems Market
Market snapshot: traction, trajectory, and concentration
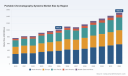
The portable chromatography market has demonstrated steady expansion through the early 2020s, and our modeling confirms continued growth into the latter part of the decade. The market reached a defined milestone in 2025 and, under the base-case scenario, advances at a compound annual growth rate (CAGR) of 5.86% across the 2026–2032 forecast window. By 2032 the market is expected to be materially larger than in 2025, reflecting structural demand drivers such as regulatory tightening, proliferation of field-deployable testing programs, and improvements in instrument miniaturization and power management.
Worldwide Portable Chromatography Systems Market
Market structure matters: competitive concentration at the top end is meaningful but not terminal. The three-largest competitors account for a notable share of market revenues, and the five-largest capture a clear majority — a landscape that supports both scale-driven incumbency and targeted disruption by niche or fast-innovating players. For strategic planners, this means scale-related advantages coexist with pockets of opportunity for specialized offerings, partnerships, and regional plays.
Worldwide Portable Chromatography Systems Market
Why this matters for 2026 strategy
- Procurement and CapEx planning: Procurement managers should expect steady demand and pricing stability for core portable chromatography platforms, but must budget for incremental costs tied to regulatory compliance and field-hardened configurations.
- R&D and product roadmaps: Product leaders should prioritize battery endurance, system ruggedization, embedded analytics, and simplified sample handling. The ROI window for modular, upgradeable architectures is narrowing — buy/borrow/build decisions made in 2026 will determine platform relevance through the next technology cycle.
- M&A and partnerships: With top-tier vendors occupying a substantial share of the market, acquisitive strategies that target technical IP, specialized consumables, or local service networks can accelerate market entry without requiring head-on competition with scaled incumbents.
Technology and application trends shaping the market
Three interlocking technology themes are shaping competitive differentiation and buyer adoption:
- Miniaturization with performance parity: Advances in microfluidics, low-dead-volume fittings, and compact detectors are compressing the performance gap between laboratory and field systems. Buyers increasingly evaluate portable platforms on whether they can deliver "lab-comparable" data rather than on size alone.
- Systems thinking for field deployment: Robust power management (battery swap vs. integrated packs), sealed sample paths, and simplified consumable replacement are moving from nice-to-have to procurement prerequisites, especially for first responders and environmental agencies.
- Embedded analytics and connectivity: Instrument manufacturers that provide validated, cloud-enabled analytics and secure data chains for regulatory traceability are gaining preferential access to procurement lists in regulated verticals.
Regulatory, reimbursement, and supply dynamics — operational levers for 2026
Regulatory and reimbursement frameworks are key determinants of adoption speed and how product features are prioritized:
- Laboratory accreditation impacts product claims: Portable platforms intended to support clinical workflows must align with laboratory accreditation standards such as ISO 15189:2022. This influences validation protocols, documentation, and the degree of on-device automation required for reliable point-of-care reporting.
- Reimbursement pathways accelerate adoption in outpatient settings: Existing procedural codes can be leveraged to create viable business cases for decentralized chromatography use cases. For example, relevant CPT designations exist that cover column-chromatography procedures, and commercial teams should map device capabilities to billable activities in target markets.
- Consumable and materials supply are non-trivial cost drivers: High-specification materials used in portable systems — including USP Class-compliant tubing and connectors — command premiums relative to commodity counterparts and affect unit economics, service pricing, and SCM strategies. Expect procurement to weigh total cost of ownership rather than headline device price when evaluating offerings.
Competitive landscape — what leading providers are doing
The competitive field is anchored by legacy analytical instrument manufacturers that are evolving portable variants of established platforms while new entrants pursue modular and specialist use cases. Highlights from leading firms:
- Agilent Technologies (Santa Clara, CA): Continuing to leverage its chromatography heritage, Agilent is packaging high-performance LC configurations into portable formats, with recent product enhancements emphasizing battery operation and field-forward purity testing. Their strategy combines platform familiarity with incremental portability innovations.
- Thermo Fisher Scientific (Waltham, MA): Thermo Fisher’s approach centers on modularity and regulatory readiness. Their portable ion chromatography upgrades have obtained CE marking for environmental monitoring in key jurisdictions, underscoring a compliance-first go-to-market stance.
- Waters Corporation (Milford, MA): Waters focuses on portable UPLC variants for bioanalysis, stressing compact hardware married with validated software workflows — a competitive posture that appeals to life-science customers requiring traceable, high-throughput field assays.
- Shimadzu Corporation (Kyoto, Japan): Shimadzu has been active in showcasing portable UHPLC configurations at major trade shows, emphasizing integrated autosampling and the applicability to clinical and food-safety contexts.
- PerkinElmer (Waltham, MA): PerkinElmer targets on-site environmental and forensic chromatography through cart-based LC-MS kits that balance mobility with analytical robustness — a proposition for agencies needing laboratory-grade confirmation in the field.
- Scion Instruments (Livingston, UK): As a specialist, Scion prioritizes modular portable gas chromatography systems for VOC and oil & gas applications, demonstrating that focused product-playbooks can capture vertical share even with incumbent competition.
Recent vendor activity underscores the iterate-and-deploy dynamics in the sector: product launches with battery operation, regulatory clearances for portable IC upgrades, and trade-show debuts of new autosampling capabilities all signal that vendors are moving beyond proof-of-concept devices to commercially viable, field-ready offerings.
What PW Consulting’s report delivers — practical outputs for executives
Our report is built to be directly operationalizable for business leaders making 2026 decisions. Highlights include:
- Proprietary market-sizing and scenario modeling: Transparent methodology with base-year validation, upside/downside scenarios, and sensitivity analyses tied to regulatory adoption rates and capital procurement cycles.
- Decision-grade competitive intelligence: Standardized vendor profiles, capability matrices, and go-to-market playbooks that allow rapid benchmarking and M&A target screening.
- Commercial playbooks for sales and channel strategy: Segmented buyer personas, procurement triggers, pricing sensitivity curves, and recommended channel structures for rapid market penetration.
- Technical and validation checklists: Engineering requirements for portable deployment, validation protocols aligned to accreditation standards, and a consumables/SLA model to support aftermarket revenue forecasting.
- Regulatory and reimbursement navigator: Jurisdictional guidance on device claims, clinical accreditation impacts, and mapping to applicable procedural codes that support revenue realization.
- M&A and partnership roadmap: Deal archetypes, valuation benchmarks, and integration templates for bolt-on acquisitions or technology licensing.
Actionable recommendations for 2026
- Buyers: Treat portable chromatography procurement as a systems purchase — evaluate instrument, consumables, service, and data workflow as a single P&L item. Prioritize devices with field validation packages and clear regulatory claim paths.
- Vendors: Invest in modularity and warranty/service frameworks. Differentiate through validated analytics and secure data management to meet the traceability expectations of regulated buyers.
- Investors/M&A teams: Seek targets that either (a) extend incumbent platforms into high-growth verticals via software-enabled workflows or (b) own niche consumables/service ecosystems that create sticky recurring revenue.
- Public agencies and NGOs: Leverage procurement pilots to quantify total cost of ownership and operational impact; prioritize interoperability standards to maximize supplier competition and rapid deployment during incidents.
Conclusion — why 2026 is a pivotal planning year
Portable chromatography is at an inflection point: technology maturation, regulatory clarity in several use cases, and a steady market expansion create a unique window for shaping long-term positioning. Whether you are prioritizing product development, channel expansion, or acquisition, 2026 decisions will materially influence who wins the next phase of market growth.
PW Consulting’s Worldwide Portable Chromatography Systems Market report supplies the detailed evidence base, playbooks, and risk-assessment tools to convert market momentum into sustainable share. To access the full dataset, complete vendor profiles, segmentation detail, and tactical recommendations, please visit our report page for a full download and executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Portable Chromatography Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com