

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
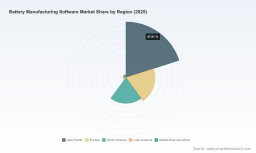
PW Consulting: Worldwide Battery Manufacturing Software Market to Rise from USD 1,127.29 Million in 2025 to USD 3,642.24 Million by 2032 at 18.24% CAGR; EV Batteries (USD 710.19 Million) and Asia‑Pacific (USD 538.91 Million) Drive Growth

Worldwide Battery Manufacturing Software Market — Strategic Preview for 2026 Decision Makers
PW Consulting today releases the executive trailer for our forthcoming market study, "Worldwide Battery Manufacturing Software Market." This briefing summarizes the report’s strategic value for corporate leadership and investors preparing decisions in 2026. It highlights why the battery-software layer has become a board-level issue, how the market is evolving at scale, and what practical guidance our full report delivers — while intentionally reserving granular segment-level tables and forecasts for subscribers.
Worldwide Battery Manufacturing Software Market
Why battery-manufacturing software will shape 2026
Battery manufacturing is no longer a pure electrochemical or automation play; it is an information and software challenge. Our analysis shows the addressable market for software that orchestrates, monitors, and optimizes battery cell and pack production has expanded rapidly over the past five years and is poised for sustained double‑digit growth. On a compound basis, the market is projected to grow at a CAGR of 18.24% over the forecast horizon beginning from the 2026 baseline. Historical traction (2020–2025) and near-term forecasts (2026–2032) demonstrate both the replacement and greenfield demand dynamics — from gigafactory digitalization to traceability, analytics, and integrated MES/MOM deployments.
Worldwide Battery Manufacturing Software Market
Key takeaways for executive teams: software is now a primary lever for yield improvement, compliance readiness (traceability, passporting), and capital-efficiency in factory ramp-ups. The speed and scale of software adoption — not only the choice of platform — will determine which manufacturers realize projected margin expansion and faster time-to-market in 2026.
Worldwide Battery Manufacturing Software Market
Macro trajectory at a glance
-
Historical growth (2020–2025) shows consistent year-over-year expansion as manufacturers moved from pilots to production-scale deployments.
-
The market base year for our analysis is 2025. From that base, our forecast period extends from 2026 through 2032 and includes scenario modelling for conservative, base, and accelerated demand pathways.
-
By modeling technology adoption curves, regulatory drivers, and factory ramp cycles, PW Consulting estimates the market will continue to expand meaningfully through 2032 under the base scenario (CAGR 18.24%).
-
Market concentration is moderate: the top three vendors account for roughly a third of market revenues (CR3 ≈ 34.2%), while the top five approach half of the market (CR5 ≈ 48.15%). This mix indicates room for both established industrial software providers and focused analytics specialists to capture opportunity through differentiation and partnerships.
What the research contains — practical, transaction-ready deliverables
Our full report is designed as an operational playbook for procurement committees, digital transformation leads, and corporate strategy teams evaluating investments in 2026. Highlights include:
-
Market size model and revenue waterfall: an auditable time series across the historical window and multi-year forecast, with clear assumptions and sensitivity endpoints.
-
Vendor landscaping and capability matrices: comparative scorecards on MES/MOM, quality management, simulation & design, asset performance, and data/AI platforms — emphasizing integration risk and scalability for gigafactories.
-
Use‑case ROI templates: pre-configured calculators for yield improvement, energy optimization, labor reduction, and ramp time compression — enabling CFOs to quantify payback over 12–36 months.
-
Implementation playbooks: staged roadmaps for pilots → scale, including data architecture patterns, cybersecurity controls, change management milestones, and vendor selection checklists.
-
Regulatory and compliance annexes: requirements mapping (including battery passport readiness), traceability architectures, and recommended audit controls for 2026 compliance schedules.
-
Scenario stress tests: impact analyses of policy interventions, energy cost shocks, and differing rate-of-ramp assumptions on software demand and vendor revenue streams.
Competitive landscape — winners, challengers, and partners
The vendor universe spans global industrial-software incumbents, automation leaders, and niche analytics specialists. In the report we profile strategic and execution differences among them and identify where partnerships and M&A will be decisive for scale.
-
Industrial incumbents with broad digital-thread portfolios — companies such as GE Vernova, Siemens, Rockwell Automation, ABB — bring deep MES/MOM expertise and plant-level automation integration. Their strategic advantage lies in end-to-end operational continuity, field-proven scalability, and existing relationships with OEMs and gigafactories.
-
Automation and software convergence plays — exemplified by Panasonic Connect’s recent launch of an end-to-end MES designed for EV battery lines — show how traditional manufacturers are building platform offerings to accelerate customer digital transformation and onshore capacity expansions.
-
Emerging analytics specialists — companies such as Voltaiq, Energsoft, and PDF Solutions — compete on depth of battery-domain analytics, flexible deployment models, and R&D-to-production data continuity. These firms often command premium valuations when they prove the ability to shift insights into measurable yield and quality outcomes.
-
New product introductions (e.g., Honeywell’s Battery MXP in mid-2024) underline a shift: vendors emphasize AI-enabled operations that claim significant reductions in startup scrap and ramp time compression, positioning software as a critical source of competitive differentiation for factory operators.
Regulatory, operational, and cost drivers — what accelerates adoption in 2026
-
Regulatory pressure: Mandatory requirements around traceability and carbon-footprint declarations (e.g., upcoming battery passport regimes) are forcing manufacturers to deploy software that guarantees provenance and auditable lifecycle data.
-
Onshoring and policy stimulus: Recent policy incentives have driven dramatic capacity growth in some industries; software integration and cross-border data sovereignty considerations are material procurement factors.
-
Labor and energy economics: In a baseline 40 GWh/a lithium-ion facility, labor represents a measurable share of operating cost — and digitalization can deliver incremental staff reductions and process automation. Separately, energy‑tracking and optimization use cases have potential for nearly double‑digit reductions in energy consumption for high-intensity stages of production. The combined effect materially improves per‑kWh cost curves and shortens payback windows for software investments.
-
Cybersecurity and standards: Compliance with standards such as ISO 21434 and IEC 62443, and implementation of end-to-end encryption (e.g., AES‑256, TLS 1.3) are no longer optional for connected manufacturing environments; they are procurement gatekeepers for enterprise buyers.
Strategic recommendations for 2026 planning
-
For battery manufacturers: Treat software procurement as capital investment. Use PW Consulting’s ROI templates to benchmark vendor claims, prioritizing projects that improve yield, reduce scrap, and compress ramp time. Reserve 20–30% of digital transformation budgets for data‑ops and cybersecurity hardening.
-
For software vendors: Differentiate on outcome-focused integrations — demonstrate validated yield improvements and clear compliance mappings. Consider flexible commercial models (subscription + performance‑share) to lower adoption barriers at scale.
-
For systems integrators and consultants: Build industry-specific accelerators (pre-built data models, traceability modules, cybersecurity baselines) to shorten time-to-value for customers and capture upstream advisory margins tied to plant commissioning.
-
For investors and M&A teams: Target assets that combine domain analytics with validated production deployments. Our market concentration analysis suggests consolidation potential where vertical integration of MES and analytics creates defensible bundles.
-
For policymakers and regulators: Collaborate with industry to design data‑sharing architectures that meet traceability goals without creating export‑blocking data‑sovereignty constraints; adopt phased compliance thresholds to avoid creating retrofit liabilities for nascent factories.
How PW Consulting’s report helps you act in 2026
If your roadmap for 2026 includes factory expansions, vendor selection, or investment allocation in battery manufacturing software, this report turns market rhetoric into actionable decisions. It combines a transparent financial model, vendor scorecards, implementation playbooks, and scenario analyses that allow procurement committees and executive teams to stress-test choices under specific ramp and regulatory timelines. Importantly, the full report contains the granular segmentation tables, regional and end‑use splits, and vendor revenue estimates — information that is intentionally embargoed here to preserve independent subscriber value.
Next steps and how to access the full analysis
PW Consulting’s full "Worldwide Battery Manufacturing Software Market" report is structured to be adoption-ready: it includes executable checklists, contract negotiation playbooks, and CFO‑grade ROI memos tailored to 2026 budgeting cycles. For teams preparing capital approvals or negotiating vendor pilots this year, the report provides the evidence base to move from pilots to plant-scale deployments with confidence.
To obtain the complete dataset, vendor profiles, and the segmented forecast tables that support scenario modelling, please visit our report subscription page or contact PW Consulting’s industry research desk. Our advisory team is available to run bespoke workshops that apply the report’s models to your specific production and regulatory context.
PW Consulting — providing the strategic intelligence that lets leaders turn software investment into factory advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Battery Manufacturing Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com