

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Areca Nut Market Hits USD 1,008.0 Million in 2025 — Growth Momentum Ahead

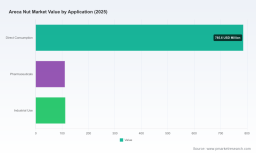
Worldwide Areca Nut Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting today releases its authoritative market brief — Worldwide Areca Nut Market — built to translate a complex mix of trade policy shifts, supply‑side pressures, and regulatory headwinds into operationally actionable intelligence for executives planning through 2026 and beyond. Anchored on a 2025 base year and a detailed forecast covering 2026–2032, our analysis shows the global areca nut market at USD 1,008.0 Million in 2025, growing at a compound annual growth rate (CAGR) of 3.88% across the forecast window. This release is a strategic “trailer”: it demonstrates the depth of our analytics and practical frameworks while guiding readers to the full report and datasets for transaction‑grade decision support.
Worldwide Areca Nut Market
Why this report matters for 2026 strategy
-
Trade and regulatory regimes are in flux. Exporters and buyers face evolving compliance demands (including heightened scrutiny from major food safety regulators) that directly affect market access and distribution economics.
Worldwide Areca Nut Market -
Supply fundamentals are changing. Input inflation, localized mechanization programs and new processing capacity are altering cost curves and the structure of competitiveness at farm and processor levels.
Worldwide Areca Nut Market -
Market concentration and vertical strategies are reshaping value capture. A modestly concentrated producer/processor pool creates both opportunities for scale plays and niches for premium positioning.
What’s inside the PW Consulting report (operational content highlights)
-
Transparent market sizing and demand scenarios — baseline, downside (regulatory shock), and upside (value‑added adoption) — with an integrated financial model for commercial diligence.
-
Supply chain mapping down to farmgate economics, post‑harvest loss vectors, and processing cost drivers so procurement managers can quantify sourcing risk and redesign supplier agreements.
-
Regulatory risk matrix and mitigation playbook covering export compliance, labeling and ingredient restrictions, and jurisdictional bans, including trigger points for immediate supply diversification.
-
Competitive landscaping and company dossiers — proprietary profiles and capability matrices for the leading cooperatives, processors, traders and exporters in key origin countries.
-
Operational toolkits: margin ladders, capex sizing templates for processing upgrades, mechanization adoption calculators, and RFP checklists for sorting/packaging lines and traceability systems.
-
Scenario‑based M&A playbooks, including target archetypes, valuation sensitives and integration checklists tailored to strategic buyers and financial sponsors.
Macro takeaways you can act on now
-
Measured growth with pockets of disruption. The 3.88% CAGR embedded in our forecast reflects steady global demand tempered by regulatory pressures and trade volatility. Executives should expect portfolio‑level growth rather than uniform expansion across channels.
-
Geography still matters. Market volume and processing capacity are concentrated in a handful of origin regions, with newer clusters emerging due to targeted public investment and private plant commissioning. This creates asymmetric risk — and asymmetric opportunities — for agile players.
-
Scale versus specialization trade‑offs. The market’s concentration metrics (CR3: 42.3%; CR5: 58.15%) point to a competitive landscape where scale buys reach and bargaining power, while specialized processors can win premium margins via quality control, certification and downstream integration.
Competitive landscape: who is shaping the market
The sector is populated by a mix of farmer cooperatives, regional processors, export houses and trader‑specialists. Cooperative aggregators focused on membership procurement and value addition are consolidating buying power and improving traceability, while private processors and exporters continuously upgrade sorting, hygienic handling and packaging to meet stricter buyer specifications. Notable operational movements in early 2026 illustrate these dynamics: a large cooperative broke ground on an expanded warehousing and procurement hub to strengthen farmer linkages; a state government rolled out subsidized processing cluster initiatives to reduce post‑harvest loss; exporters commissioned optical sorting and hygienic packaging lines to satisfy international buyers; and new high‑capacity processing plants were inaugurated in under‑served production belts to support regional cultivation expansion.
These developments underscore two strategic threads: (1) incumbents are investing to defend export channels and quality premiums; (2) local public investment is accelerating capital intensity at origin, changing the basis of competition from raw supply to processed, compliant throughput.
Regulatory and trade dynamics that will shape 2026 outcomes
-
Heightened import scrutiny in principal markets requires exporters to invest in documented quality systems. Ongoing import alerts and detention protocols maintained by major food safety authorities mean that non‑compliant shipments face material time‑to‑market and cost penalties.
-
Protectionist trade instruments in origin markets — including recent minimum import pricing and tariff adjustments — are influencing trade flows and filter directly into sourcing and pricing strategies for downstream buyers.
-
Persisting public health classifications have led to municipal restrictions, mandatory warnings and, in some instances, product bans. Companies must run jurisdictional regulatory heat maps and include litigation/regulatory risk premiums in long‑term planning.
Operational and raw‑material pressures
Farmers and processors are contending with rising agricultural input costs and localized labor constraints. Input inflation — in part driven by global fertilizer and agrochemical price moves — is increasing smallholder production costs by approximately one digit percentage in affected origins. That trend amplifies the value of aggregation, input financing solutions and productivity‑enhancing investments (e.g., mechanized harvest support and improved post‑harvest handling) to compress total landed cost.
Strategic playbook for 2026 decision‑makers
-
De‑risk export exposure: implement a compliance assurance program (certifications, pre‑shipment testing, documented chain of custody) and diversify market channels to reduce single‑market dependency.
-
Upgrade processing to capture premium margins: prioritize investments in optical sorting, hygienic packaging and traceable supply chains where modelled payback is within three–five years under our baseline case.
-
Partner with cooperatives and cluster programs: structured off‑take and input support contracts reduce procurement volatility and create scalable raw material pipelines.
-
Adopt scenario planning as governance routine: board‑level stress tests should include acute regulatory shock and sustained demand contraction scenarios; set contingent KPIs and liquidity buffers accordingly.
-
Reconfigure sourcing agreements: move from spot buying to hybrid contracts (indexed base price + quality premium) tied to recognized quality metrics and compliance milestones.
M&A and partnership implications
Given the sector’s middling concentration, there is strategic logic for both horizontal consolidation and bolt‑on deals that expand processing capacity or buyer access. Buyers should prioritize targets that (a) demonstrate documented quality controls and export compliance, (b) have access to farmer networks or cooperative relationships, and (c) possess processing upgrades that materially improve yield and reduce rejection rates. Our acquisition assessment matrix in the full report quantifies integration cost, expected margin uplift and time‑to‑value against regulatory and market risk scenarios.
How PW Consulting supports implementation
Our full engagement package includes granular market models, a live Excel toolkit for scenario and sensitivity analysis, on‑the‑ground supplier benchmarking templates, and downloadable due‑diligence checklists tailored for strategic and financial buyers. We also provide bespoke workshops to operationalize the report’s playbook — from capex prioritization for processing lines to drafting export compliance SOPs and supplier scorecards.
Final note — the trailer and next steps
This briefing highlights the high‑value insights contained in PW Consulting’s Worldwide Areca Nut Market study and explains why 2026 is a pivotal year for strategic repositioning. We intentionally present top‑level sizing and directional analytics here, while preserving the full modeling, sub‑segment outputs, and transaction‑grade datasets for the complete report. To obtain the full study, access the downloadable models, or commission an executive briefing tailored to your organization’s strategic questions, please visit our report page.
Leaders who act in 2026 with disciplined compliance programs, targeted processing investments, and pragmatic sourcing partnerships will convert a market characterized by steady growth and elevated risk into a durable source of competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Areca Nut Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com