

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Portable Chromatography Systems Market Set to Expand at 5.86% CAGR Through 2032

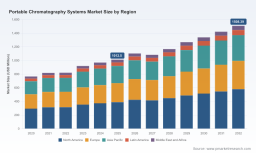
Worldwide Portable Chromatography Systems Market — Strategic Briefing for 2026 Decisions
As organizations plan capital allocation, R&D prioritization, and M&A activity for 2026, portable chromatography systems are moving from niche field instruments to mission-critical assets across environmental monitoring, public safety, food safety, and decentralized clinical testing. PW Consulting’s latest market study — anchored on 2025 as the base year and projecting through 2032 — provides the actionable intelligence executives need to translate growing demand into defensible growth strategies.
Worldwide Portable Chromatography Systems Market
Market snapshot: traction, trajectory, and concentration
The portable chromatography market has demonstrated steady expansion through the early 2020s, and our modeling confirms continued growth into the latter part of the decade. The market reached a defined milestone in 2025 and, under the base-case scenario, advances at a compound annual growth rate (CAGR) of 5.86% across the 2026–2032 forecast window. By 2032 the market is expected to be materially larger than in 2025, reflecting structural demand drivers such as regulatory tightening, proliferation of field-deployable testing programs, and improvements in instrument miniaturization and power management.
Worldwide Portable Chromatography Systems Market
Market structure matters: competitive concentration at the top end is meaningful but not terminal. The three-largest competitors account for a notable share of market revenues, and the five-largest capture a clear majority — a landscape that supports both scale-driven incumbency and targeted disruption by niche or fast-innovating players. For strategic planners, this means scale-related advantages coexist with pockets of opportunity for specialized offerings, partnerships, and regional plays.
Worldwide Portable Chromatography Systems Market
Why this matters for 2026 strategy
- Procurement and CapEx planning: Procurement managers should expect steady demand and pricing stability for core portable chromatography platforms, but must budget for incremental costs tied to regulatory compliance and field-hardened configurations.
- R&D and product roadmaps: Product leaders should prioritize battery endurance, system ruggedization, embedded analytics, and simplified sample handling. The ROI window for modular, upgradeable architectures is narrowing — buy/borrow/build decisions made in 2026 will determine platform relevance through the next technology cycle.
- M&A and partnerships: With top-tier vendors occupying a substantial share of the market, acquisitive strategies that target technical IP, specialized consumables, or local service networks can accelerate market entry without requiring head-on competition with scaled incumbents.
Technology and application trends shaping the market
Three interlocking technology themes are shaping competitive differentiation and buyer adoption:
- Miniaturization with performance parity: Advances in microfluidics, low-dead-volume fittings, and compact detectors are compressing the performance gap between laboratory and field systems. Buyers increasingly evaluate portable platforms on whether they can deliver "lab-comparable" data rather than on size alone.
- Systems thinking for field deployment: Robust power management (battery swap vs. integrated packs), sealed sample paths, and simplified consumable replacement are moving from nice-to-have to procurement prerequisites, especially for first responders and environmental agencies.
- Embedded analytics and connectivity: Instrument manufacturers that provide validated, cloud-enabled analytics and secure data chains for regulatory traceability are gaining preferential access to procurement lists in regulated verticals.
Regulatory, reimbursement, and supply dynamics — operational levers for 2026
Regulatory and reimbursement frameworks are key determinants of adoption speed and how product features are prioritized:
- Laboratory accreditation impacts product claims: Portable platforms intended to support clinical workflows must align with laboratory accreditation standards such as ISO 15189:2022. This influences validation protocols, documentation, and the degree of on-device automation required for reliable point-of-care reporting.
- Reimbursement pathways accelerate adoption in outpatient settings: Existing procedural codes can be leveraged to create viable business cases for decentralized chromatography use cases. For example, relevant CPT designations exist that cover column-chromatography procedures, and commercial teams should map device capabilities to billable activities in target markets.
- Consumable and materials supply are non-trivial cost drivers: High-specification materials used in portable systems — including USP Class-compliant tubing and connectors — command premiums relative to commodity counterparts and affect unit economics, service pricing, and SCM strategies. Expect procurement to weigh total cost of ownership rather than headline device price when evaluating offerings.
Competitive landscape — what leading providers are doing
The competitive field is anchored by legacy analytical instrument manufacturers that are evolving portable variants of established platforms while new entrants pursue modular and specialist use cases. Highlights from leading firms:
- Agilent Technologies (Santa Clara, CA): Continuing to leverage its chromatography heritage, Agilent is packaging high-performance LC configurations into portable formats, with recent product enhancements emphasizing battery operation and field-forward purity testing. Their strategy combines platform familiarity with incremental portability innovations.
- Thermo Fisher Scientific (Waltham, MA): Thermo Fisher’s approach centers on modularity and regulatory readiness. Their portable ion chromatography upgrades have obtained CE marking for environmental monitoring in key jurisdictions, underscoring a compliance-first go-to-market stance.
- Waters Corporation (Milford, MA): Waters focuses on portable UPLC variants for bioanalysis, stressing compact hardware married with validated software workflows — a competitive posture that appeals to life-science customers requiring traceable, high-throughput field assays.
- Shimadzu Corporation (Kyoto, Japan): Shimadzu has been active in showcasing portable UHPLC configurations at major trade shows, emphasizing integrated autosampling and the applicability to clinical and food-safety contexts.
- PerkinElmer (Waltham, MA): PerkinElmer targets on-site environmental and forensic chromatography through cart-based LC-MS kits that balance mobility with analytical robustness — a proposition for agencies needing laboratory-grade confirmation in the field.
- Scion Instruments (Livingston, UK): As a specialist, Scion prioritizes modular portable gas chromatography systems for VOC and oil & gas applications, demonstrating that focused product-playbooks can capture vertical share even with incumbent competition.
Recent vendor activity underscores the iterate-and-deploy dynamics in the sector: product launches with battery operation, regulatory clearances for portable IC upgrades, and trade-show debuts of new autosampling capabilities all signal that vendors are moving beyond proof-of-concept devices to commercially viable, field-ready offerings.
What PW Consulting’s report delivers — practical outputs for executives
Our report is built to be directly operationalizable for business leaders making 2026 decisions. Highlights include:
- Proprietary market-sizing and scenario modeling: Transparent methodology with base-year validation, upside/downside scenarios, and sensitivity analyses tied to regulatory adoption rates and capital procurement cycles.
- Decision-grade competitive intelligence: Standardized vendor profiles, capability matrices, and go-to-market playbooks that allow rapid benchmarking and M&A target screening.
- Commercial playbooks for sales and channel strategy: Segmented buyer personas, procurement triggers, pricing sensitivity curves, and recommended channel structures for rapid market penetration.
- Technical and validation checklists: Engineering requirements for portable deployment, validation protocols aligned to accreditation standards, and a consumables/SLA model to support aftermarket revenue forecasting.
- Regulatory and reimbursement navigator: Jurisdictional guidance on device claims, clinical accreditation impacts, and mapping to applicable procedural codes that support revenue realization.
- M&A and partnership roadmap: Deal archetypes, valuation benchmarks, and integration templates for bolt-on acquisitions or technology licensing.
Actionable recommendations for 2026
- Buyers: Treat portable chromatography procurement as a systems purchase — evaluate instrument, consumables, service, and data workflow as a single P&L item. Prioritize devices with field validation packages and clear regulatory claim paths.
- Vendors: Invest in modularity and warranty/service frameworks. Differentiate through validated analytics and secure data management to meet the traceability expectations of regulated buyers.
- Investors/M&A teams: Seek targets that either (a) extend incumbent platforms into high-growth verticals via software-enabled workflows or (b) own niche consumables/service ecosystems that create sticky recurring revenue.
- Public agencies and NGOs: Leverage procurement pilots to quantify total cost of ownership and operational impact; prioritize interoperability standards to maximize supplier competition and rapid deployment during incidents.
Conclusion — why 2026 is a pivotal planning year
Portable chromatography is at an inflection point: technology maturation, regulatory clarity in several use cases, and a steady market expansion create a unique window for shaping long-term positioning. Whether you are prioritizing product development, channel expansion, or acquisition, 2026 decisions will materially influence who wins the next phase of market growth.
PW Consulting’s Worldwide Portable Chromatography Systems Market report supplies the detailed evidence base, playbooks, and risk-assessment tools to convert market momentum into sustainable share. To access the full dataset, complete vendor profiles, segmentation detail, and tactical recommendations, please visit our report page for a full download and executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Portable Chromatography Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com