

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
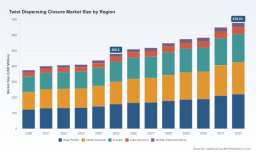
PW Consulting: Worldwide Twist-Dispensing Closure Market Hits USD 480.5 Million in 2025, Poised for 5.06% CAGR to USD 678.8 Million by 2032

Worldwide Twist Dispensing Closure Market: Strategic Imperatives for 2026 — PW Consulting Insights
As manufacturers, brand owners, and investors prepare decisions for 2026, the Worldwide Twist Dispensing Closure market is entering a period that demands both operational rigor and strategic foresight. Our latest PW Consulting market study — anchored to a 2025 base year and projecting through 2032 — positions stakeholders to act with confidence. The market expanded from under USD 380 million in 2020 to roughly USD 480 million in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of approximately 5.06% across 2026–2032, reaching an estimated mid-to-high six‑hundred million dollar range by the end of the forecast window. These macro trajectories mask important inflection points that will determine winners and laggards in the coming 18–36 months.
Worldwide Twist Dispensing Closure Market
Why this report matters for 2026 decision-makers
-
Actionable foresight: Growth is steady but non-linear. The 5.06% CAGR reflects a market driven by regulatory impetus, sustainability transitions, and product convenience trends rather than simple volume expansion. Companies that treat 2026 as “more of the same” risk being overtaken by competitors that integrate compliance, circularity, and user experience into product roadmaps.
Worldwide Twist Dispensing Closure Market -
Regulatory and design convergence: Mandates for tethered closures, extended producer responsibility (EPR) programs, and heightened recyclability requirements are accelerating material and design changes. These changes translate into technical requirement shifts for tooling, line speeds, and material sourcing that are immediate and tangible for packaging operations.
Worldwide Twist Dispensing Closure Market -
Margin pressure and premiumization co-exist: While raw material volatility and recycling integration increase cost-to-serve for commodity closures, premium-end personal care and specialized pharmaceutical dispensing formats continue to offer margin expansion. The strategic choice — invest in higher-value product platforms or optimize for low-cost scale — must be evidence-based and timed to 2026 market realities.
What PW Consulting’s study delivers (practical, transaction-ready content)
-
Consolidated market sizing and seven-year forecast (2026–2032) with scenario analysis that isolates the impact of regulatory compliance costs, PCR adoption curves, and resin-price volatility.
-
Competitive benchmark suite: technology capability maps, manufacturing footprint overlays, and a proprietary scoring model for go-to-market readiness across dispensing formats.
-
Supply-chain and cost-sensitivity tools: index-driven models that translate resin price moves and conversion efficiency into gross-margin impacts at the SKU level.
-
Commercial playbooks for brand owners: prioritized product feature sets, recommended testing protocols, and phased transition timelines for mono-material and tethered closure adoption.
-
M&A and partnership intelligence: targets and alliance archetypes grounded in concentration metrics, capability gaps, and integration complexity assessments.
Competitive landscape — who to watch and why
The twist dispensing closure market is characterized by a mix of global platform players, regional specialists, and niche innovators. Market concentration is meaningful but far from monopolistic: the top three and top five manufacturers together account for a material slice of the market, leaving room for agile challengers and specialized entrants. This balance creates distinct strategic plays for incumbents and new entrants alike.
-
Large-platform manufacturers (Silgan Holdings, AptarGroup, Berry Global, Amcor): These firms combine global manufacturing scale with broad product portfolios that span consumer goods and pharmaceutical channels. Their strengths include high-speed application compatibility, extensive liner and sealing technology, and the ability to finance capital-intensive transitions such as mono-material tooling. Expect them to lead in large-volume tenders and rapid compliance roll-outs.
-
Specialists and system integrators (Closure Systems International, Mold‑Rite Plastics / Weatherchem & Stull lines, TriMas Packaging): These players win on customization, rapid prototyping, and close alignment with OEM fill-line requirements. Their nimbleness is an asset for brand owners seeking differentiated dispensing functions — e.g., child-resistant mechanisms or low-friction dispensing for viscous formulas.
-
Distribution and service-centric providers (O.Berk, regional converters, and family-owned manufacturers): These firms capitalize on customer intimacy and aftermarket services, such as rapid color matching, regional inventory support, and specialty cap finishes that matter to CPG customers with complex SKUs.
-
European technology leaders (BERICAP, Guala Closures): With deep experience in tamper-evidence, safety closures, and compliance-driven formats, these companies are often first movers on regulatory-driven designs, particularly tethered and long-term recyclability solutions.
Recent product activity underscores this competitive dynamic: Aptar’s 2024 launch of a child‑resistant, eco-conscious twist dispensing closure for personal care is emblematic of the “sustainability + safety” innovation vector. Similarly, new two-part designs that pair PCR-compatible overcaps with engineered seals — introduced in 2026 — demonstrate how material science and modular design are converging to meet both regulatory and performance targets.
Market dynamics shaping 2026 actions
-
Materials and cost pressures: Twist dispensers remain dominated by polypropylene (PP) and high-density polyethylene (HDPE) in design and production. Regional feedstock pricing differentials and intermittent supply constraints will continue to influence sourcing strategies. Companies should treat resin-market dynamics as an operational risk that can rapidly affect product-level margins.
-
Regulatory catalysts: EPR schemes in Europe and expanding rules in North America, combined with the EU’s single-use plastics mandate for tethered beverage closures, have crystallized timelines for design changes. These external deadlines compress R&D and line-conversion timetables, necessitating early decisions on retrofit vs. greenfield investments.
-
Recyclability and PCR integration: The dual pressures of compliance and retailer sustainability programs are pushing manufacturers toward mono-material formats and validated PCR content. Adoption is uneven by segment — but by 2026, PCR readiness will be a procurement pre-requisite for many blue‑chip customers.
-
Technology and line-speed trade-offs: Design choices that improve recyclability or add functions (tethering, child resistance) often affect fill-line cycle times. The cost calculus must compare incremental part cost and capex for conversion against customer willingness to pay or contractual compliance requirements.
Strategic recommendations for 2026
-
Prioritize product-platform bifurcation: Define “commodity” and “premium/regulatory” product families with separate roadmaps. For commodity closures, optimize cost and supply resilience. For regulated or premium formats, invest in design-for-recyclability and feature differentiation (e.g., child-resistance, dosing accuracy).
-
Accelerate supplier and resin diversification: Establish multi-sourcing arrangements and regional hedges for PP/HDPE. Negotiate formulaic contracts that share resin risk between converter and brand owner where possible.
-
Invest in conversion flexibility: Where justified by customer mix, prioritize modular tooling and adaptable application heads that can accommodate tethered, mono-material, and hybrid sealing technologies without full line replacement.
-
Use M&A and partnerships selectively: Given moderate market concentration, M&A can be a fast route to capability acquisition — particularly for niche technology (e.g., advanced child-resistant systems) or for expanding into premium personal-care dispensing. Alternatively, strategic licensing and co-development can de‑risk technical adoption.
-
Embed regulatory scenarios in commercial planning: Treat EPR and mandatory tethering not as one-off compliance costs but as multi-year strategic drivers that will reshape SKUs, packaging specs, and supplier selection criteria.
-
Leverage the PW Consulting toolkit: Use our cost-sensitivity models and supplier maps to quantify the P&L impact of design choices and to create defensible pricing proposals for customers during 2026 negotiations.
How to use this insight — and where to find the withheld details
The narrative above outlines the strategic contours every executive should consider in 2026. The full PW Consulting report contains the granular segmentation, regional and end-use breakdowns, and SKU-level price and volume tables that underpin these conclusions. We have intentionally presented deep strategic context while withholding the core segmented datasets — including detailed regional and application splits and proprietary share tables — to encourage direct engagement with the full research package. For procurement managers, R&D leads, and corporate development teams, those datasets are the working files for scenario planning, supplier negotiations, and transaction due diligence.
In short: the market is growing at a steady mid-single-digit rate, driven more by regulatory and sustainability mandates, product differentiation, and changing material economics than by sheer volume growth alone. Companies that align product architecture, sourcing strategies, and go‑to‑market models to these forces in 2026 will capture the outsized opportunities embedded in the broader market expansion.
To access the comprehensive data tables, scenario models, and supplier benchmarking that support these insights, please consult the full PW Consulting report available on our website. The detailed segment-level intelligence and downloadable decision-support tools are provided exclusively in the full report.
For detailed analysis of this topic, please visit the official page: Worldwide Twist Dispensing Closure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com