

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide 5G‑Advanced Chip Market Set to Surge from USD 3,850 Million in 2025 to USD 41,506.3 Million by 2032 at a 40.45% CAGR

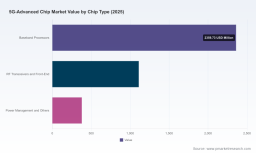
Worldwide 5G-Advanced Chip Market: Strategic Preview for 2026 Decision-Makers
PW Consulting’s newest market study, Worldwide 5G-Advanced Chip Market (base year 2025; forecast 2026–2032), frames a defining moment for semiconductor strategy and telco ecosystem planning. With the market accelerating from early commercialization to a broad-scale deployment phase, our analysis equips executives to translate technical standards, supplier moves, and manufacturing capacity into defensible commercial choices for 2026 and beyond.
Worldwide 5G-Advanced Chip Market
Executive summary — why this matters now
5G-Advanced is shifting from standards and demonstrations to revenue-generating architectures. Our market model shows the total 5G‑Advanced chip market jumping materially by 2026 and compounding at a very high rate across the forecast window (CAGR ~40.45% for 2026–2032). This creates a finite strategic window in 2026 when choices about vendor partnerships, node investments, and product roadmaps will determine market share and margin trajectories through 2030 and into the era that bridges toward 6G.
Worldwide 5G-Advanced Chip Market
For leaders in device OEMs, infrastructure suppliers, auto telematics, industrial automation, and chipset IP licensing, the immediate questions are operational: which silicon partners to prioritize for sampling and qualification; where to allocate R&D and packaging budgets; how to reconfigure manufacturing and procurement to capture the early-adopter premium while avoiding overcommitment to single-node dependencies. Our report does not merely map opportunity — it prescribes decision paths aligned to business models and time horizons.
Worldwide 5G-Advanced Chip Market
Market trajectory: the macro picture
After a rapid commercialization ramp in 2023–2025, the total market value that underpins 5G‑Advanced chipsets shows a pronounced expansion in 2026 as Release 18 implementations broaden. The model projects a dramatic expansion across the forecast period, underscoring both scale potential and the imperative for timely execution. Equally important, industry concentration is pronounced: the top three suppliers account for a dominant share of the market (CR3 ~72.4%), and the top five approach near-total dominance (CR5 ~88.2%).
These structural facts — high growth and high concentration — create a bifurcated strategic environment: suppliers who secure early design wins and preferred foundry/packaging arrangements can capture outsized margins; late entrants face either niche specialization or acquisition as the primary route to scale.
Dynamics shaping 2026 decisions
- Standards and device readiness: 3GPP Release 18 crystallizes the technical baseline for 5G‑Advanced, introducing advanced MIMO, energy-efficient network constructs, evolved duplexing, and expanded positioning capabilities. Device and infrastructure timelines are now tightly coupled to Release 18 maturations.
- Manufacturing and packaging: Advanced node and advanced packaging capacity (including investments enabled by national semiconductor initiatives) are central to delivering power‑efficient, high‑performance modems and RF front-ends at scale. Decisions about node roadmaps and packaging partnerships will determine tactical time-to-market.
- RF and material shifts: Wide adoption of GaN in RF subsystems for mmWave amplification is remapping supply chains — from material sourcing through thermal/packaging engineering — and creating new supplier gating functions for systems integrators.
- Device ecosystems and platform plays: Platforms that combine modem, RF, AI acceleration, and power management are emerging as differentiators. The interplay between platform breadth and ecosystem support (software, modem stacks, and certification) will be a make-or-break factor in 2026 procurements.
Competitive landscape — who to watch
Our competitive review synthesizes supplier positioning, recent product milestones, and strategic signals that matter to procurement and product teams in 2026.
- Qualcomm Technologies, Inc. — Continues to lead on integrated modem‑RF platforms and early Release 18/19 readiness. Recent launches and sampling programs indicate Qualcomm’s strategy of marrying feature parity with OEM scale, making it a default partner for many smartphone and FWA players.
- MediaTek Inc. — Aggressively pursuing a platform and CPE-focused strategy with variants optimized for FWA and telematics. MediaTek’s emphasis on multi‑antenna RF gains and embedded AI shows a clear play to capture non-smartphone segments where differentiation is rapidly valued.
- Samsung Electronics Co., Ltd. — Advances in process and packaging allow Samsung to play both as an internal integrator (for its mobile business) and as a competitive foundry/customer for external modem projects. Expect Samsung to leverage transistor and memory innovations to create performance/per-watt advantages.
- Broadcom Inc. — Focused on infrastructure-grade SoCs for massive MIMO and wideband radio systems, with strategic FPGA and interoperability collaborations to enable scalable beamforming and AI-assisted signal processing.
- GCT Semiconductor — An example of rapid commercialization from a fabless designer to commercial shipments, signaling that smaller suppliers can capture specific verticals (e.g., air-to-ground) through focused qualification pipelines.
- Sequans Communications — Targeting the IoT and RedCap evolution in 5G‑Advanced, with low-power connectivity platforms that appeal to industrial and metered applications where cost and energy efficiency dominate.
- Huawei Technologies Co., Ltd. — Continues to execute in infrastructure and vertical implementations (robotics, healthcare), leveraging systems integration to offset component-level competition.
- Intel Corporation — Emphasizing infrastructure and edge compute integrations where network processors and modem platforms intersect with edge workloads, offering differentiated value to cloud and carrier partners.
Recent vendor moves in early 2026 — commercial sampling of Release 19‑capable modems, first commercial shipments from niche fabless players, and cross-company interoperability tests — are the operational signals procurement teams must track. These events will shape qualification schedules and OEM design freezes through H2 2026.
Strategic implications by value chain node
- Chip design and IP: Prioritize modular designs and licenseable IP blocks to shorten pathway to revenue when standards evolve. Licensing strategies and patent exposure must be reconciled with partner roadmaps.
- Foundry and packaging: Secure multi-node options and advanced packaging slots early. Contingency planning across foundries — and alignment with national subsidy programs — will reduce supply risk and cost volatility.
- RF subsystem and materials: Integrate RF material strategies (e.g., GaN) into system roadmaps; thermal and power design trade-offs will drive differentiation in mmWave devices and infrastructure radios.
- Software and platform certification: Software stacks, modem validation, and certification timelines are equally critical; allocate resources to interoperability testing and operator acceptance early in 2026.
What the PW Consulting report delivers — practical content
Our report is designed for executives who need to act in 2026. It blends forecast modeling with operational playbooks and includes:
- Scenario-driven market models and sensitivity analysis to map risk/reward across different adoption timelines;
- Supplier benchmarking that evaluates technical readiness, commercial terms, ecosystem support, and integration risk;
- Manufacturing and packaging heat maps identifying critical node bottlenecks and strategic contract-placement recommendations;
- Go-to-market playbooks for OEMs, infrastructure vendors, Tier‑1 integrators, and component suppliers aligned to three time-horizon archetypes (fast-follow, platform leader, and niche specialist);
- Due‑diligence and M&A frameworks tailored to de‑risk acquisitions in a high‑concentration market;
- Operational checklists for cross-functional teams (product, procurement, legal, and regulatory) to accelerate qualification while preserving negotiating leverage.
Importantly, the report omits line‑by‑line segment share tables in this public preview — a deliberate choice to ensure readers and clients engage with the full dataset and supplier breakdowns in the paid report. Those granular insights are essential for procurement negotiations and are provided under our standard client licensing terms.
Actionable recommendations for 2026
- Immediately initiate multi-vendor qualification lanes: Run parallel qualification with at least two platform suppliers for high-volume products to preserve time-to-market and bargaining leverage.
- Lock strategic foundry/packaging options: Secure advanced packaging slots and node allocations conditional on fall-back clauses tied to qualification milestones.
- Reassess IP and licensing posture: Build cross-license contingency plans and incorporate IP warranty/indemnity terms early in supplier contracts.
- Prioritize interoperability testing: Begin operator and ecosystem interoperability tests before design freeze to avoid schedule slips driven by Release 18/19 nuances.
- Align product roadmaps with regulatory and material shifts: Factor GaN adoption and national semiconductor initiatives into procurement and supplier development plans.
How PW Consulting’s analysis supports board-level decisions
Boards and C-suites need concise scenarios that translate technical standards and supplier events into balance-sheet and market-share outcomes. Our study provides translated impact metrics — revenue sensitivity, margin scenarios, and strategic option payoffs — that feed directly into capital allocation, M&A screening, and partnership commitments. The combination of a rigorous market model (showing the pronounced expansion beginning 2026 and a high multi-year CAGR) and supplier-level intelligence yields an execution roadmap you can act on this fiscal year.
Next steps — where to get the full intelligence
This public briefing highlights the strategic contours of the 5G‑Advanced chip market while preserving the full segmentation table and supplier-specific scorecards for our subscription clients and report purchasers. To access the detailed breakdowns, supplier scorecards, and the complete downloadable dataset that supports procurement and investment decisions, please visit the PW Consulting report page or contact our advisory team for a tailored briefing.
In an industry defined by both high growth and concentrated power, 2026 will be the year companies decide whether to lead, follow, or niche. PW Consulting’s Worldwide 5G‑Advanced Chip Market report is designed to make that choice a defensible, data‑driven decision.
For detailed analysis of this topic, please visit the official page: Worldwide 5G-Advanced Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com