

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Differential Electrochemical Mass Spectrometry Market to Grow at a 9.25% CAGR Through 2026–2032
By pmarketresearch, 2026-07-15
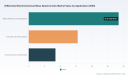
Worldwide Differential Electrochemical Mass Spectrometry (DEMS) Market — PW Consulting Strategic Release
Executive snapshot
Our new Pw Consulting Worldwide Differential Electrochemical Mass Spectrometry Market study crystallizes why DEMS instruments are moving from niche lab curiosities to strategic tools for materials and energy R&D organizations. Using 2025 as the base year and a forecast horizon through 2032, the market is projected to expand at a compound annual growth rate (CAGR) of 9.25%. This growth trajectory reflects accelerating investment in battery and electrocatalysis research, stronger demand for mechanistic gas/volatile analysis in electrochemical systems, and widening adoption of integrated analytical workflows across industry and academia.
Worldwide Differential Electrochemical Mass Spectrometry Market
Why this matters to enterprise decision-makers in 2026
-
Strategic timing: 2026 is a pivot year for many industrial research organizations recalibrating capital and service budgets post-pandemic and amid tighter technology roadmaps for batteries, fuel cells, and CO2 electroconversions. DEMS capability is increasingly treated as an enabler for competitive differentiation rather than a discretionary spend.
Worldwide Differential Electrochemical Mass Spectrometry Market -
Risk and reward balance: DEMS delivers high-value, direct measurements that reduce development cycle risk for electrochemical materials. However, hardware fragility (notably membrane interfaces), consumables cadence, and integration complexity create operational risk that must be managed strategically.
Worldwide Differential Electrochemical Mass Spectrometry Market -
Investment signals: The market’s high-single-digit CAGR implies predictable topline expansion for established vendors and an attractive entry window for specialized instrument and consumable players. Investors and corporate R&D procurement teams should consider not only capital acquisition costs but total cost of ownership, service footprints, and data-ecosystem lock-in when evaluating options.
What the report delivers — practical, decision-ready intelligence
PW Consulting’s report goes beyond headline growth to deliver operational, commercial, and technical intelligence that matters at the procurement, product and corporate strategy levels. Key actionable deliverables include:
-
Instrument selection framework — a reproducible checklist that ties experimental goals (e.g., gas evolution quantification vs. volatile product speciation) to DEMS architecture choices and accessory requirements.
-
Total cost of ownership models that quantify consumables, membrane replacement cycles, service intervals, and integration effort with potentiostats and LIMS.
-
Supply chain maps for critical subcomponents (membranes, vacuum interfaces, microfluidics), and vendor-mapping to identify single-source risk and diversification pathways.
-
Operational playbooks — SOP templates for membrane handling, contamination mitigation, and routine calibration that reduce downtime and preserve measurement integrity.
-
Competitive profiling and benchmarking of leading vendors, including product roadmaps, go-to-market strategies, and recent product developments.
-
Scenario-based demand forecasts that stress-test assumptions on battery scale-up, hydrogen and fuel cell programs, and academic investment cycles.
Competitive landscape — who matters and why
The DEMS vendor community is compact but technically deep. Market concentration indicates that a relatively small number of suppliers command the majority of installed capability, creating both stability and barriers for new entrants. Our fieldwork and supplier audits highlight four vendors that shape the market dynamic in 2026:
-
Hiden Analytical (Warrington, UK) — Hiden’s HPR-40 platform and the modular ECL Series electrochemical cells position the company as a leader in synchronized electrochemical-mass data capture. Recent 2026 product showcases underscore a focus on software and hardware synchronization (potentiostat integration), which lowers the barrier for laboratories seeking turnkey time-correlated measurements. For enterprise buyers, Hiden represents a mature option with strong application notes and partner integrations.
-
Spectro Inlets (Denmark) — Spectro’s EC-MS systems emphasize quantifiable, real-time battery gas evolution and SEI studies. Their technical materials also call out the membrane interface as a practical bottleneck — an area where Spectro positions itself with engineering and maintenance guidance. Organizations prioritizing battery failure-mode analysis will find Spectro’s instruments tailored to such workflows.
-
Liquid Loop (Europe) — Liquid Loop’s modular microfluidic and flow systems cater to labs that require flexible experimental geometries and rapid reconfiguration. Their emphasis on compact, modular hardware makes them an attractive partner for R&D groups experimenting across electrocatalysis and microfluidic electrochemistry.
-
Shanghai Linglu Instruments (Shanghai, China) — Linglu brings competitive local-market manufacturing and a product suite oriented to battery DEMS and classic electrochemical cells. For multinational purchasers, Linglu expands sourcing options and price-performance tradeoffs, especially where deployment volumes and localized service agreements matter.
For buyers and investors, vendor selection should weigh not only instrument performance but service network maturity, consumables supply, software openness, and demonstrated integration with third-party potentiostats and data systems.
Technology and operational dynamics to watch
-
Membrane interface remains the prime hardware constraint. The pervaporation/nanoporous membrane is central to DEMS functionality but is also the subsystem most exposed to failure and contamination in volatile electrolytes. Companies that reduce membrane downtime through design, consumables strategy, or predictive service offerings will capture disproportionate operational share.
-
Standards and software synchronization are commercial levers. While there are no DEMS-specific ISO standards, routine integration with potentiostats (e.g., Metrohm Autolab, BioLogic) requires robust cabling, timing protocols, and software APIs. Vendors that commit to open, documented synchronization standards reduce buyer friction and accelerate adoption.
-
Research-use only positioning constrains downstream adoption. DEMS instruments are lab-centered tools and not intended for clinical or large-scale production deployment. This boundary shapes addressable markets and suggests that growth will be driven primarily by R&D funding cycles and the pace of electrochemical innovation.
Strategic recommendations for 2026
Based on quantitative forecasts and qualitative intelligence, Pw Consulting recommends distinct actions by stakeholder type to capture value from the DEMS market expansion:
-
For instrument buyers (corporate R&D and national labs): Treat DEMS procurement as a systems investment. Prioritize suppliers that include service SLAs, consumables pipelines, and documented integration with existing potentiostats. Conduct a 12-month consumables and membrane stress test before committing to multi-unit purchases.
-
For DEMS vendors and OEMs: Differentiate through consumables and service economics. Develop predictable membrane replacement programs, remote diagnostics, and API-first software that facilitates integration into lab automation. Consider modular product families to address both benchtop and in-situ requirements without heavy engineering overhead per customer.
-
For investors and M&A teams: Look for targets with strong consumables margins, intellectual property around membrane interfaces, or software that provides data lock-in. Given the current market concentration, bolt-on acquisitions that extend service footprints or add complementary microfluidic capabilities can accelerate go-to-market scale.
-
For research consortia and funders: Pool procurement or establish shared instrumentation facilities to reduce unit cost and accelerate cross-project learning. Invest in standard operating procedures and inter-lab round-robin studies to improve data comparability and accelerate technology transfer.
Next steps and how to use this intelligence in 2026 planning
Operational leaders should use the report to build a 12–36 month action plan linking instrument acquisition to specific project milestones (e.g., cell chemistry optimization, accelerated lifetime testing). Commercial leaders should integrate the report’s vendor benchmarks and concentration metrics into supply-risk assessments and sourcing roadmaps. Investors should overlay the market growth assumptions and scenario analyses against capital availability and exit timelines.
About the dataset and where to get the full intelligence
This release highlights the strategic implications and programmatic recommendations drawn from Pw Consulting’s full study. The comprehensive report includes granular segmentation, regional demand models, company financial and product benchmarks, and downloadable TCO and procurement templates designed for immediate operational use. To access the complete dataset, detailed segment breakdowns, and vendor-level scorecards, please visit our report page or contact Pw Consulting’s industry practice.
For detailed analysis of this topic, please visit the official page: Worldwide Differential Electrochemical Mass Spectrometry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Laminating Lithium‑ion Capacitor Market Set to Surge at a 18.54% CAGR Through 2032
By pmarketresearch, 2026-07-15
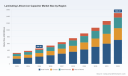
Worldwide Laminating Lithium‑ion Capacitor Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s newest market study on the Worldwide Laminating Lithium‑ion Capacitor (LIC) market provides a forward‑looking, decision‑grade intelligence package designed for senior executives, product and supply‑chain leaders, and corporate development teams planning for 2026 and beyond. Anchored on a 2025 base year and extending through 2032, the analysis quantifies an accelerated growth trajectory (CAGR 18.54%) and translates that growth into the commercial choices companies must make today to capture position and margin in a rapidly maturing technology ecosystem.
Worldwide Laminating Lithium-ion Capacitor Market
Key market trajectory — what the numbers imply for strategy
-
The laminated LIC market has moved from early commercialization into scale‑up. Historical sizing shows consistent expansion through 2023–2025, and our forecasts anticipate that trajectory accelerating from 2026 onwards. This industry‑level momentum — reflected in a mid‑teens compound annual growth rate (18.54%) through 2032 — creates both timing pressure and windows of opportunity for first movers, fast followers and systems integrators.
Worldwide Laminating Lithium-ion Capacitor Market -
By anchoring strategy to our 2025 base year, organizations can translate growth expectations into production, procurement and route‑to‑market investments that avoid common scale‑up missteps (e.g., over‑capitalization against immature demand, or underinvestment when adoption inflects).
Worldwide Laminating Lithium-ion Capacitor Market -
The market structure is moderately concentrated: the top three vendors account for a majority share, and the top five approach three‑quarters of the market by revenue. This concentration amplifies the influence of incumbent suppliers while still leaving room for new entrants with differentiated technology or manufacturing economics.
Why 2026 is a pivotal planning horizon
-
Near‑term capacity and certification events in 2025–2026 will shape which suppliers can meaningfully address industrial, transportation and grid applications at scale. Firms that align product roadmaps and sourcing strategies to that supply picture will preserve optionality and pricing leverage.
-
Technology convergence — notably in laminated pouch construction and dry‑electrode processes — is lowering some barriers to higher energy‑density and manufacturability. IP transfers and licensing activity are accelerating the diffusion of manufacturing know‑how from battery processes into LIC production lines.
-
Supply‑chain volatility for activated carbon and lithium, compounded by tariff dynamics and geopolitical shifts, will make strategic sourcing and nearshore manufacturing more than a cost exercise: it will be a resilience play that materially affects time‑to‑market and total landed cost.
What practitioners will find inside the report
-
Transparent market sizing and forecasting methodology (historical 2020–2025 base; forecast 2026–2032), including scenario and sensitivity runs that translate macro drivers into actionable revenue and capacity planning benchmarks.
-
Technology and manufacturability roadmap: laminated cell processing options, dry‑electrode and pre‑doping pathways, materials tradeoffs and yield drivers. This section is geared to R&D and operations teams evaluating CAPEX and process selection.
-
Commercial segmentation frameworks and go‑to‑market playbooks for OEMs, system integrators and component suppliers — constructed to prioritize channels, partner archetypes and value capture without exposing proprietary subsegment detail in this preview.
-
Supplier risk and opportunity matrix: scoring for production readiness, geographic risk, certification status and capable mass‑production technologies, plus recommended mitigation tactics for procurement and strategic sourcing leaders.
-
Competitive intelligence dossiers: in‑depth profiles, strategic positioning and likely near‑term moves for the cohort of LIC suppliers and adjacent energy‑storage players, supported by primary interviews and plant‑level verification.
-
M&A and partnership playbook: deal archetypes and valuation considerations relevant to 2026 buyers, including earn‑out structures tied to performance milestones common in capital‑intensive battery‑adjacent deals.
Competitive landscape — players to watch and why they matter
-
LICAP Technologies, Inc. — A U.S.‑based innovator advancing dry electrode approaches and domestic scaling for laminated‑compatible processes. Recent facility expansion and manufacturing collaborations indicate a push to convert lab‑scale advantages into volume supply for automotive and grid applications. For strategic buyers and Tier‑1s, LICAP is both a likely supplier and an M&A candidate depending on execution and capital intensity.
-
Musashi Energy Solutions (JM Energy) — Japan‑based with established mass‑production capability and system certifications for energy storage. Their progress on regulatory listings and modular systems makes them a credible partner for integrators prioritizing validated safety and lifecycle performance.
-
Regional fabricators (several Asian and European engineering firms) — These suppliers bring pouch/laminate manufacturing know‑how and thin‑form‑factor cell formats that appeal to constrained package spaces and high‑power burst applications. Their competitive edge is in optimized form factors and local supply‑chain synergies.
-
Specialty and hybrid suppliers — Firms combining EDLC and Li‑ion characteristics can outcompete purely capacitive providers on energy density while competing with batteries on power density and cycle life. Expect these vendors to target niches such as industrial backup, regenerative braking and power‑smoothing in renewable systems.
-
System and module integrators — Companies that pair cells with power electronics and thermal management will capture a disproportionate share of end‑customer value. The report maps which integrator capabilities matter most depending on target applications.
Supply‑chain dynamics and raw‑material constraints
-
Activated carbon supply and price volatility are key short‑to‑mid‑term constraints. Industry analyses indicate that particular biomass sources dominate feedstock supply and that current pricing sits noticeably above the cost threshold that would make certain supercapacitor electrode formulations broadly economical. This cost delta is a structural risk for players that cannot achieve material or process economies.
-
Licensing and process standardization — e.g., lithium pre‑doping techniques made available under third‑party licenses — are lowering barriers to entry by enabling producers to use conventional lithium‑ion battery equipment. That trend shortens the time and capital required to field competent laminated LIC lines, changing the competitive calculus for both incumbent battery makers and start‑ups.
-
Geopolitical pressures and tariff shifts are driving nearshoring and supplier diversification for critical inputs. Organizations that align procurement and capacity plans to anticipated commodity and trade scenarios will avoid the costly scramble many saw in prior energy‑materials cycles.
Strategic imperatives for 2026
-
Prioritize supply‑chain optionality: hedge raw‑material exposure, qualify secondary suppliers and design for material substitution where validated by lifecycle testing.
-
Invest selectively in manufacturing partnerships and licensing that accelerate time‑to‑volume for laminated formats without overcommitting capital to proprietary processes before unit economics are proven.
-
Target system‑level differentiation: marry cell performance with power electronics, thermal management and software to win in applications that prize integration (e.g., renewable smoothing, transportation ancillary systems, industrial automation).
-
Map regulatory and certification pathways early: UL and system‑level approvals materially affect adoption timelines for many end markets; certification‑focused R&D is a de‑risking investment.
-
Prepare M&A and JV playbooks: with market concentration still evolving, disciplined bolt‑on acquisitions and joint manufacturing ventures can be effective routes to scale and capability capture.
How PW Consulting helps executives translate insight into action
-
We convert the report’s market sizing, supplier scoring and scenario models into an executable 90‑day plan tailored to your role — procurement, product, operations or corporate development — aligning KPIs and investment triggers to real commercial milestones.
-
Our hands‑on vendor due diligence service verifies factory readiness, process yields and certification roadmaps so you can prioritize partners with the lowest execution risk.
-
For boards and investment committees, we prepare transaction‑oriented analyses that estimate required capex, payback timing and integration risk under multiple adoption scenarios.
PW Consulting’s Worldwide Laminating Lithium‑ion Capacitor Market report is structured to be a practical tool for 2026 planning: it balances robust quantitative forecasting with operational levers, supplier intelligence and executable strategic options. To review the complete segmentation data, granular scenario outputs and supplier scorecards that underpin these findings, please visit our report page to access the full dataset and supporting appendices.
For detailed analysis of this topic, please visit the official page: Worldwide Laminating Lithium-ion Capacitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Cab Mounts Market Set to Grow at a 5.0% CAGR, Signaling Strategic Opportunities for OEMs
By pmarketresearch, 2026-07-15
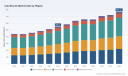
Worldwide Cab Mounts Market — Strategic Outlook and Decision Playbook for 2026
As PW Consulting’s lead industry analyst, I present a forward-looking synthesis of our newest market research on the Worldwide Cab Mounts market. This briefing highlights the strategic value of the full 2026–2032 forecast study for corporate leaders, product teams, supply-chain heads and M&A strategists preparing decisions in 2026. The analysis below signals where value creation will accrue, what competitive moves will matter, and how to prioritize investments — while preserving the granular datasets and proprietary segmentation that make the full report essential for execution.
Worldwide Cab Mounts Market
Executive snapshot: resilient growth, clear catalysts
The cab mounts market has displayed steady recovery and growth through the recent cycle. After navigating pandemic disruptions and supply-chain pressures, the industry reached an estimated market size of USD 545.2 Million in 2025 (base year), and our modelling points to an expected USD 584.97 Million in 2026. Under the scenarios embedded in the report, the market grows at a compound annual growth rate (CAGR) of 5.0% over the 2026–2032 forecast horizon, with a projected market value near USD 767.14 Million by 2032.
Worldwide Cab Mounts Market
This steady mid-single-digit growth is driven by converging forces: rising adoption of advanced vibration-damping technologies in off‑highway equipment, heightened regulatory and occupational-safety expectations, and OEMs’ renewed focus on operator comfort as a differentiator in equipment procurement.
Worldwide Cab Mounts Market
Why this matters for 2026 decision-makers
- Investment prioritization: A clear, multi-year growth runway enables manufacturers and suppliers to justify targeted investments in R&D (viscous and fluid-damped mounts, hybrid materials), capacity expansions, and regional service footprints — but only where market dynamics and unit economics align.
- Product strategy: Evolving operator-comfort expectations and whole‑body-vibration mandates are shifting product requirements from basic rubber-to-metal solutions to more complex hybrid systems. Product roadmaps that integrate material science, NVH (noise-vibration-harshness) modelling, and modular designs will capture premium segments.
- Supply-chain resilience: Raw material composition — primarily elastomers bonded to metal substrates — exposes manufacturers to volatility in elastomer feedstocks and metal prices. Strategic procurement, dual-sourcing, and long-term supplier agreements are now hygiene factors for margin protection.
- M&A and partnership screening: Given a moderately concentrated supplier base with differentiated capabilities, 2026 is a pivotal year to pursue tuck-ins that add material expertise, fluid-damping technologies, or regional OEM relationships. Our full report provides candidate scoring against technical fit, commercial synergies and integration risk.
Market dynamics driving the 2026 strategic agenda
- Technology shift toward hybrid damping: Viscous and fluid‑elastic solutions—combining elastomers and internal damping fluids—are gaining traction where NVH performance and lifecycle durability are mission critical. Adoption patterns are especially pronounced in off‑highway rigs where operator hours are long and exposure to whole-body vibration is regulated or tightly monitored.
- Operator safety and regulation: Cab mounts play a material role in compliance with ROPS and related safety standards. Buyers increasingly evaluate mounts not just on cost and life, but on documented compliance and test performance under standardized rollover and vibration protocols.
- Raw-material & manufacturing considerations: The industry’s core components remain rubber-to-metal bonded assemblies using natural or synthetic elastomers mated to steel or similar substrates. This underpins both product performance and cost structure: material selections and bonding processes determine fatigue life, environmental resistance and manufacturability.
- Commercial channel evolution: OEMs continue to consolidate procurement, but aftermarket and retrofit channels remain vital, especially in ag and construction equipment where fleet operators prioritize lifecycle comfort and uptime. Serviceability and rapid replacement logistics are becoming differentiators.
Competitive landscape — who matters and why
The market is characterized by several established engineering-first suppliers and specialist manufacturers offering differentiated technologies. The competitive positions we profile in the report demonstrate a mix of deep engineering capability, broad product portfolios, and channel strength that will determine winners in 2026 and beyond:
- Trelleborg AB (Trelleborg, Sweden): A leader in high‑performance anti‑vibration solutions with a comprehensive industrial catalogue. Its portfolio and recent catalogue updates underscore a product-led strategy aimed at off‑highway vehicle segments.
- Link Manufacturing (Sioux Center, Iowa, USA): Globally recognized for cab suspensions and complete air-suspension systems, Link’s focus on air-based systems for heavy trucks and specialty vehicles positions it strongly where ride quality and retrofitability are prioritized.
- GMT Rubber-Metal-Technic Ltd (UK): Known for cone mounts and progressive-stiffness designs, GMT’s engineered rubber-metal systems address high-shock load applications typical in heavy machinery.
- AMC-MECANOCAUCHO (Spain): Specialist in rubber-bonded metal mounts with tailored hardnesses and load ratings; their ROPS-focused testing capability is a competitive advantage for safety-first OEMs.
- Parker LORD (formerly LORD Corporation, USA): A technology pioneer in viscous and Fluidlastic mounts, combining elastomeric and fluid damping — solution sets that capture premium NVH performance requirements.
- Hutchinson SA (France) & SumiRiko (Japan): Both suppliers bring global manufacturing scale and product breadth, serving both on‑highway and off‑highway equipment segments with standard and custom isolation solutions.
Notably, competitive advantage is created through product breadth, engineering services (testing, ROPS support), and aftermarket distribution. The industry is neither fragmented nor monopolized — leading firms hold meaningful scale but non‑dominant market shares, leaving room for targeted entrants and consolidation plays. The full report contains a quantified competitive map and a ranked capability matrix to help you shortlist partners and acquisition targets.
Practical actions for 2026
- Prioritize product investment by measurable ROI: Use NVH performance thresholds and regulatory testing outcomes to create tiered product roadmaps — basic rubber mounts for cost-sensitive fleets, and hybrid viscous designs for premium and regulated applications.
- Hedge raw-material exposure: Lock in elastomer supply contracts, qualify second-source metal suppliers, and investigate alternative compound formulations that offer comparable performance with improved cost or sustainability characteristics.
- Optimize aftermarket and services: Deploy predictive-fitment catalogs, accelerated logistics hubs near major equipment clusters, and value-added services such as installation training and warranty analytics to increase lifetime revenue per unit.
- Screen M&A by capability gaps: Target targets that close gaps in fluid-damping tech, high-load elastomer formulations, or that add durable relationships with OEMs in growth geographies. Use the report’s M&A heatmaps and synergy models to accelerate diligence.
- Embed testing and certification as commercial tools: Make ROPS validation and documented NVH improvements a part of the sales narrative; buyers will pay a premium for validated performance and reduced operator fatigue liability.
What the full PW Consulting report delivers
The public summary above is a strategic preview. The complete Worldwide Cab Mounts Market report (base year 2025, forecast 2026–2032) equips decision‑makers with:
- Historical market tracking (2020–2025) and scenario-based forecasts through 2032, expressed in USD Million and incorporating granular sensitivity testing.
- Proprietary demand-models calibrated to equipment OEM build rates, fleet replacement cycles and regulatory adoption curves.
- High-resolution competitive benchmarking: product portfolios, technological differentiation, channel reach and a ranked target list for M&A or partnership consideration.
- Supply-chain risk maps focusing on elastomer and metal feedstocks, with mitigation playbooks and cost-impact scenarios.
- Actionable go‑to‑market templates for OEM, aftermarket and retrofit channels — including pricing strategies and service-pack options designed to accelerate uptake.
- Primary-sourced interviews and product-spec validations from leading suppliers and OEM engineering teams to substantiate technical assumptions.
Recent industry signals to watch in 2026
- Catalog and portfolio refreshes: Premium suppliers have recently updated product catalogues and engineering guides — a sign they are consolidating technical leadership and preparing commercial push strategies that will influence OEM procurement cycles.
- Technology diffusion: Expect increasing cross-adoption of viscous and hybrid-damping approaches in niches previously dominated by rubber-only solutions; performance demands and operator-safety metrics are the accelerants.
- Procurement sophistication: Buyers are requesting validated lifecycle cost analyses, shifting supplier selection from price-first to value-first evaluations.
How to use this report in 90 days
- Day 0–30: Align leadership on prioritized use cases (OEM, aftermarket, retrofits) and run the report’s profitability stress-tests on current product lines.
- Day 30–60: Execute supplier audits for elastomer and metal exposures, and begin technical trials for any new compound or fluid-damping components identified as high-value.
- Day 60–90: Complete a shortlist of M&A or partnership targets using the report’s capability matrix and initiate preliminary outreach supported by our commercial-case templates.
Concluding observation
The cab mounts market presents a compelling, mid-single-digit growth opportunity underpinned by technological substitution, regulatory reinforcement and buyer willingness to pay for demonstrable comfort and safety benefits. For 2026, leaders who combine material science investment, robust supply-chain hedging and a service-led aftermarket strategy will be best positioned to convert projected market growth into sustainable margin expansion.
PW Consulting’s full study contains the detailed segmentation, regional and application-level analytics, and proprietary company benchmarking necessary to operationalize the strategies outlined here. To access the granular datasets, candidate acquisition targets, and the complete implementation playbook, please consult the full Worldwide Cab Mounts Market report on the PW Consulting website.
For detailed analysis of this topic, please visit the official page: Worldwide Cab Mounts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Digital Generator Circuit Breaker Market to Rise from USD 345.5 Million in 2025 to USD 547.6 Million by 2032 at a 6.81% CAGR — SF6‑Insulated GCBs and Asia‑Pacific Lead as Top 3 Firms Control ~68.5%
By pmarketresearch, 2026-07-15
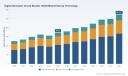
Worldwide Digital Generator Circuit Breaker (GCB) Market: Strategic Imperatives for 2026 Decision‑Makers
As global power systems confront accelerating renewable integration, stricter environmental standards, and heightened expectations for plant availability, Generator Circuit Breakers (GCBs) have moved from a commoditized protection device to a strategic asset class. PW Consulting’s latest market study — the Worldwide Digital GCB Market report — synthesizes a seven‑year historical series (2020–2025) and delivers an evidence‑based forecast for 2026–2032, demonstrating both the scale and velocity of change facing asset owners, OEMs, and investors. The report shows the market crossed roughly USD 345.5 million in 2025 and is modeled to expand at a 6.81% CAGR through the forecast window, underscoring material opportunities and risks that will shape procurement and O&M choices in 2026.
Worldwide Digital Generator Circuit Breaker (GCB) Market
Why this report matters for your 2026 agenda
- Decision timing: The 2026 planning cycle is the inflection point for many utilities and plant operators who must choose between life‑extension and retrofit paths. Our analysis quantifies market momentum and outlines the tipping points where digital retrofits unlock disproportionate reductions in forced outages and maintenance spend.
- Regulatory and compliance alignment: GCBs operate under distinct high‑duty requirements (per IEEE C37.013) and installation standards (IEC/IEEE 62271‑37‑013:2021). The report maps these standards against technology choices and procurement language to reduce bid risk and future retrofit exposure.
- Operational resilience: Digital GCB architectures — combining on‑device sensors, edge aggregation, and cloud analytics — are no longer experimental. Our findings show how predictive health data changes the maintenance cadence, availability economics, and spare‑parts strategies for large plant fleets.
- Investor signals: Market concentration metrics (CR3 at 68.45% and CR5 at 82.12%) indicate a supplier landscape where a small set of incumbent players will drive technology roadmaps. Investors should weigh competitive moat, services revenue potential, and retrofit addressable markets when evaluating OEM exposure.
What the report delivers — practical, executable modules
This study is built for action. Rather than high‑level commentary, the report provides a modular toolkit that procurement, engineering, and strategy teams can apply immediately:
Worldwide Digital Generator Circuit Breaker (GCB) Market
- Robust market sizing & forecast methodology: Transparent modeling that reconciles historical deliveries (2020–2025) with component lead times, OEM production capacities, and demand drivers to project 2026–2032 trajectories.
- Technology deep dives: Comparative analysis across SF6‑insulated, vacuum, and air‑insulated GCB technologies — covering failure modes, maintenance intervals, lifecycle OPEX, and environmental implications — enabling techno‑economic tradeoff analysis without vendor bias.
- End‑user use cases and failure economics: Quantified case studies for thermal, hydro, nuclear, and integrated gas/renewable assets that translate breaker performance into outage minutes, replacement costs, and availability impacts.
- Regulatory mapping and compliance checklists: Ready‑to‑use procurement clauses and test acceptance criteria aligned to IEC and IEEE norms to reduce non‑conformance risk at bid evaluation.
- Supply‑chain risk and raw‑material outlook: Assessment of critical components (e.g., vacuum interrupters versus SF6 gas handling) and contingency strategies to mitigate long‑lead items and price volatility.
- Competitive benchmarking and vendor scorecards: Multi‑dimensional profiles of incumbent and emerging suppliers across technology, manufacturing footprint, service coverage, digital capability, and aftermarket intensity — with an objective scoring framework for RFP short‑listing.
- Digital adoption playbook: Practical architectures for on‑premise and cloud integration, edge data aggregation, cybersecurity considerations, and sample KPIs for Asset Health Management and predictive maintenance pilots.
- Commercial templates and CapEx/Opex models: TCO calculators, contract structures, and service‑level templates that let buyers simulate buy vs. service vs. retrofit scenarios over typical asset lifecycles.
Competitive landscape: incumbents, strategies, and recent moves
The market is characterized by a handful of global OEMs with deep installed bases and differentiated digital offerings. The report’s company intelligence synthesizes public disclosures, product literature, and field evidence to highlight competitive positioning without revealing confidential supplier performance metrics.
Worldwide Digital Generator Circuit Breaker (GCB) Market
- Hitachi Energy (Zurich, Switzerland) — A long‑standing leader in GCB technology, with a history of global deliveries and integrated digital offerings. Notable is their Digital GCB solution paired with the GMS600 platform for health aggregation, predictive maintenance workflows, and flexible deployment across on‑premise and cloud environments. Recent customer engagement initiatives (e.g., their GCB Customer Days in 2025) underscore a services‑led agenda focused on lifecycle management and sustainability themes.
- GE Vernova (United States) — A major supplier for a broad spectrum of plant sizes and typologies. Their product set emphasizes digital cooling optimization and comprehensive condition monitoring (CBWatch3), backed by updated services literature that highlights retrofit and maintenance pathways. GE’s strategic posture is to convert installed base into recurring aftermarket revenue via digital services and targeted retrofits.
- Siemens (Germany) — A technology leader advocating SF6‑free vacuum solutions that reduce long‑term environmental liability and OPEX through maintenance reduction. Siemens’ portfolio positions the vacuum route as a compliance‑friendly and low‑maintenance option that aligns with decarbonization priorities.
- Eaton (Ireland/USA operations) — Focused on medium‑voltage generator breaker performance optimized to IEEE duty classes, Eaton’s strength lies in engineered vacuum interrupter designs for smaller and mid‑sized generator sets, with emphasis on continuous current capability and reliability.
Key industry dynamics shaping vendor and buyer choices
- Standards and duty differentiation: GCBs must satisfy generator‑specific continuous current and short‑circuit duties that differ materially from distribution breakers. Procurement language that conflates the two is a persistent source of field failure and contractual disputes.
- Environmental regulation and technology substitution: The transition away from SF6 — driven by emissions policy and corporate sustainability targets — is accelerating adoption of vacuum interrupter technologies. Buyers should assess asset‑level tradeoffs between retrofit complexity, lifecycle OPEX, and regulatory risk.
- Digitalization as an operational lever: Embedded monitoring and analytics alter the value equation for spare parts, testing intervals, and workforce allocation. Pilot programs that demonstrate measurable uptime gains and maintenance deferral are now preconditions for capital approval in many utilities.
- Consolidation pressure and aftermarket economics: High CR3/CR5 concentration suggests bargaining power for incumbent suppliers to monetize digital and service capabilities. Buyers must design procurement processes that protect against lock‑in while capturing future upgrade optionality.
Strategic recommendations for 2026 (concise, actionable)
- Mandate digital readiness in all RFPs: Require native sensor telemetry, standard communication protocols (e.g., IEC 61850, Modbus TCP), and clear data ownership terms. Insist on demonstrable integration pathways to enterprise Asset Health platforms.
- Prioritize lifecycle TCO over headline capital cost: Use the report’s TCO calculator to compare buy, retrofit, and service models over a 10–20 year window; include outage cost assumptions specific to plant type and grid exposure.
- Start retrofit pilots for high‑value units: Deploy small, measurable pilots (3–5 units) that combine condition monitoring with predictive workflows. Use results to standardize retrofit specs and institutionalize altered maintenance KPIs.
- Embed compliance testing in acceptance plans: Tighten factory and site acceptance tests to the IEC/IEEE generator duty standards to avoid post‑commissioning nonconformances.
- Mitigate supplier concentration risk: Maintain dual‑sourcing options for critical components and negotiate spare‑parts consignment or guaranteed lead‑time clauses where feasible.
How to use the PW Consulting report in your 2026 decision cycle
- Immediate (0–3 months): Run the report’s fleet diagnostic to identify candidate units for digital retrofits and include mandatory digital clauses in any new RFPs being drafted.
- Near term (3–12 months): Execute retrofit pilots, finalize supplier scorecards, and negotiate service‑based contracts that align incentives for uptime improvements.
- Strategic (12–36 months): Implement an enterprise‑wide Asset Health Management approach, scale successful pilots, and reassess fleet renewal timing using the report’s scenario models.
PW Consulting’s Worldwide Digital GCB Market study offers the granular frameworks, vendor intelligence, and executable templates necessary to convert market insight into procurement and operational advantage in 2026. To preserve competitive value and encourage evidence‑based decision making, this release intentionally highlights directional findings and strategic prescriptions while directing practitioners to the full report for detailed segmentation, interactive dashboards, raw time‑series, and downloadable vendor scorecards.
For executives preparing budgets, retooling maintenance strategies, or assessing acquisition targets, the full report provides the empirical dataset and commercial tools needed to act with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Generator Circuit Breaker (GCB) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Memory Packaging Market to Expand at a Robust 10.53% CAGR Through 2026–2032
By pmarketresearch, 2026-07-15
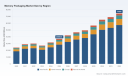
Worldwide Memory Packaging Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic briefing derived from our new Worldwide Memory Packaging Market report (base year 2025). This note highlights the macro trajectory, competitive dynamics, and executable plays that corporate leaders must weigh when setting 2026 priorities. Consider this a trailer: we reveal the directional intelligence and high-conviction implications you need to act, while preserving detailed segment-level tables and proprietary scenario outputs for subscribers of the full report.
Worldwide Memory Packaging Market
Macro outlook: a growing, structurally shifting market
The memory packaging market entered 2026 from a position of renewed momentum. Our model pegs the global market at approximately USD 36,898.6 Million in 2025, expanding to roughly USD 42,140.5 Million in 2026. Over the 2026–2032 forecast window the market is projected to grow at a compound annual growth rate (CAGR) of 10.53%, reaching an estimated USD 74,380.0 Million by 2032. These headline numbers reflect both cyclical recovery elements and durable structural drivers—chiefly accelerated demand for higher-bandwidth memory solutions, greater outsourced packaging intensity among IDMs, and sustained investments in advanced packaging technologies.
Worldwide Memory Packaging Market
Why this matters for 2026 corporate strategy
- Capital allocation must be proactive, not reactive: with double-digit projected growth through 2032, 2026 is an inflection year for capacity planning and capex sequencing. Late entry risks elevated costs and missed revenue capture as advanced packaging adoption accelerates.
- Pricing power has shifted: early-2026 price adjustments announced by several OSATs indicate tighter near-term capacity and a potential re-rating of packaging margins — companies should update pricing and contract playbooks accordingly.
- Regulatory and geopolitical overlays change the calculus for location and partner selection. Export controls and tariff measures add execution risk to cross-border packaging strategies and should be embedded into 2026 sourcing decisions.
Competitive landscape — OSATs, specialists and shifting boundaries
The market remains moderately concentrated: our concentration analysis shows the top-three suppliers control a meaningful share of revenue (CR3 ≈ 58.4%), and the top-five share is higher still (CR5 ≈ 72.15%). That structure creates opportunities for scale players to protect margins and for focused specialists to win through niche capabilities.
Worldwide Memory Packaging Market
- Advanced Semiconductor Engineering Inc. (ASE Inc.) — As a leading OSAT with deep memory packaging capabilities (covering DRAM, NAND and advanced formats such as HBM and SiP), ASE is well-positioned to capture HBM and high-density DRAM migrations. For 2026, ASE’s advantages will hinge on integrating material and process innovations into high-volume production while managing capex timing to meet rising demand without overextending.
- Amkor Technology Inc. — Amkor’s broad packaging/test footprint and experience with SCSP and advanced memory formats make it a natural partner for IDMs looking to outsource part or all of their packaging flows. In 2026, Amkor’s strategic focus should be on modular service offerings that combine packaging, testing and thermal/stacking IP to capture value higher up the stack.
- Powertech Technology Inc. (PTI), ChipMOS, STATS ChipPAC and specialist OSATs — These providers are critical capacity partners for DRAM and NAND supply chains. The early-2026 price adjustments and capacity tightness reported by several firms highlight a near-term supply-demand imbalance. For buyers, this elevates the importance of multi-sourcing, flexible contracts and capacity reservation mechanisms.
- Regional players (JCET, Hana Micron, and others) — These firms add competitive intensity, particularly in Asia, and often combine packaging with test, integration and logistics capabilities. Their proximity to major memory foundries/OEMs creates both strategic partnerships and geopolitical exposure.
Supply chain, regulation and pricing dynamics — what changed in early 2026
- Price signaling: several memory packaging and test providers announced price increases of up to 30% in early 2026 amid tight DRAM/NAND packaging capacity. This is not simply tactical — it signals a material rebalancing of supplier leverage. Buyers should stress-test profitability under various pricing scenarios and consider indexed contracts or tiered take-or-pay arrangements.
- Export controls & tariffs: new U.S. export controls and a 25% tariff on certain advanced compute chips have reverberations beyond chip sales. Packaging flows for advanced packaging SME, HBM and certain DRAM products are subject to licensing complexity, increasing lead times and compliance costs. Companies must embed export-control expertise into commercial and procurement teams.
- Materials & critical minerals: export controls and supply constraints on elements like gallium (and broader upstream materials pressure) create upstream vulnerability. Sourcing strategies in 2026 must include alternative suppliers, dual-sourcing of critical materials, and longer-term offtake or strategic inventory plans.
- Technology partnerships: notable R&D collaborations (for example, an Applied Materials–SK hynix partnership announced in March 2026) underscore that equipment and materials co-innovation will accelerate tooling and process development cycles for next-generation DRAM and HBM. Expect faster throughput improvements and declining per-unit advanced packaging costs over the medium term as these co-innovations scale.
Strategic playbook for 2026 — action priorities
Below are pragmatic, prioritized actions executives should consider this year. These are structured to be implementable within 6–18 months, aligned to the market trajectory and regulatory environment.
- Immediate (0–6 months):
- Run scenario-based pricing and margin stress tests that incorporate up to a ~30% differential in packaging costs and extended lead-times for advanced SKUs.
- Conclude a rapid sourcing audit to identify single points of failure (critical materials, single-factory dependencies) and negotiate contingency capacity with at least two OSAT partners.
- Deploy export-control and tariff impact assessments for all product lines that rely on advanced packaging (HBM, high-density DRAM, specialty NAND) and update commercial contracts to reflect licensing risk.
- Near term (6–12 months):
- Prioritize capacity flex: finance short-cycle expansions and take-or-pay agreements that secure capacity for high-value SKUs rather than broad-based capacity bets.
- Form strategic R&D or co-investment partnerships with equipment and materials suppliers to accelerate adoption of TSV/3D, fan-out and other advanced packaging processes that improve power, latency and form-factor metrics.
- Revise product roadmaps to accelerate offerings that benefit from advanced packaging (e.g., high-bandwidth modules, heterogeneous memory+logic integration) and align go-to-market teams accordingly.
- Medium term (12–24 months):
- Pursue bolt-on M&A or minority investments in regional OSATs where regulatory exposure is acceptable — focus on capabilities (e.g., 3D stacking, fan-out) and near-term capacity rather than pure revenue scale.
- Invest in traceability and compliance systems that reduce time-to-license and simplify cross-border transfers for regulated SKUs; these systems create long-term commercial differentiation.
What the full PW Consulting report contains (practical, subscription-grade deliverables)
For executives and strategy teams preparing detailed plans, the full Worldwide Memory Packaging Market report includes:
- Comprehensive historical dataset (2020–2025) and a granular forecast (2026–2032) in USD Million with scenario sensitivity analyses and a 10.53% forecast CAGR baseline.
- Segmented forecasts by packaging technology, memory type and region (presented with interactive pivotable tables and downloadable models) — note: the high-resolution segmentation tables are available in the full report only.
- Competitive profiles and capability matrices for the leading OSATs and specialist suppliers, with SWOT-style implications and supplier-vetting checklists.
- Practical playbooks: capex modeling templates, pricing negotiation playbooks, regulatory compliance checklists and M&A screening frameworks tailored to memory packaging.
- Case studies illustrating successful outsourcing transitions, co-development partnerships with equipment vendors, and contingency sourcing implementations during supply tightness.
Closing synthesis — the mandate for 2026
2026 will be the year many companies choose between being followers who absorb rising packaging costs and compliance burdens or being architects who design supply chains, pricing models and product roadmaps to capture the market’s next wave. With the market expanding from an estimated USD 36.9 Billion in 2025 to a projected USD 74.4 Billion by 2032 under our baseline, the opportunity is material but conditioned on decisive moves in sourcing, technology partnerships and regulatory preparedness.
PW Consulting’s full report gives executives the granular data and tactical templates needed to make those 2026 decisions with confidence. For organizations that want the complete dataset, supplier scorecards, and executable roadmaps, please consult the full report on the PW Consulting website or contact your PW representative for a briefing and model access.
For detailed analysis of this topic, please visit the official page: Worldwide Memory Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pod Hotel Market Set to Expand at a 7.15% CAGR, Outlook Strengthens
By pmarketresearch, 2026-07-15
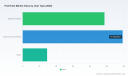
Pod Hotel Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence Brief
PW Consulting today releases a forward-looking industry brief on the global Pod Hotel Market that is designed to inform C-suite decisions, institutional investment theses, and operational playbooks for 2026 and beyond. Grounded in a 2020–2025 historical baseline and a 2026–2032 forecast horizon, the study synthesizes primary interviews, operator financials, site-level economics and regulatory intelligence into a compact, action-oriented resource for executives who must move from opportunity recognition to deployable strategy.
Pod Hotel Market
Executive snapshot
The pod hotel sector has transitioned from a niche urban curiosity to a repeatable product class with measurable unit economics and growth runway. On an aggregate basis the market expanded from roughly USD 170 million (2020) to USD 245.5 million in our base year (2025). Using 2026 as the launch-point for our forecast, we model the sector to grow at a compound annual growth rate of 7.15% through 2032, reaching approximately USD 398.1 million by the end of the forecast window. These headline metrics underscore a healthy growth trajectory that is large enough to attract mainstream hospitality capital while remaining sufficiently fragmented to reward early movers with disciplined execution.
Pod Hotel Market
Why 2026 is a pivot year
-
Capital readiness: Lower per-unit construction cost and modular manufacturing make greenfield and conversion strategies capital-feasible faster than traditional hotels. Industry benchmarking indicates pod unit construction typically sits materially below that of full hotel rooms, delivering faster payback periods in properly located projects.
Pod Hotel Market -
Operational scalability: Standardized, tech-driven pod designs enable high levels of automation and remote management, compressing staffing needs and enabling operators to replicate concepts across geographies.
-
Customer segmentation and channel evolution: Demand from time-constrained travelers (including transit and short-stay segments) alongside budget-conscious urban leisure guests provides a multi-channel demand base. At the same time, distribution and pricing dynamics (OTAs versus direct channels) are evolving and materially affect RevPAR capture.
-
Regulatory clarity and safety standards: As local authorities adopt clearer guidance on compact accommodation—fire safety, ventilation, privacy and shared facilities—compliant designs are becoming a necessary competitive moat.
Market dynamics that matter to decision-makers
-
Unit economics drive site strategy. Our analysis shows pod construction benefits from factory modularization and lower on-site labor intensity, enabling deployment cycles measured in months rather than years. This materially reduces time-to-revenue for new sites and supports portfolio rollouts driven by site economics rather than pure brand expansion.
-
Fragmented competitive structure. The market remains fragmented: incumbent specialist operators and new entrants coexist, leaving white space for scalable platforms and local partners. Market concentration metrics indicate that the leading firms do not yet control a dominant share, creating acquisition and roll-up opportunities for strategic buyers and PE sponsors.
-
Cost profile and capex benchmarking. Industry sources point to a broad capex envelope for pod units that is substantially lower than conventional hotel rooms—supporting payback horizons in the 2–4 year range for well-located assets. These capex differentials alter hurdle rates and permit more aggressive yield-management and transient pricing strategies.
-
Regulation and standards are a gating factor. Operators must design to local building codes covering fire safety, ventilation, privacy and accessibility. Early engagement with regulators and adherence to evolving standards are essential to avoid retrofit costs and operational restrictions.
Competitive landscape — positioning and strategic moves
The competitive set is varied, comprising purpose-built capsule specialists, hybrid lifestyle brands, airport-centric sleep solutions, and modular system providers. Key operator archetypes include minimalist sleep-first chains, premium “cabin” concepts, airport transit specialists, and franchisable urban boutique operators. Representative firms we analyze in detail include:
-
nine hours Inc. (Tokyo) — a minimalist, sleep-optimization chain integrating technology and health partnerships; recently announced a new Shinjuku property slated for mid-2026 launch with an institutional collaboration focused on sleep and health monitoring.
-
First Cabin (Japan) — positions cabins as an elevated alternative between capsule and business hotels, targeting travelers seeking compact but premium amenities and expanding selectively into international leisure gateways.
-
YOTEL (London) — adapts an airline-cabin-inspired model across urban and airport sites with a strong emphasis on tech-enabled guestrooms and public spaces.
-
Bobobox (Indonesia) — a tech-forward, modular operator scaling rapidly in domestic markets and building a playbook for regional rollouts; announced significant network expansion activity in recent years.
-
GoSleep (Finland), napcabs GmbH (Germany), Sleepbox (USA), and The Pod Hotel (New York) — collectively illustrate the breadth of use cases from airport transit pods and workplace rest solutions to urban lifestyle capsule hotels.
Recent operator developments—new openings, network expansions and construction starts—confirm that both specialty players and mainstream brands are actively testing formats and channel mixes. For investors, this means a market where occupancy uplift and pricing premium derive not only from location but also from brand positioning and tech-enabled guest experiences.
What the PW Consulting brief delivers (practical assets)
-
Decision-ready financial models: customizable unit-economics templates for capex, opex and scenario testing that allow rapid evaluation of single-site pilots and five-site rollouts.
-
Site-selection framework: a replicable heatmap methodology that blends demand density, transit flows and regulatory feasibility to prioritize target markets without exposing sensitive segmentation tables in this preview.
-
Operational playbooks: staffing, maintenance, and tech-stack blueprints designed to lower operating costs and stabilize guest satisfaction in mixed-use and airport environments.
-
Regulatory and safety checklist: a curated checklist of local-code touchpoints and certification pathways to accelerate permitting and reduce retrofit risk.
-
Partnering and distribution matrix: strategic guidance on OTA vs. direct channel mix, franchise structures and capex-lite partnerships with landowners and transit hubs.
Strategic imperatives for 2026
-
Adopt a “pilot-and-scale” approach. Run tightly instrumented pilots (3–5 sites) to validate unit economics before committing to larger rollouts. Use pilots to refine yield management, channel strategy and guest experience frameworks.
-
Prioritize compliance-led design. Invest up-front in designs that meet or exceed local safety and ventilation standards to minimize time-to-market and long-term retrofit exposure.
-
Leverage modular build and supplier partnerships. Lock in modular pod suppliers and factory capacity to control cost, quality and deployment schedules—critical inputs for delivering on the short payback promise.
-
Differentiate via experiences and adjacent services. For urban leisure and business segments, adjacency services (luggage storage, micro-workspaces, health/sleep partnerships) free up pricing power beyond base bed-nights.
-
Manage channel economics actively. Optimize OTA relationships with tailored promotions and loyalty integrations to protect direct-booking margins while maintaining reach.
Risk map and mitigations
-
Construction and supply-chain volatility — mitigate through long-lead procurement, modular contracts and local supplier diversification.
-
Regulatory uncertainty — engage early with authorities, maintain adaptive designs and budget for incremental compliance costs.
-
Demand concentration — diversify site typologies (airport, urban core, tourist corridors) to smooth occupancy cycles.
-
Labor and operations — deploy automation where it preserves guest experience and reduces routine labor dependency.
Next steps and how to use this intelligence
For executives preparing 2026 capital plans, this brief is structured to accelerate decision cycles: run our unit-econ templates against your target markets; deploy a two-quarters pilot budget; and select modular supply partners to shorten development timelines. PW Consulting’s full report provides granular regional and user-type segmentation, channel-by-channel revenue build-ups, and pro forma case studies. Those detailed appendices and proprietary models are intentionally gated to preserve commercial value and are available through our research portal.
In summary, the pod hotel market presents a near-term pathway to asset-light expansion, attractive payback intervals and differentiated guest propositions — but success hinges on disciplined site selection, compliance-centric design and a technology-enabled operating model. PW Consulting’s new brief equips leaders with the operational templates, financial models and competitive diagnostics required to convert potential into profitable scale in 2026.
For detailed analysis of this topic, please visit the official page: Pod Hotel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 7.82% CAGR for Worldwide High-Speed Spectroscopy Cameras Market Through 2032
By pmarketresearch, 2026-07-15
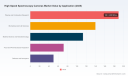
Worldwide High Speed Spectroscopy Cameras Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s new market study on Worldwide High Speed Spectroscopy Cameras delivers a focused, action-oriented perspective tailored for C-suite and technical leaders preparing strategy and investment decisions in 2026. The sector has shown resilient expansion — growing from roughly 395 million USD in 2020 to about 564 million USD in 2025 — and the report forecasts continued momentum through the 2026–2032 horizon with a compound annual growth rate of 7.82%, reaching an estimated 955.6 million USD by 2032. These macro dynamics create both opportunity and complexity: accelerating demand across biomedical, industrial inspection, and defense use cases, while advancing sensor architectures, software stacks and regulatory expectations reshuffle competitive advantage.
Worldwide High Speed Spectroscopy Cameras Market
Why this report matters for 2026 planning
-
Actionable foresight, not just numbers. The study translates market trajectory into prioritized decision levers: product roadmap sequencing, channel and partnership strategies, CapEx versus OpEx trade-offs for clinical customers, and near-term M&A opportunities for strategic buyers.
Worldwide High Speed Spectroscopy Cameras Market -
Operational due diligence support. For procurement and integration teams, we map technology risk to implementation timelines — critical when integrating high line-rate cameras into multimodal imaging systems used in operating rooms, research labs, or high-throughput production lines.
Worldwide High Speed Spectroscopy Cameras Market -
Regulatory and reimbursement navigation. The report synthesizes applicable regulatory pathways (e.g., ISO 13485, FDA 510(k) processes) and current reimbursement context that materially affect commercialization timelines for diagnostic and clinical imaging applications.
Market trajectory and its strategic implications
The high-speed spectroscopy camera market’s steady ascent through the first half of the decade reflects a confluence of factors: rising demand for spectral precision in clinical diagnostics and material characterization, broader adoption of hyperspectral imaging in industrial inspection, and continued miniaturization enabling OEM embedding. For 2026, this translates into three pragmatic implications:
-
Prioritize modular architectures. Buyers and systems integrators should favor camera and software platforms that decouple sensor upgrades from core system electronics — enabling faster responsiveness to sensor-driven performance improvements without full system redesigns.
-
Invest in low-noise, high-line-rate capabilities for clinical/biomedical playbooks. Emerging clinical applications (e.g., OCT-integrated spectral modules and NIR-based tissue perfusion monitoring) make cameras with both high line rates and low-noise characteristics strategic assets for device OEMs and hospital imaging centers alike.
-
Balance near-term revenue capture against long-term platform bets. Investors and product leaders must weigh the economics of premium sensor adoption (e.g., sCMOS and advanced SWIR detectors) against the growing market for compact, embedded hyperspectral modules that enable high-volume industrial deployments.
Competitive landscape — what the leading vendors signal
The market shows moderate concentration: the top three vendors command a meaningful share of installed capabilities, and the leading five account for a clear majority of market presence. This topology favors companies that combine differentiated sensor IP with strong application expertise and global channel access.
-
Andor Technology (Oxford Instruments): With deep technical roots in high-sensitivity sCMOS, EMCCD and CCD offerings, Andor’s Newton and iDus lines continue to be reference points for academic and clinical spectroscopy customers seeking low-light, high-fidelity capture.
-
Teledyne Princeton Instruments: Known for low-noise, high-speed CCD and sCMOS cameras, Teledyne’s product set is frequently chosen for Raman, hyperspectral and transient spectroscopy where signal integrity is paramount.
-
Hamamatsu Photonics and HORIBA Scientific: These established players bring a combination of detector R&D and instrument-level expertise — particularly relevant for near-infrared spectroscopy and deep-cooled, clinical-grade imaging modules.
-
Specim (Konica Minolta), Headwall Photonics and HySpex: Specialization in push-broom hyperspectral cameras and integrated systems positions these firms to win in industrial inspection and research imaging segments that demand line-scan throughput and broad spectral bands.
-
XIMEA, Photon etc., BaySpec: The emergence of miniaturized, OEM-friendly modules from these vendors accelerates adoption in embedded and device-integrated applications, an area attractive to medtech OEMs and automated inspection integrators.
Recent product activity underscores a rapid cadence of capability refresh. Notable announcements in 2025–2026 include a high-speed NIR–SWIR push-broom camera introduced by a leading hyperspectral manufacturer, new rectangular-pixel SWIR camera roadmaps presented at major industry forums, and updated SWIR hyperspectral datasheets from established distributors. For 2026 decision-makers, these moves mean price/performance thresholds will shift, and first-mover advantages will accrue to organizations that align procurement timing with platform refresh cycles.
Technology trends shaping procurement and R&D choices
-
sCMOS and EMCCD evolution: The drive for higher quantum efficiency at reduced noise continues to push sCMOS into a wider set of spectroscopy and fast-imaging use cases. Systems architects should evaluate camera latency, thermals and readout modes as core selection criteria.
-
SWIR and InGaAs advances: Extended spectral coverage is enabling material differentiation in industrial and biomedical contexts, but SWIR economics and integration complexity require careful systems-level validation and thermal management planning.
-
Hyperspectral vs. multispectral trade-offs: For many applications, faster push-broom or snapshot hyperspectral systems provide operational advantages. Report guidance helps teams decide when spectral fidelity justifies higher system cost versus targeted multispectral solutions.
-
Miniaturization and OEM integration: Miniature cameras and embedded modules open new productization pathways for device OEMs, accelerating go-to-market when paired with robust software abstraction layers and standardized interfaces.
Regulatory, reimbursement and clinical adoption factors
For players targeting diagnostic and clinical workflows, regulatory compliance and reimbursement posture materially influence time-to-market. Key considerations covered in the study include:
-
Quality management and device pathways: Conformance with ISO 13485 and alignment with FDA 510(k) expectations for Class II imaging systems are baseline requirements for clinical deployments.
-
Reimbursement landscape: High-speed spectroscopy applications such as near-infrared monitoring for wound or flap management currently operate within established Medicare coverage frameworks; however, the absence of specific CPT updates for 2025–2026 means commercial models must combine device-level evidence generation with local coverage strategies.
-
Clinical integration: Hospitals’ CapEx and research investment trends favor multimodal platforms that can be upgraded with spectral modules; vendors that provide proven integration kits, clinical validation support and interoperability roadmaps will accelerate adoption.
What the PW Consulting report delivers — practical, executable content
-
Tactical vendor scorecards and capability maps that help procurement teams short-list suppliers based on performance, integration risk and service footprint.
-
Productization playbooks for OEMs that cover sensor selection criteria, thermal and firmware integration templates, and recommended testing sequences for clinical and industrial validation.
-
Regulatory checklists and time-to-market models estimating resource needs for ISO 13485 alignment and FDA 510(k) filings in diagnostic use cases.
-
Commercial models for investors: scenario-driven revenue projections, margin sensitivities and acquisition candidate screening criteria tied to platform stickiness and IP defensibility.
-
Use-case impact analyses that translate sensor specs into operational outcomes for biomedical imaging, material inspection and high-throughput manufacturing.
How to use this intelligence in 2026
-
For corporate strategists: use the report to prioritize R&D and M&A agendas — focus on complementary sensor IP, software analytics and go-to-market reach that accelerate platform adoption.
-
For product managers and systems integrators: align procurement and prototype cycles to vendor roadmap announcements; leverage modularity to defer large CapEx until sensor improvements are validated.
-
For hospital and lab procurement leaders: request interoperable, upgradeable modules and insist on clinical evidence packages and regulatory readiness as part of bidding criteria.
-
For investors: prioritize companies that combine differentiated sensor roadmaps with recurring service or software revenue streams to mitigate hardware commoditization risk.
Where the report withholds and why
The study is deliberately designed as a decision-enabling product: it surfaces strategic findings, vendor insights and implementation playbooks while preserving detailed node-level segmentation tables, precise regional and application revenue breakdowns, and proprietary vendor scoring matrices for subscribers. This “teaser” approach ensures readers can rapidly assimilate the strategic implications while requiring a deeper engagement to access the granular data needed for high-stakes procurement or transaction diligence.
Next steps
For executives preparing 2026 roadmaps, the report serves as both a yardstick and a playbook. PW Consulting recommends an immediate 90-day sprint to: (1) test modular integrations with one or two leading sensor suppliers, (2) initiate clinical or industrial validation pilots tied to reimbursement or productivity KPIs, and (3) conduct a regulated-product readiness audit covering ISO 13485 and 510(k) pathways. These steps de-risk later-stage scale-up and align R&D investments to the market’s 7.82% CAGR trajectory through 2032.
To explore the full set of findings, proprietary vendor assessments and the complete dataset underlying our forecasts, please consult the full Worldwide High Speed Spectroscopy Cameras Market report on the PW Consulting website.
For detailed analysis of this topic, please visit the official page: Worldwide High Speed Spectroscopy Cameras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 4.58% CAGR for Worldwide 2D Ablation Catheter Market, Rising from USD 552.48 Million in 2025 to USD 755.93 Million by 2032
By pmarketresearch, 2026-07-15
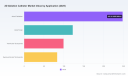
PW Consulting: Strategic Preview — Worldwide 2D Ablation Catheter Market Outlook and Decision Playbook for 2026
PW Consulting today releases a strategic preview of our forthcoming Worldwide 2D Ablation Catheter Market report, designed to equip executives, product leaders, and investment teams with the evidence-based perspective they need to make high-conviction decisions in 2026. This briefing synthesizes our macro-sizing, trend diagnostics, competitive read, and pragmatic recommendations — while reserving the full, granular segment intelligence for the complete report.
Worldwide 2D Ablation Catheter Market
Why this market matters in 2026
Cardiac electrophysiology remains one of medtech’s higher-velocity innovation corridors. The 2D ablation catheter market — encompassing radiofrequency, cryo, and emergent energy modalities together with intracardiac echo support — exhibits a steady, investment-grade growth profile that is driven by an ageing patient base, broader adoption of minimally invasive electrophysiology workflows, and incremental clinical evidence supporting multi-energy strategies. PW Consulting’s top-line sizing reaffirms a resilient expansion: the market grew from roughly USD 442 million in 2020 to about USD 552 million in the 2025 base year, and under our central forecast it continues to strengthen across 2026–2032 with a compound annual growth rate of 4.58%, reaching an estimated USD 756 million by 2032.
Worldwide 2D Ablation Catheter Market
What senior leaders will find most valuable
- Actionable strategy, not just data: We translate growth vectors into decision frameworks for product investment, commercialization sequencing, and M&A prioritization — for example, how to allocate R&D between incremental catheter improvements vs. platform-level mapping and imaging integrations.
- Near-term inflection points: 2025–2027 is an execution horizon where regulatory clears, system compatibility, and early post-market data determine durable adoption. Our report isolates the clinical and commercial triggers that will separate winners from followers in that window.
- Practical go-to-market playbook: Segmentation-agnostic tactical guidance on channel strategy, hospital procurement dynamics, and cross-selling opportunities with mapping and ICE imaging systems.
- Risk calibration: Scenario-based risk matrices that quantify exposure to reimbursement shifts, regulatory timing variance, and competitive product launches.
Data-driven view: growth trajectory and composition (high level)
The market’s historical trajectory shows recovery after near-term volatility and a return to steady expansion. From an estimated USD 442 million in 2020, the market expanded to roughly USD 552 million by 2025. Our 2026 base projection shows continued expansion with compound growth averaging 4.58% across the 2026–2032 forecast period, culminating near USD 756 million in 2032 under the base case. These macro figures reflect a mixed dynamic: stable demand for mature RF and cryo technologies, coupled with rising clinical interest and early adoption of pulsed field and multi-energy catheters, and increasing use of 2D intracardiac echo for procedural guidance.
Worldwide 2D Ablation Catheter Market
Importantly, market concentration is meaningful: the three largest vendors account for a majority share of the market, while the top five capture an even larger proportion, evidencing an environment where scale advantages — in mapping systems, cross-device interoperability, and sales reach — materially influence competitive outcomes. This structure favors integrators and platform players but leaves space for focused specialists with differentiated technology or compelling cost-of-care value propositions.
Competitive landscape — what to watch
Our proprietary competitive mapping examines product portfolios, systems interoperability, clinical evidence, go-to-market models, regulatory milestones, and geographic footholds. Core incumbent and growth companies to track include established platform players (notably those offering RF portfolios with integrated 3D mapping and intracardiac echo solutions), major diversified medtech firms advancing sensor-enabled contact-force catheters and pulsed-field pilots, and several regional innovators pushing competitive cost structures and fast local approvals.
- Platform incumbents continue to leverage mapping-system lock-in and integrated imaging to preserve premium pricing and procedural preference. Recent launches of advanced 2D ICE catheters and mapping integrations have reinforced these incumbents’ procedural value propositions.
- Major electrophysiology OEMs are actively entering multi-energy strategies — RF, cryo, and pulsed field — to hedge clinical uncertainty and to offer differentiated safety/performance claims for specific arrhythmia subtypes.
- New approvals and regional launches are reshaping competitive dynamics: targeted regulatory clears and CE/PMAs in 2025–2026 have accelerated clinical adoption cycles in several markets, altering short-term demand patterns.
To maintain the "trailer" principle of this preview, we do not disclose product-level or regional market shares here; the full report contains supplier scorecards, product lifecycles, and modelled share curves that convert qualitative positioning into quantitative revenue impact scenarios.
Selected near-term developments and strategic implications
- Advanced ICE catheter launches: New 2D intracardiac echo products introduced in 2025 improve intraprocedural visualization and mapping compatibility. For hospital systems and reference labs, this raises the bar for imaging-enabled ablation workflows. Strategy implication: vendors must prioritize mapping and imaging compatibility or create bundled service propositions to capture the upgrade cycle.
- Regulatory wins for robotic and magnetic navigation: FDA approvals for robotically navigated ablation tools in early 2026 validate robotic adjuncts in complex cases. Strategy implication: capital allocation to navigated systems, training programs, and cross-selling to congenital-heart centers will drive differentiated adoption.
- Pulsed field momentum: Regional approvals for sensor-enabled pulsed-field platforms in 2025–2026 are creating a bifurcation in clinical trials and hospital purchasing committees between multi-energy platforms and single-energy incumbents. Strategy implication: capture early PFA real-world evidence or risk constraining long-term competitive credibility.
- Reimbursement and procedure coding dynamics: Current CPT and MS-DRG structures do not consistently differentiate by energy modality. In the short term this favors clinical adoption of newer energy sources; however, practice expense recalibrations and coding updates could change margins for high-cost disposable strategies. Strategy implication: commercial teams need to build payer dossiers demonstrating cost-per-outcome improvements to protect premium pricing.
Clinical and commercial inflection zones
PW Consulting identifies four high-impact inflection zones that will drive strategic outcomes between 2026 and 2028:
- Interoperability and data integration: The winners will be those who reduce friction in EP lab workflows by delivering seamless mapping-to-ablation-to-echo data flows, enabling shorter procedure times and clearer outcomes tracking.
- Evidence generation cadence: Rapid, prospective registries and pragmatic randomized trials will be decisive for procedure-level reimbursement and hospital formulary inclusion.
- Service and training ecosystems: As devices become more complex, post-sale services, lab optimization, and physician training packages are becoming revenue multipliers and adoption accelerants.
- Pricing and cost-of-care narratives: Hospitals will increasingly assess catheters as part of a system-level cost equation; manufacturers must be able to quantify total-case economics, not just disposable unit price.
What the full report contains (practical and proprietary deliverables)
PW Consulting’s full Worldwide 2D Ablation Catheter Market report is structured for immediate operational use. Highlights include:
- Comprehensive market sizing and base-year reconciliation, with a transparent methodology and sensitivity testing across alternate adoption curves.
- Forecasts to 2032 with scenario analysis (base, upside, downside) and modular access to regional, type and application splits for bespoke client modelling.
- Vendor scorecards and product lifecycle maps tied to clinical evidence, regulatory pathway timelines, and commercialization readiness assessments.
- Go-to-market playbooks and sales-force deployment models, including hospital segmentation, tender strategies, and channel partnership frameworks.
- Due diligence annexes for M&A and licensing — including valuation multipliers, comparables, and integration risk checklists.
- Reimbursement and regulatory pathway deep dives, with templates for payer engagement and coding change advocacy.
In keeping with our preview intent, the full product includes the granular regional and application split matrices, product-level revenue forecasts, and pricing models that underpin the market totals summarized above.
Strategic recommendations for 2026
- Prioritize interoperability investments: Allocate development resources to ensure mapping and ICE compatibility; this is a higher-return pathway than incremental disposable feature upgrades in the current market phase.
- Accelerate evidence generation: Fund multi-center registries that highlight case-time reductions and complication-rate improvements; these datasets meaningfully influence hospital procurement committees and payer conversations.
- Design bundled service offers: Pair disposables with lab-optimization services, training, and outcome analytics to lock-in clinical preference and create annuity-like revenue streams.
- Calibrate M&A selectively: Target acquisitions that deliver either mapping/ICE capability or differentiated energy technology with clinical data — not merely incremental market share — to move the needle on product portfolios and scale economics.
- Prepare for coding sensitivity: Build payer-value dossiers early and participate in coding advisory groups to mitigate practice expense reassignments that could compress margins.
How to use this preview
This preview is intended to frame executive decision-making for product planning, commercial investments, and corporate development through 2026. For teams prioritizing new product introductions, strategic alliances, or M&A activity in the electrophysiology space, the full PW Consulting report delivers the detailed, auditable analytics required to create investment memos, build revenue models, and shape regulatory strategies.
To access the complete Worldwide 2D Ablation Catheter Market report — including the proprietary regional and application splits, supplier share models, and product-level forecasts — please visit the PW Consulting report portal. The full study is the vehicle for converting the directional insights presented here into precise, executable plans.
About PW Consulting
PW Consulting is a strategic advisory and industry research firm specializing in medtech markets. We combine deep clinical domain expertise, proprietary market models, and transaction-grade diligence to help clients make faster, better-informed strategic decisions. The Worldwide 2D Ablation Catheter Market study is part of our ongoing coverage of cardiac rhythm management and electrophysiology.
For detailed analysis of this topic, please visit the official page: Worldwide 2D Ablation Catheter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com