

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Laminating Lithium‑ion Capacitor Market Set to Surge at a 18.54% CAGR Through 2032

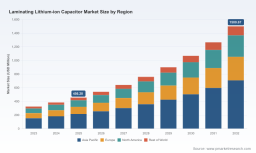
Worldwide Laminating Lithium‑ion Capacitor Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s newest market study on the Worldwide Laminating Lithium‑ion Capacitor (LIC) market provides a forward‑looking, decision‑grade intelligence package designed for senior executives, product and supply‑chain leaders, and corporate development teams planning for 2026 and beyond. Anchored on a 2025 base year and extending through 2032, the analysis quantifies an accelerated growth trajectory (CAGR 18.54%) and translates that growth into the commercial choices companies must make today to capture position and margin in a rapidly maturing technology ecosystem.
Worldwide Laminating Lithium-ion Capacitor Market
Key market trajectory — what the numbers imply for strategy
-
The laminated LIC market has moved from early commercialization into scale‑up. Historical sizing shows consistent expansion through 2023–2025, and our forecasts anticipate that trajectory accelerating from 2026 onwards. This industry‑level momentum — reflected in a mid‑teens compound annual growth rate (18.54%) through 2032 — creates both timing pressure and windows of opportunity for first movers, fast followers and systems integrators.
Worldwide Laminating Lithium-ion Capacitor Market -
By anchoring strategy to our 2025 base year, organizations can translate growth expectations into production, procurement and route‑to‑market investments that avoid common scale‑up missteps (e.g., over‑capitalization against immature demand, or underinvestment when adoption inflects).
Worldwide Laminating Lithium-ion Capacitor Market -
The market structure is moderately concentrated: the top three vendors account for a majority share, and the top five approach three‑quarters of the market by revenue. This concentration amplifies the influence of incumbent suppliers while still leaving room for new entrants with differentiated technology or manufacturing economics.
Why 2026 is a pivotal planning horizon
-
Near‑term capacity and certification events in 2025–2026 will shape which suppliers can meaningfully address industrial, transportation and grid applications at scale. Firms that align product roadmaps and sourcing strategies to that supply picture will preserve optionality and pricing leverage.
-
Technology convergence — notably in laminated pouch construction and dry‑electrode processes — is lowering some barriers to higher energy‑density and manufacturability. IP transfers and licensing activity are accelerating the diffusion of manufacturing know‑how from battery processes into LIC production lines.
-
Supply‑chain volatility for activated carbon and lithium, compounded by tariff dynamics and geopolitical shifts, will make strategic sourcing and nearshore manufacturing more than a cost exercise: it will be a resilience play that materially affects time‑to‑market and total landed cost.
What practitioners will find inside the report
-
Transparent market sizing and forecasting methodology (historical 2020–2025 base; forecast 2026–2032), including scenario and sensitivity runs that translate macro drivers into actionable revenue and capacity planning benchmarks.
-
Technology and manufacturability roadmap: laminated cell processing options, dry‑electrode and pre‑doping pathways, materials tradeoffs and yield drivers. This section is geared to R&D and operations teams evaluating CAPEX and process selection.
-
Commercial segmentation frameworks and go‑to‑market playbooks for OEMs, system integrators and component suppliers — constructed to prioritize channels, partner archetypes and value capture without exposing proprietary subsegment detail in this preview.
-
Supplier risk and opportunity matrix: scoring for production readiness, geographic risk, certification status and capable mass‑production technologies, plus recommended mitigation tactics for procurement and strategic sourcing leaders.
-
Competitive intelligence dossiers: in‑depth profiles, strategic positioning and likely near‑term moves for the cohort of LIC suppliers and adjacent energy‑storage players, supported by primary interviews and plant‑level verification.
-
M&A and partnership playbook: deal archetypes and valuation considerations relevant to 2026 buyers, including earn‑out structures tied to performance milestones common in capital‑intensive battery‑adjacent deals.
Competitive landscape — players to watch and why they matter
-
LICAP Technologies, Inc. — A U.S.‑based innovator advancing dry electrode approaches and domestic scaling for laminated‑compatible processes. Recent facility expansion and manufacturing collaborations indicate a push to convert lab‑scale advantages into volume supply for automotive and grid applications. For strategic buyers and Tier‑1s, LICAP is both a likely supplier and an M&A candidate depending on execution and capital intensity.
-
Musashi Energy Solutions (JM Energy) — Japan‑based with established mass‑production capability and system certifications for energy storage. Their progress on regulatory listings and modular systems makes them a credible partner for integrators prioritizing validated safety and lifecycle performance.
-
Regional fabricators (several Asian and European engineering firms) — These suppliers bring pouch/laminate manufacturing know‑how and thin‑form‑factor cell formats that appeal to constrained package spaces and high‑power burst applications. Their competitive edge is in optimized form factors and local supply‑chain synergies.
-
Specialty and hybrid suppliers — Firms combining EDLC and Li‑ion characteristics can outcompete purely capacitive providers on energy density while competing with batteries on power density and cycle life. Expect these vendors to target niches such as industrial backup, regenerative braking and power‑smoothing in renewable systems.
-
System and module integrators — Companies that pair cells with power electronics and thermal management will capture a disproportionate share of end‑customer value. The report maps which integrator capabilities matter most depending on target applications.
Supply‑chain dynamics and raw‑material constraints
-
Activated carbon supply and price volatility are key short‑to‑mid‑term constraints. Industry analyses indicate that particular biomass sources dominate feedstock supply and that current pricing sits noticeably above the cost threshold that would make certain supercapacitor electrode formulations broadly economical. This cost delta is a structural risk for players that cannot achieve material or process economies.
-
Licensing and process standardization — e.g., lithium pre‑doping techniques made available under third‑party licenses — are lowering barriers to entry by enabling producers to use conventional lithium‑ion battery equipment. That trend shortens the time and capital required to field competent laminated LIC lines, changing the competitive calculus for both incumbent battery makers and start‑ups.
-
Geopolitical pressures and tariff shifts are driving nearshoring and supplier diversification for critical inputs. Organizations that align procurement and capacity plans to anticipated commodity and trade scenarios will avoid the costly scramble many saw in prior energy‑materials cycles.
Strategic imperatives for 2026
-
Prioritize supply‑chain optionality: hedge raw‑material exposure, qualify secondary suppliers and design for material substitution where validated by lifecycle testing.
-
Invest selectively in manufacturing partnerships and licensing that accelerate time‑to‑volume for laminated formats without overcommitting capital to proprietary processes before unit economics are proven.
-
Target system‑level differentiation: marry cell performance with power electronics, thermal management and software to win in applications that prize integration (e.g., renewable smoothing, transportation ancillary systems, industrial automation).
-
Map regulatory and certification pathways early: UL and system‑level approvals materially affect adoption timelines for many end markets; certification‑focused R&D is a de‑risking investment.
-
Prepare M&A and JV playbooks: with market concentration still evolving, disciplined bolt‑on acquisitions and joint manufacturing ventures can be effective routes to scale and capability capture.
How PW Consulting helps executives translate insight into action
-
We convert the report’s market sizing, supplier scoring and scenario models into an executable 90‑day plan tailored to your role — procurement, product, operations or corporate development — aligning KPIs and investment triggers to real commercial milestones.
-
Our hands‑on vendor due diligence service verifies factory readiness, process yields and certification roadmaps so you can prioritize partners with the lowest execution risk.
-
For boards and investment committees, we prepare transaction‑oriented analyses that estimate required capex, payback timing and integration risk under multiple adoption scenarios.
PW Consulting’s Worldwide Laminating Lithium‑ion Capacitor Market report is structured to be a practical tool for 2026 planning: it balances robust quantitative forecasting with operational levers, supplier intelligence and executable strategic options. To review the complete segmentation data, granular scenario outputs and supplier scorecards that underpin these findings, please visit our report page to access the full dataset and supporting appendices.
For detailed analysis of this topic, please visit the official page: Worldwide Laminating Lithium-ion Capacitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com