

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
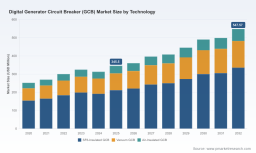
PW Consulting: Global Digital Generator Circuit Breaker Market to Rise from USD 345.5 Million in 2025 to USD 547.6 Million by 2032 at a 6.81% CAGR — SF6‑Insulated GCBs and Asia‑Pacific Lead as Top 3 Firms Control ~68.5%

Worldwide Digital Generator Circuit Breaker (GCB) Market: Strategic Imperatives for 2026 Decision‑Makers
As global power systems confront accelerating renewable integration, stricter environmental standards, and heightened expectations for plant availability, Generator Circuit Breakers (GCBs) have moved from a commoditized protection device to a strategic asset class. PW Consulting’s latest market study — the Worldwide Digital GCB Market report — synthesizes a seven‑year historical series (2020–2025) and delivers an evidence‑based forecast for 2026–2032, demonstrating both the scale and velocity of change facing asset owners, OEMs, and investors. The report shows the market crossed roughly USD 345.5 million in 2025 and is modeled to expand at a 6.81% CAGR through the forecast window, underscoring material opportunities and risks that will shape procurement and O&M choices in 2026.
Worldwide Digital Generator Circuit Breaker (GCB) Market
Why this report matters for your 2026 agenda
- Decision timing: The 2026 planning cycle is the inflection point for many utilities and plant operators who must choose between life‑extension and retrofit paths. Our analysis quantifies market momentum and outlines the tipping points where digital retrofits unlock disproportionate reductions in forced outages and maintenance spend.
- Regulatory and compliance alignment: GCBs operate under distinct high‑duty requirements (per IEEE C37.013) and installation standards (IEC/IEEE 62271‑37‑013:2021). The report maps these standards against technology choices and procurement language to reduce bid risk and future retrofit exposure.
- Operational resilience: Digital GCB architectures — combining on‑device sensors, edge aggregation, and cloud analytics — are no longer experimental. Our findings show how predictive health data changes the maintenance cadence, availability economics, and spare‑parts strategies for large plant fleets.
- Investor signals: Market concentration metrics (CR3 at 68.45% and CR5 at 82.12%) indicate a supplier landscape where a small set of incumbent players will drive technology roadmaps. Investors should weigh competitive moat, services revenue potential, and retrofit addressable markets when evaluating OEM exposure.
What the report delivers — practical, executable modules
This study is built for action. Rather than high‑level commentary, the report provides a modular toolkit that procurement, engineering, and strategy teams can apply immediately:
Worldwide Digital Generator Circuit Breaker (GCB) Market
- Robust market sizing & forecast methodology: Transparent modeling that reconciles historical deliveries (2020–2025) with component lead times, OEM production capacities, and demand drivers to project 2026–2032 trajectories.
- Technology deep dives: Comparative analysis across SF6‑insulated, vacuum, and air‑insulated GCB technologies — covering failure modes, maintenance intervals, lifecycle OPEX, and environmental implications — enabling techno‑economic tradeoff analysis without vendor bias.
- End‑user use cases and failure economics: Quantified case studies for thermal, hydro, nuclear, and integrated gas/renewable assets that translate breaker performance into outage minutes, replacement costs, and availability impacts.
- Regulatory mapping and compliance checklists: Ready‑to‑use procurement clauses and test acceptance criteria aligned to IEC and IEEE norms to reduce non‑conformance risk at bid evaluation.
- Supply‑chain risk and raw‑material outlook: Assessment of critical components (e.g., vacuum interrupters versus SF6 gas handling) and contingency strategies to mitigate long‑lead items and price volatility.
- Competitive benchmarking and vendor scorecards: Multi‑dimensional profiles of incumbent and emerging suppliers across technology, manufacturing footprint, service coverage, digital capability, and aftermarket intensity — with an objective scoring framework for RFP short‑listing.
- Digital adoption playbook: Practical architectures for on‑premise and cloud integration, edge data aggregation, cybersecurity considerations, and sample KPIs for Asset Health Management and predictive maintenance pilots.
- Commercial templates and CapEx/Opex models: TCO calculators, contract structures, and service‑level templates that let buyers simulate buy vs. service vs. retrofit scenarios over typical asset lifecycles.
Competitive landscape: incumbents, strategies, and recent moves
The market is characterized by a handful of global OEMs with deep installed bases and differentiated digital offerings. The report’s company intelligence synthesizes public disclosures, product literature, and field evidence to highlight competitive positioning without revealing confidential supplier performance metrics.
Worldwide Digital Generator Circuit Breaker (GCB) Market
- Hitachi Energy (Zurich, Switzerland) — A long‑standing leader in GCB technology, with a history of global deliveries and integrated digital offerings. Notable is their Digital GCB solution paired with the GMS600 platform for health aggregation, predictive maintenance workflows, and flexible deployment across on‑premise and cloud environments. Recent customer engagement initiatives (e.g., their GCB Customer Days in 2025) underscore a services‑led agenda focused on lifecycle management and sustainability themes.
- GE Vernova (United States) — A major supplier for a broad spectrum of plant sizes and typologies. Their product set emphasizes digital cooling optimization and comprehensive condition monitoring (CBWatch3), backed by updated services literature that highlights retrofit and maintenance pathways. GE’s strategic posture is to convert installed base into recurring aftermarket revenue via digital services and targeted retrofits.
- Siemens (Germany) — A technology leader advocating SF6‑free vacuum solutions that reduce long‑term environmental liability and OPEX through maintenance reduction. Siemens’ portfolio positions the vacuum route as a compliance‑friendly and low‑maintenance option that aligns with decarbonization priorities.
- Eaton (Ireland/USA operations) — Focused on medium‑voltage generator breaker performance optimized to IEEE duty classes, Eaton’s strength lies in engineered vacuum interrupter designs for smaller and mid‑sized generator sets, with emphasis on continuous current capability and reliability.
Key industry dynamics shaping vendor and buyer choices
- Standards and duty differentiation: GCBs must satisfy generator‑specific continuous current and short‑circuit duties that differ materially from distribution breakers. Procurement language that conflates the two is a persistent source of field failure and contractual disputes.
- Environmental regulation and technology substitution: The transition away from SF6 — driven by emissions policy and corporate sustainability targets — is accelerating adoption of vacuum interrupter technologies. Buyers should assess asset‑level tradeoffs between retrofit complexity, lifecycle OPEX, and regulatory risk.
- Digitalization as an operational lever: Embedded monitoring and analytics alter the value equation for spare parts, testing intervals, and workforce allocation. Pilot programs that demonstrate measurable uptime gains and maintenance deferral are now preconditions for capital approval in many utilities.
- Consolidation pressure and aftermarket economics: High CR3/CR5 concentration suggests bargaining power for incumbent suppliers to monetize digital and service capabilities. Buyers must design procurement processes that protect against lock‑in while capturing future upgrade optionality.
Strategic recommendations for 2026 (concise, actionable)
- Mandate digital readiness in all RFPs: Require native sensor telemetry, standard communication protocols (e.g., IEC 61850, Modbus TCP), and clear data ownership terms. Insist on demonstrable integration pathways to enterprise Asset Health platforms.
- Prioritize lifecycle TCO over headline capital cost: Use the report’s TCO calculator to compare buy, retrofit, and service models over a 10–20 year window; include outage cost assumptions specific to plant type and grid exposure.
- Start retrofit pilots for high‑value units: Deploy small, measurable pilots (3–5 units) that combine condition monitoring with predictive workflows. Use results to standardize retrofit specs and institutionalize altered maintenance KPIs.
- Embed compliance testing in acceptance plans: Tighten factory and site acceptance tests to the IEC/IEEE generator duty standards to avoid post‑commissioning nonconformances.
- Mitigate supplier concentration risk: Maintain dual‑sourcing options for critical components and negotiate spare‑parts consignment or guaranteed lead‑time clauses where feasible.
How to use the PW Consulting report in your 2026 decision cycle
- Immediate (0–3 months): Run the report’s fleet diagnostic to identify candidate units for digital retrofits and include mandatory digital clauses in any new RFPs being drafted.
- Near term (3–12 months): Execute retrofit pilots, finalize supplier scorecards, and negotiate service‑based contracts that align incentives for uptime improvements.
- Strategic (12–36 months): Implement an enterprise‑wide Asset Health Management approach, scale successful pilots, and reassess fleet renewal timing using the report’s scenario models.
PW Consulting’s Worldwide Digital GCB Market study offers the granular frameworks, vendor intelligence, and executable templates necessary to convert market insight into procurement and operational advantage in 2026. To preserve competitive value and encourage evidence‑based decision making, this release intentionally highlights directional findings and strategic prescriptions while directing practitioners to the full report for detailed segmentation, interactive dashboards, raw time‑series, and downloadable vendor scorecards.
For executives preparing budgets, retooling maintenance strategies, or assessing acquisition targets, the full report provides the empirical dataset and commercial tools needed to act with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Generator Circuit Breaker (GCB) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com