

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts 7.82% CAGR for Worldwide High-Speed Spectroscopy Cameras Market Through 2032

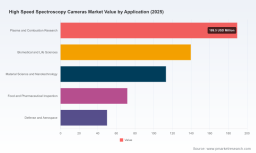
Worldwide High Speed Spectroscopy Cameras Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s new market study on Worldwide High Speed Spectroscopy Cameras delivers a focused, action-oriented perspective tailored for C-suite and technical leaders preparing strategy and investment decisions in 2026. The sector has shown resilient expansion — growing from roughly 395 million USD in 2020 to about 564 million USD in 2025 — and the report forecasts continued momentum through the 2026–2032 horizon with a compound annual growth rate of 7.82%, reaching an estimated 955.6 million USD by 2032. These macro dynamics create both opportunity and complexity: accelerating demand across biomedical, industrial inspection, and defense use cases, while advancing sensor architectures, software stacks and regulatory expectations reshuffle competitive advantage.
Worldwide High Speed Spectroscopy Cameras Market
Why this report matters for 2026 planning
-
Actionable foresight, not just numbers. The study translates market trajectory into prioritized decision levers: product roadmap sequencing, channel and partnership strategies, CapEx versus OpEx trade-offs for clinical customers, and near-term M&A opportunities for strategic buyers.
Worldwide High Speed Spectroscopy Cameras Market -
Operational due diligence support. For procurement and integration teams, we map technology risk to implementation timelines — critical when integrating high line-rate cameras into multimodal imaging systems used in operating rooms, research labs, or high-throughput production lines.
Worldwide High Speed Spectroscopy Cameras Market -
Regulatory and reimbursement navigation. The report synthesizes applicable regulatory pathways (e.g., ISO 13485, FDA 510(k) processes) and current reimbursement context that materially affect commercialization timelines for diagnostic and clinical imaging applications.
Market trajectory and its strategic implications
The high-speed spectroscopy camera market’s steady ascent through the first half of the decade reflects a confluence of factors: rising demand for spectral precision in clinical diagnostics and material characterization, broader adoption of hyperspectral imaging in industrial inspection, and continued miniaturization enabling OEM embedding. For 2026, this translates into three pragmatic implications:
-
Prioritize modular architectures. Buyers and systems integrators should favor camera and software platforms that decouple sensor upgrades from core system electronics — enabling faster responsiveness to sensor-driven performance improvements without full system redesigns.
-
Invest in low-noise, high-line-rate capabilities for clinical/biomedical playbooks. Emerging clinical applications (e.g., OCT-integrated spectral modules and NIR-based tissue perfusion monitoring) make cameras with both high line rates and low-noise characteristics strategic assets for device OEMs and hospital imaging centers alike.
-
Balance near-term revenue capture against long-term platform bets. Investors and product leaders must weigh the economics of premium sensor adoption (e.g., sCMOS and advanced SWIR detectors) against the growing market for compact, embedded hyperspectral modules that enable high-volume industrial deployments.
Competitive landscape — what the leading vendors signal
The market shows moderate concentration: the top three vendors command a meaningful share of installed capabilities, and the leading five account for a clear majority of market presence. This topology favors companies that combine differentiated sensor IP with strong application expertise and global channel access.
-
Andor Technology (Oxford Instruments): With deep technical roots in high-sensitivity sCMOS, EMCCD and CCD offerings, Andor’s Newton and iDus lines continue to be reference points for academic and clinical spectroscopy customers seeking low-light, high-fidelity capture.
-
Teledyne Princeton Instruments: Known for low-noise, high-speed CCD and sCMOS cameras, Teledyne’s product set is frequently chosen for Raman, hyperspectral and transient spectroscopy where signal integrity is paramount.
-
Hamamatsu Photonics and HORIBA Scientific: These established players bring a combination of detector R&D and instrument-level expertise — particularly relevant for near-infrared spectroscopy and deep-cooled, clinical-grade imaging modules.
-
Specim (Konica Minolta), Headwall Photonics and HySpex: Specialization in push-broom hyperspectral cameras and integrated systems positions these firms to win in industrial inspection and research imaging segments that demand line-scan throughput and broad spectral bands.
-
XIMEA, Photon etc., BaySpec: The emergence of miniaturized, OEM-friendly modules from these vendors accelerates adoption in embedded and device-integrated applications, an area attractive to medtech OEMs and automated inspection integrators.
Recent product activity underscores a rapid cadence of capability refresh. Notable announcements in 2025–2026 include a high-speed NIR–SWIR push-broom camera introduced by a leading hyperspectral manufacturer, new rectangular-pixel SWIR camera roadmaps presented at major industry forums, and updated SWIR hyperspectral datasheets from established distributors. For 2026 decision-makers, these moves mean price/performance thresholds will shift, and first-mover advantages will accrue to organizations that align procurement timing with platform refresh cycles.
Technology trends shaping procurement and R&D choices
-
sCMOS and EMCCD evolution: The drive for higher quantum efficiency at reduced noise continues to push sCMOS into a wider set of spectroscopy and fast-imaging use cases. Systems architects should evaluate camera latency, thermals and readout modes as core selection criteria.
-
SWIR and InGaAs advances: Extended spectral coverage is enabling material differentiation in industrial and biomedical contexts, but SWIR economics and integration complexity require careful systems-level validation and thermal management planning.
-
Hyperspectral vs. multispectral trade-offs: For many applications, faster push-broom or snapshot hyperspectral systems provide operational advantages. Report guidance helps teams decide when spectral fidelity justifies higher system cost versus targeted multispectral solutions.
-
Miniaturization and OEM integration: Miniature cameras and embedded modules open new productization pathways for device OEMs, accelerating go-to-market when paired with robust software abstraction layers and standardized interfaces.
Regulatory, reimbursement and clinical adoption factors
For players targeting diagnostic and clinical workflows, regulatory compliance and reimbursement posture materially influence time-to-market. Key considerations covered in the study include:
-
Quality management and device pathways: Conformance with ISO 13485 and alignment with FDA 510(k) expectations for Class II imaging systems are baseline requirements for clinical deployments.
-
Reimbursement landscape: High-speed spectroscopy applications such as near-infrared monitoring for wound or flap management currently operate within established Medicare coverage frameworks; however, the absence of specific CPT updates for 2025–2026 means commercial models must combine device-level evidence generation with local coverage strategies.
-
Clinical integration: Hospitals’ CapEx and research investment trends favor multimodal platforms that can be upgraded with spectral modules; vendors that provide proven integration kits, clinical validation support and interoperability roadmaps will accelerate adoption.
What the PW Consulting report delivers — practical, executable content
-
Tactical vendor scorecards and capability maps that help procurement teams short-list suppliers based on performance, integration risk and service footprint.
-
Productization playbooks for OEMs that cover sensor selection criteria, thermal and firmware integration templates, and recommended testing sequences for clinical and industrial validation.
-
Regulatory checklists and time-to-market models estimating resource needs for ISO 13485 alignment and FDA 510(k) filings in diagnostic use cases.
-
Commercial models for investors: scenario-driven revenue projections, margin sensitivities and acquisition candidate screening criteria tied to platform stickiness and IP defensibility.
-
Use-case impact analyses that translate sensor specs into operational outcomes for biomedical imaging, material inspection and high-throughput manufacturing.
How to use this intelligence in 2026
-
For corporate strategists: use the report to prioritize R&D and M&A agendas — focus on complementary sensor IP, software analytics and go-to-market reach that accelerate platform adoption.
-
For product managers and systems integrators: align procurement and prototype cycles to vendor roadmap announcements; leverage modularity to defer large CapEx until sensor improvements are validated.
-
For hospital and lab procurement leaders: request interoperable, upgradeable modules and insist on clinical evidence packages and regulatory readiness as part of bidding criteria.
-
For investors: prioritize companies that combine differentiated sensor roadmaps with recurring service or software revenue streams to mitigate hardware commoditization risk.
Where the report withholds and why
The study is deliberately designed as a decision-enabling product: it surfaces strategic findings, vendor insights and implementation playbooks while preserving detailed node-level segmentation tables, precise regional and application revenue breakdowns, and proprietary vendor scoring matrices for subscribers. This “teaser” approach ensures readers can rapidly assimilate the strategic implications while requiring a deeper engagement to access the granular data needed for high-stakes procurement or transaction diligence.
Next steps
For executives preparing 2026 roadmaps, the report serves as both a yardstick and a playbook. PW Consulting recommends an immediate 90-day sprint to: (1) test modular integrations with one or two leading sensor suppliers, (2) initiate clinical or industrial validation pilots tied to reimbursement or productivity KPIs, and (3) conduct a regulated-product readiness audit covering ISO 13485 and 510(k) pathways. These steps de-risk later-stage scale-up and align R&D investments to the market’s 7.82% CAGR trajectory through 2032.
To explore the full set of findings, proprietary vendor assessments and the complete dataset underlying our forecasts, please consult the full Worldwide High Speed Spectroscopy Cameras Market report on the PW Consulting website.
For detailed analysis of this topic, please visit the official page: Worldwide High Speed Spectroscopy Cameras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com