

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pod Hotel Market Set to Expand at a 7.15% CAGR, Outlook Strengthens

Pod Hotel Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence Brief
PW Consulting today releases a forward-looking industry brief on the global Pod Hotel Market that is designed to inform C-suite decisions, institutional investment theses, and operational playbooks for 2026 and beyond. Grounded in a 2020–2025 historical baseline and a 2026–2032 forecast horizon, the study synthesizes primary interviews, operator financials, site-level economics and regulatory intelligence into a compact, action-oriented resource for executives who must move from opportunity recognition to deployable strategy.
Pod Hotel Market
Executive snapshot
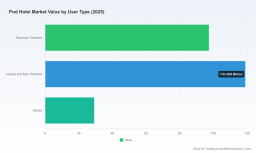
The pod hotel sector has transitioned from a niche urban curiosity to a repeatable product class with measurable unit economics and growth runway. On an aggregate basis the market expanded from roughly USD 170 million (2020) to USD 245.5 million in our base year (2025). Using 2026 as the launch-point for our forecast, we model the sector to grow at a compound annual growth rate of 7.15% through 2032, reaching approximately USD 398.1 million by the end of the forecast window. These headline metrics underscore a healthy growth trajectory that is large enough to attract mainstream hospitality capital while remaining sufficiently fragmented to reward early movers with disciplined execution.
Pod Hotel Market
Why 2026 is a pivot year
-
Capital readiness: Lower per-unit construction cost and modular manufacturing make greenfield and conversion strategies capital-feasible faster than traditional hotels. Industry benchmarking indicates pod unit construction typically sits materially below that of full hotel rooms, delivering faster payback periods in properly located projects.
Pod Hotel Market -
Operational scalability: Standardized, tech-driven pod designs enable high levels of automation and remote management, compressing staffing needs and enabling operators to replicate concepts across geographies.
-
Customer segmentation and channel evolution: Demand from time-constrained travelers (including transit and short-stay segments) alongside budget-conscious urban leisure guests provides a multi-channel demand base. At the same time, distribution and pricing dynamics (OTAs versus direct channels) are evolving and materially affect RevPAR capture.
-
Regulatory clarity and safety standards: As local authorities adopt clearer guidance on compact accommodation—fire safety, ventilation, privacy and shared facilities—compliant designs are becoming a necessary competitive moat.
Market dynamics that matter to decision-makers
-
Unit economics drive site strategy. Our analysis shows pod construction benefits from factory modularization and lower on-site labor intensity, enabling deployment cycles measured in months rather than years. This materially reduces time-to-revenue for new sites and supports portfolio rollouts driven by site economics rather than pure brand expansion.
-
Fragmented competitive structure. The market remains fragmented: incumbent specialist operators and new entrants coexist, leaving white space for scalable platforms and local partners. Market concentration metrics indicate that the leading firms do not yet control a dominant share, creating acquisition and roll-up opportunities for strategic buyers and PE sponsors.
-
Cost profile and capex benchmarking. Industry sources point to a broad capex envelope for pod units that is substantially lower than conventional hotel rooms—supporting payback horizons in the 2–4 year range for well-located assets. These capex differentials alter hurdle rates and permit more aggressive yield-management and transient pricing strategies.
-
Regulation and standards are a gating factor. Operators must design to local building codes covering fire safety, ventilation, privacy and accessibility. Early engagement with regulators and adherence to evolving standards are essential to avoid retrofit costs and operational restrictions.
Competitive landscape — positioning and strategic moves
The competitive set is varied, comprising purpose-built capsule specialists, hybrid lifestyle brands, airport-centric sleep solutions, and modular system providers. Key operator archetypes include minimalist sleep-first chains, premium “cabin” concepts, airport transit specialists, and franchisable urban boutique operators. Representative firms we analyze in detail include:
-
nine hours Inc. (Tokyo) — a minimalist, sleep-optimization chain integrating technology and health partnerships; recently announced a new Shinjuku property slated for mid-2026 launch with an institutional collaboration focused on sleep and health monitoring.
-
First Cabin (Japan) — positions cabins as an elevated alternative between capsule and business hotels, targeting travelers seeking compact but premium amenities and expanding selectively into international leisure gateways.
-
YOTEL (London) — adapts an airline-cabin-inspired model across urban and airport sites with a strong emphasis on tech-enabled guestrooms and public spaces.
-
Bobobox (Indonesia) — a tech-forward, modular operator scaling rapidly in domestic markets and building a playbook for regional rollouts; announced significant network expansion activity in recent years.
-
GoSleep (Finland), napcabs GmbH (Germany), Sleepbox (USA), and The Pod Hotel (New York) — collectively illustrate the breadth of use cases from airport transit pods and workplace rest solutions to urban lifestyle capsule hotels.
Recent operator developments—new openings, network expansions and construction starts—confirm that both specialty players and mainstream brands are actively testing formats and channel mixes. For investors, this means a market where occupancy uplift and pricing premium derive not only from location but also from brand positioning and tech-enabled guest experiences.
What the PW Consulting brief delivers (practical assets)
-
Decision-ready financial models: customizable unit-economics templates for capex, opex and scenario testing that allow rapid evaluation of single-site pilots and five-site rollouts.
-
Site-selection framework: a replicable heatmap methodology that blends demand density, transit flows and regulatory feasibility to prioritize target markets without exposing sensitive segmentation tables in this preview.
-
Operational playbooks: staffing, maintenance, and tech-stack blueprints designed to lower operating costs and stabilize guest satisfaction in mixed-use and airport environments.
-
Regulatory and safety checklist: a curated checklist of local-code touchpoints and certification pathways to accelerate permitting and reduce retrofit risk.
-
Partnering and distribution matrix: strategic guidance on OTA vs. direct channel mix, franchise structures and capex-lite partnerships with landowners and transit hubs.
Strategic imperatives for 2026
-
Adopt a “pilot-and-scale” approach. Run tightly instrumented pilots (3–5 sites) to validate unit economics before committing to larger rollouts. Use pilots to refine yield management, channel strategy and guest experience frameworks.
-
Prioritize compliance-led design. Invest up-front in designs that meet or exceed local safety and ventilation standards to minimize time-to-market and long-term retrofit exposure.
-
Leverage modular build and supplier partnerships. Lock in modular pod suppliers and factory capacity to control cost, quality and deployment schedules—critical inputs for delivering on the short payback promise.
-
Differentiate via experiences and adjacent services. For urban leisure and business segments, adjacency services (luggage storage, micro-workspaces, health/sleep partnerships) free up pricing power beyond base bed-nights.
-
Manage channel economics actively. Optimize OTA relationships with tailored promotions and loyalty integrations to protect direct-booking margins while maintaining reach.
Risk map and mitigations
-
Construction and supply-chain volatility — mitigate through long-lead procurement, modular contracts and local supplier diversification.
-
Regulatory uncertainty — engage early with authorities, maintain adaptive designs and budget for incremental compliance costs.
-
Demand concentration — diversify site typologies (airport, urban core, tourist corridors) to smooth occupancy cycles.
-
Labor and operations — deploy automation where it preserves guest experience and reduces routine labor dependency.
Next steps and how to use this intelligence
For executives preparing 2026 capital plans, this brief is structured to accelerate decision cycles: run our unit-econ templates against your target markets; deploy a two-quarters pilot budget; and select modular supply partners to shorten development timelines. PW Consulting’s full report provides granular regional and user-type segmentation, channel-by-channel revenue build-ups, and pro forma case studies. Those detailed appendices and proprietary models are intentionally gated to preserve commercial value and are available through our research portal.
In summary, the pod hotel market presents a near-term pathway to asset-light expansion, attractive payback intervals and differentiated guest propositions — but success hinges on disciplined site selection, compliance-centric design and a technology-enabled operating model. PW Consulting’s new brief equips leaders with the operational templates, financial models and competitive diagnostics required to convert potential into profitable scale in 2026.
For detailed analysis of this topic, please visit the official page: Pod Hotel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com